Tag: American Economic History

  • The Stock Market Crash of 1929 and the Beginning of the Great Depression

    The Stock Market Crash of 1929 and the Beginning of the Great Depression

    Before You Begin

    If you don’t know the background of this complicated story, you might want to first read a shorter version that introduces some of the key factors explaining the Crash and the Depression. See,

    Introduction to the Stock Market Crash of 1929 and the Beginning of the Great Depression

    Before reading this essay, I strongly recommend you see the PBS video on YouTube. Type in Stock Market Crash 1929. Look for US – The Crash of 1929 (PBS), ALLHISTORIES – PLAYLIST. 

    Documentary broken into 6 parts to show commercials. Or buy the video on Amazon Prime. Great documentary with wonderful photos, videos, and scenes from movies of the 1920s and the crash. Shows what a crazy time it was.

    The video is also a great introduction to Andrew Ross Sorkin, 1929:  Inside the Greatest Crash in Wall Street History – and How It Shattered a Nation. This book concentrates on the roles played by a small number of key men; the video also focuses on these men and their social environment.

    The following quote that introduces this essay is from Mr. Sorkin’s book.

    The stock market is a mirror whose function it is to provide an image of the underlying or fundamental situation. Cause and effect run from the economy to the stock market, never the reverse. An unstable economy can be disturbed by all kinds of incidents that on the surface appear extraneous.

        Jesse Livermore

        Famous stock market speculator 

    INTRODUCTION

    The usual reason given for the Great Depression – the stock market crash in October 1929 and the later collapse of the banking system – does not tell the whole story. Available economic data (there were no national income accounts in 1929) indicate that a recession had already begun before the stock market crash. The crash of October and November of 1929 was a catalyst that made the recession worse, but the partial stock market recovery in early 1930 did not end the recession. Industrial production continued to fall quickly and unemployment rose rapidly in 1930. As the economy sunk lower into depression and unemployment reached catastrophic heights, continuing farm and businesses failures over the next two years wiped out thousands of small rural banks and threatened total financial collapse in early 1933.  

    For a fuller explanation, we have to go back to the 1920s to see additional reasons for the stock market crash of 1929 and the rapid decline in output at the beginning of the Great Depression. We have to look at the international financial situation and how it contributed to America’s depression, including the attempt after World War I to reestablish the pre-war gold standard.

    Economic Growth in the 1920s:  Industrial Production and the Real Economy

    There was a spectacular increase in industrial production starting in the 1870s and continuing into the 1920s. The 1920s were a decade of economic growth and development. The large increase in manufacturing output in this decade was driven by innovation in new and greatly expanding industries and companies.

    The structure of the economy changed in the 1920s, with consequences for the stock market and financial markets in general. Industrial production, especially of large corporations, were a larger and more important part of the total economy. In contrast, agriculture stagnated in the 1920s. In 1920, agriculture accounted for 18% of Gross Domestic Product (GDP, a measure of total output); by 1929, agriculture’s share had fallen to 12%. 

    The foundations of the new economic structure were corporations building large-scale manufacturing plants with electricity replacing steam as the power source, new steel machinery, lower transportation and information costs, increased productivity (output per worker), and lower unit cost.

    The drivers of economic growth were the new and developing technologies.

    • consumer durables, especially autos, electrical appliances, and radios. 
    • electricity utilities.
    • mass communication (phones) and entertainment (radios, phonographs, movies). 
    • mass-produced consumer nondurables such cosmetics, toiletries, processed food, and cigarettes.

    Steel was the basis for the new auto industry, modern machinery, and skyscrapers. The amount of railroad track increased eight times from 1870. Thousands of miles of paved roads were built in the 1920s. The telephone system became ubiquitous and transcontinental with an increase in transmission bandwidth.

    The 1920s was a decade of economic growth and development but it was uneven. It began with a severe deflationary (prices going down) recession as the economy adjusted from the World War I wartime economy to a peacetime economy. Economic growth began in 1922. The stock market grew rapidly in 1922 and 1923, and kept growing until late in 1929. But in 1927 and 1928, the economy hardly grew at all. Growth for the two years was about 1% per year. One reason for the 1927 stagnation was the bursting of the Florida land boom bubble (in video). This bubble showed large numbers were willing to speculate on something they knew nothing about but thought they would get rich quick. (See Marx Brothers movie Cocoanuts. Groucho was wiped out by the market crash. The movie, ironically, was released in 1929.)

    Another reason was the total shutdown of Ford in 1927. Henry Ford finally scrapped the Model T and retooled his plants to produce an entirely new auto. He laid off 60,000 workers. There were spillover effects on other major industries such as steel, tires, and glass. Full production was not reached until 1929.

    But strong economic growth returned in 1929. The annual growth rate was 6%. Industrial output grew faster. This strong growth was led by increased production of autos, radios, electrical appliances, and new consumer goods.  

    The economic expansion of 1921-1929 was based on the development of new technologies like radio and the expansion and sales of consumer durables like autos. The urban and regional buildout of the electric grid (and lower rates) led to demand for new electrical appliances and large productivity gains in mass production. Car ownership increased from about 7 million in 1919 to 27 million in 1929, on average about one car per household. This created demand for complementary products and services such as steel alloys, refined oil products, gas stations and mechanics, paved roads, and motels. 

    Radio (RCA) and others went from selling hobby kits in 1919 to sales of $60 million in 1922 to sales of $426 million in 1929. (Figures on car and radio sales are from digital history.uh.edu, “The Consumer Economy and Mass Entertainment.”)

    Auto production was an important part of the industrial economy in the years leading up to the stock market crash. The auto industry produced approximately 4 million cars in 1926, fell to 3.1 million in 1927 because of the Ford shutdown, recovered in 1928, and reached a record 5.4 million in 1929. 

    Sales of these products was greatly enhanced by a large increase in consumer credit. General Motors started its own credit operation in 1919. Sears quickly followed by offering installment plans on appliances and other products. (Singer Sewing Machine Company started an installment payment plan in the 1800s.) Hundreds of new consumer credit companies were started in the 1920s. 

    New industries were created or greatly expanded in new types of passive entertainment (movies and phonographs) and mass consumption products like packaged food, cigarettes, toiletries, and cosmetics. Marketing and advertising encouraged consumption.

    Economic growth and industrial production helped to create and expand a new middle class including managers, engineers, accountants, and lawyers. So did the expansion of the financial sector. This middle class had rising income and savings. They provided many of the new speculators in stocks in the 1920s.

    Industrial Corporations and Stock Markets

    Starting in the late 1800s, new and rapidly-growing industrial corporations needed large amounts of investment and expansion capital, far more than what they could generate from internal cash flow. Capital was needed to take advantage of scalability (economies of scale).

    The stock market, and the financial sector in general, had become increasingly important to the American economy during the 60 years leading up to the crash of 1929. In the 1920s, the financial sector doubled as a percent of the national economy. Its growth paralleled the financial requirements of new and growing companies. New, capital-intensive, large, and growing corporations needed investment capital far in excess of what company founders and rich backers could provide. The solution was the creation of the publicly financed, limited liability corporation. The canals starting in the 1820s, the railroads starting in the 1830s and then the industrial corporations starting in the 1870s issued stocks and bonds to the public to finance their capital requirements. In an expanding economy, investors could expect to collect dividends and watch their stocks appreciate in price.  

    Equity capital (stock) had the advantage over bonds that the corporation was not obligated to buy back the securities. Or pay a fixed amount of interest. But investors were “locked-in.” This might have limited the attraction of equity investment except that investors in public companies could exit by selling their stock to others in “secondary” markets like the New York Stock Exchange (NYSE).

    So large companies and stock exchanges were connected, complementary, and grew together.

    The Stock Market Crash of 1929

    In the 1920s, the “stock market” meant the New York Stock Exchange. This is where the shares of most large companies were bought and sold. 

    The New York Stock Exchange was a private company, owned by its members. Until the 1920s, most stock traders were full-time professionals. There were no rules or laws. Traders lied, cheated, and deceived among themselves. In the 1920s, they could now also do this to naïve small investors. They viewed small investors as sheep to be shorn.

    In 1929, there were 1,334 companies whose stock was traded on the New York Stock Exchange. This was a tiny percent of all the farms and businesses in America. But these were most of America’s largest companies. They accounted for much of the economic growth in the 1920s.

    Many of the companies on the NYSE dominated their industries and markets. They had exhibited large increases in sales and profits over time, which led to high expectations for rapid future growth in company sales and profits.

    The impression that “everyone” was playing the stock market is an exaggeration. By 1929, fewer than one out of ten families had money in the market. They were about half of all families with financial assets. Stocks, like consumer durables, were often bought on credit, or “margin,” by some of the speculators. About half of small investors bought on margin. Typically, the investors put up 10 – 20% of the value of the stock and borrowed the other 80 – 90% from the broker. The stock was collateral for the loan. The broker, in turn, borrowed the money from banks and other institutions with spare cash. Brokers’ loans (also known as “call money” because they were overnight loans and could be “called” in one day) increased  about $1 billion in 1920 to $4.4 billion in early 1928 to $8.5 billion in October 1929. 

    About 80% of the brokers loans came from sources outside the banking system, including overseas, so Fed pressure on member banks not to make call loans had little effect. The loans seemed safe as long as the stock collateral increased in value. Interest rates were higher than alternative short-term loans.

    Small investors leveraged their bets even more by using margin to buy stock in new investment trusts. Investment trusts were similar to today’s mutual funds except they were also leveraged – selling both shares to investors and floating bonds. Then leveraged investment trusts bought shares in other leveraged investment trusts. Alas, leverage also worked on the downside; owners of shares in investment trusts were wiped out even when the shares of the underlying companies still had some value.

    The speculative bubble, when stock prices rose much faster than earnings and earnings per share, began in March 1928. As measured by the Dow Jones Industrial Average, stock prices doubled and reached an all-time high the day after Labor Day,  September 3, 1929. The Dow Jones index went from 200 to 390. The total value of stocks had gone from $25 billion to over $50 billion, in an economy of $100 billion.

    By 1929, investors had high expectations about the percent increase in stock prices. Based on the yearly increases from the beginning of 1928 to September 29, conservative investors who paid cash and bought a diversified portfolio of stock like the Dow Jones index, expected returns of 50%/year. If they bought stock on 20% margin, they expected to make over 200% a year; on 10% margin, over 400% a year.

    Investors who bought leveraged investment instruments like investment trusts with margin expected an even higher yearly return.

    Speculators bet on companies like Radio (RCA). RCA was up 500% since beginning of 1928.

    There were also short-term bets based on rumors about big pools of capital going into a stock. Often a big speculative pool started buying a stock. They paid for a lot of publicity, including bribing financial journalists to hype their stock. As more small speculators piled in, the pool started selling. Small investors were left holding a bag of stocks with rapidly falling prices. (See video)

    While corporate profits were going up, stock prices were going up even faster. This led to record high stock price/earnings per share (P/E) ratios. This was viewed as an indication of rising confidence that the market would continue to go up. But the market’s P/E ratio would have to continue to rise if the market continued to go up at 50% a year.

    The Dow Jones index reached its high on September 3, 1929. The market slowly declined for a few weeks and then crashed at the end of October. The market was down nearly 13% on Monday, October 28. The climax, in massive volume, was the next day, October 29 (Black Tuesday), when the market fell 12%. The total drop from its September high to the end of October was 40%.

    By the end of November 1929, the stock market had fallen 50% and had wiped out all of the speculative gains since early 1928. In early 1930, it reversed direction and regained 40% of its 1929 losses. Volume was high. But in April commodity prices started to fall again. Industrial production continued to decline all through 1930. Unemployment rose quickly. The market turned down again. By late 1930, the stock market had fallen below its November 1929 lows.

    The entry of large “pools” of outside speculative capital and small investors into the stock market was one reason for the bubble. This was something new; until the 1920s, stock market participation was an insider’s game of professional speculators. But now insiders and investment managers of outside capital could manipulate stock prices at the expense of small investors.

    Partners of the largest investment banks, market analysts, government officials, congressional committee hearings, and Fed officials had private doubts or warned the public of the dangers of the “over-priced” market. But their messages were drowned out by reassuring and optimistic statements of market boosters like Charlie Mitchell of National City Bank who had done much to encourage margin buying by new small investors. Negative comments were ignored by speculators caught up in the frenzy. Instead, they listened to advisors like the foremost astrologer of the day, who predicted the market would go up forever. Presumably to the stars (see video).

    The stock market crash of October 1929 did not come as a surprise to everyone. Some of the biggest speculators like Jesse Livormore and investment bankers like some of the partners at J.P. Morgan sold their positions before the crash. Livormore shorted the market (bet it would go down); when he came home on the worse day of the crash, he told his wife he had made more money that day than any other day in over 20 years of speculating. 

    Before World War I, about a half a million shares were traded on a typical day. In 1928 and 1929, volume was rising rapidly, averaging about five million shares a day. On October 29, volume hit an all-time high of 16 million shares. Stock prices were on average six times higher than earlier in the 1920s, so that the combination of more speculators, and more of them acting like short-term traders, led to a huge increase in the dollar value of the stock market.

    Investors’ and large speculators’ margin of 10%-20% was wiped out in just two days, October 28 and October 29. Margin calls for more cash went out; if not provided immediately, the broker tried to sell the underlying stock, increasing supply. Banks and other providers called their loans. All this led to a cascade of hitting stop-loss orders and more margin calls.  In the fall of 1929, about $2 billion of brokers’ loans were pulled out or wiped out.

    Large investment pools, like the one controlled by Billy Durant (who put together General Motors and then drove it into bankruptcy), speculated on margin and also lost heavily in the stock market crash. When stock prices fell, they doubled down – buying more stock – only to see their losses increase. Durant personally lost $18 million. One of the richest men in America (on paper) in 1929, he never recovered and finally declared personal bankruptcy in 1936. Jesse Livermore, probably the most successful individual speculator in the 1920s, made a series of bad bets in the 1930s and committed suicide in 1940. 

    The large, sharp decline in the stock market had an immediately negative impact on aggregate (total) demand, especially demand for consumer durables usually bought on credit and luxury goods and services. Expectations of rising personal wealth and a higher standard of living from rising stock prices were shattered.

    After the bubble burst, the New York Fed reacted quickly. In the six months after the crash, the New York Fed injected $500 million of liquidity into the banking system. It cut its rediscount (loan) rate to banks from 6.0% to 2.5%. New York banks, in response, took over $1 billion in brokers’ loans. No major New York bank failed. The market rallied in the first half of 1930. It appeared the crash had been contained. It wasn’t.

    It was not because of:

    • the weaknesses in the American economy, especially the farm sector.
    • the fragile international financial system, based on the gold standard, constructed after World War I.
    • the fragmented American banking system watched over by passive regional Fed banks.
    • the rising importance of the financial sector, and how it interacted with the real economy.

    The Farm Economy

    The period from the mid-1890s to 1918 has been called the “Golden Age of American Agriculture.” Expansion into new areas, rising demand from American and European urban areas and industry, rising prices, and World War I (large food exports to England) all led to prosperity for the farming sector. 

    In addition to the usual seasonal loans, farmers went deeper in debt to expand acreage (the average size farm increased) and buy large amounts of new equipment, including tractors, to increase productivity and lower unit cost. They also bought new cars (mostly Model T Fords) with borrowed money. During this period, thousands of new banks were started in rural areas to finance this expansion.

    Agriculture was still a major part of the economy. In 1920, the farm population was 30% of the total U.S. population.  Almost 50% of Americans lived on the farm or in towns with fewer than 2.500 people, many of them in rural areas dependent on agriculture.

    The farm economy went into recession during the price deflation after World War I and remained stagnant during the 1920s. Farm prices fell in half after World War I and then slowly declined as American farmers lost their European markets. European demand fell because of the violence, chaos, and disruption caused by the war. 

    Attempts by the Hoover Administration to stabilize farm prices through purchasing surpluses failed. In 1930, the market price of wheat fell in half.  Further large decreases after 1930 in farm prices and the “Dust Bowl” collapsed the agricultural sector, farmers defaulted on loans at a rate of 1,000 a day, resulting in the bankruptcy of thousands of small, rural banks. 

    Eight rural states set up deposit insurance programs before and during the 1920s. All failed by 1929. Depositors (savers) were ruined along with the banks since there was no federal deposit insurance before 1933.

    Large industrial corporations created and dominated markets. The raising of large amounts of financial capital fueled buying the more efficient capital equipment and industrial expansion. Large industrial companies employed factory workers, office workers and new types of professionals like engineers, chemists, accountants, and managers. Combined with the stagnation of the rural sector, America became an urban, industrialized society.

    Investors in corporate stock did not always understand why stock prices were rising. Mass production processors and assemblers had high fixed costs in capital equipment. Some of it was financed with debt, creating financial leverage. Companies had to run at a high percent of rated capacity to make a profit. A small increase in sales (output) resulted in a leveraged increase in profit. Stock prices rose with rising profits; expectations of future increases in profits led to higher stock price to earnings (P/E) ratios, also increasing stock prices. This worked in reverse, starting in late 1929. Decreases in sales led to leveraged decreases in profits. Stock prices fell. Expectations of further decreases in profits lowered P/E ratios causing even lower stock prices.

    Real incomes rose in the 1920s. But, like today, income and especially wealth was concentrated.

    One estimate is that about one-third of all income was going to the top 5%. Sales of luxury goods and services soared. In contrast, farm families experienced a fall in total real income. 

    Demand for many consumer durables was partly paid for with a large increase in consumer debt called installment loans (buy now, pay later). As an expanding urban middle class and working class financed their rising standards of living partly through increased borrowing, household debt rose faster than income. By 1929, about 60% of cars and 75% of all radios were bought on credit. (A top-of-the-line radio cost as much as the average cost of a car!) Total consumer debt doubled in just four years, going from $1.4 billion in 1925 to $3.0 billion in 1929. Hundreds of new banks and finance companies were started to provide consumer credit.

    Home ownership financed by new forms of mortgage debt rose rapidly. Mortgage debt rose over eight times from 1920 to 1929. Hundreds of new “saving” banks were started to supply mortgages. 

    Household balance sheets were leveraged with consumer debt and mortgages backed by illiquid assets as collateral that quickly lost market value starting in the fall of 1929. Even as savings were being wiped out, families still had to make installment and mortgage payments.

    By October 1929, the economy was already in recession. Railroad car loadings and steel production had been falling since summer. The Fed’s Index of Industrial Production was also declining. Auto inventories were rising. But a general recession wasn’t recognized and declared until late in 1929. These numbers had little influence on analysts or investors.

    1930

    The recession was sudden and severe. Industrial production fell about 5% in October and another 5% in November. The contraction continued into 1930; industrial production fell another 30%. Unemployment doubled, from about 1.5 million (3% of the workforce) in the summer of 1929 to about 3 million (6%) in the spring of 1930, and then rose to about 5 million (10%) at the end of 1930. At least 25% of American families – a higher percent of non-farm families – were hit by unemployment sometime before the end of 1930. About half of the Great Depression’s total decrease in industrial production and about half of the increase in unemployment had already occurred by late 1930. Families experiencing unemployment couldn’t meet loan payments. (Most urban families were one-income families. Also, there wasn’t unemployment benefits like today.)

    In 1930, farmers were hit with lower prices, the Dust Bowl (huge dust clouds), loss of deposits in local failed banks, and inability to make loan payments on equipment. Farmers started to lose their farms; banks foreclosed on about 100,000 farms in 1930. (See the movie and/or read the book about this – The Grapes of Wrath.) The Dust Bowl continued until 1940, helping to wipe out many more farmers (see PBS video on the Dust Bowl; the dust clouds are unbelievable).

    Demand for consumer durables was especially hard hit. Car sales were 5.4 million in 1929, falling about one-third to 3.4 million in 1930. (At the bottom of the depression, auto production would fall by 90%.) Sales went from $3.5 billion in 1929 to $0.8 billion in 1932. Repossessed and used cars glutted the market. (Good for my grandfather; he bought a used truck in the 1930s for $30 to start a small business. The seller had to teach him how to drive.)

    AFTER 1930 – A QUICK SUMMARYAs the Great Depression got worse, stock prices kept going down, about 5,000 more banks went under wiping out depositors, unemployment rose to catastrophic heights, families couldn’t meet loan payments and lost their houses and cars.Eventually, almost half of all mortgages were in default.When the worse was over, real GDP fell by about 25% and nominal GDP went from about $100 billion in 1929 to about $50 billion in 1932. In 1929, corporations made total profits of about $10 billion; in 1932, they lost about $3 billion. Business investment disappeared.The depression and consequent disappearance of corporate profits (earnings) had consequences for stock prices. Using valuation metrics like price/earnings (P/E) ratios, there was no support level, no bottom, for stock prices. The other support for stock prices – dividends – also fell drastically as profits disappeared. Trading volume fell, from an average around 10 million shares per day in October 1929 to around a half a million shares per day in 1932.By 1932, market indexes had fallen 80-90% from October 1929.The negative reinforcing feedback effects between the real economy and the financial sector created the Great Depression. Again, the size of the total economy was about $100 billion in 1929. Between 1929 and 1932, stocks (and stockholders) lost about $30-$40 billion in value. Total bank credit fell $20 billion.

    WAGES AND PRICES

    Wages and prices acted differently at the beginning of the Great Depression compared to earlier recessions. The Consumer Price Index (CPI) went down only 2.6% in 1930. Nominal (current dollar or money) wages in the large industrial corporations, and other large companies, stayed virtually constant in 1930. Industrial prices also did not decline. Instead, large manufacturing firms laid off employees and cut production, watching sales and profits plummet. Investment stopped, hurting the capital goods sector. The question all this raises is:  Why didn’t large companies quickly cut wage and prices, as in prior recessions?In a series of conferences in November and December 1929, President Herbert Hoover urged the leaders of the largest companies not to cut wages. Many corporate presidents agreed, including the presidents of General Motors, Ford, General Electric, Westinghouse, Standard Oil, U.S. Steel, Du Pont, Firestone, and Goodrich. The idea was that by not cutting the wages, and therefore income, of their workers, they were helping to limit the fall in overall (aggregate) demand. Keeping wages and thus prices high probably contributed to the large decreases in demand for consumer durables. As demand and output fell, these companies laid off workers, contributing to the rapid increase in unemployment. It was only in late 1930 and 1931 that large companies began cutting wages.In 1933, President Franklin Roosevelt had Congress pass the National Recovery Act (NRA), an economy-wide, mandatory version of President Hoover’s voluntary program.


    FINANCING ECONOMIC GROWTH AND DEVELOPMENT IN THE 1920S
    The financial sector as a whole was a growing part of the economy in the 1920s. Finance doubled as a share of GDP with most of the growth coming in the second half.The raising of large amounts of financial capital fueled the economic expansion, not just on the supply side but also on the demand side.An expanding urban middle class financed its rising standard of living partly through increased borrowing; household debt rose faster than income. In addition, mortgage debt rose rapidly. Household balance sheets were leveraged with debt backed by illiquid assets that quickly lost market value starting in the fall of 1929.The purchase of consumer durables such as autos, radios (some cost as much as cars), furniture, and some electrical appliances was usually financed with debt, often with money borrowed at the new consumer finance companies. Miss one payment and the product was repossessed. One of the largest banks that specialized in car loans, controlled by Henry Ford’s son Edsel, went under. 

    THE AMERICAN BANKING SYSTEM AND THE FED

    At the beginning of 1929, the United States had 25,000 banks. Most, about two-thirds, were outside the Federal Reserve System (the Fed). States and the federal government had passed laws to protect local banks from competition from larger banks by limiting the geographical reach of banks. The small rural banks depended on the health of the local farm economy. It should have been an alarm bell as thousands went under in the decade before the crash.Between 1929 and 1933, the U.S. banking system – unregulated, fragmented, without deposit insurance – went through waves of bankruptcies as farmers, businesses, and consumers defaulted. In the two years 1929 and 1930, about 10% in of the total number of banks failed. About a third of all banks would disappear during the Great Depression. Depositors lost their savings. Farmers and processors could not repay loans and small, local banks went under. Solvent farmers could not get credit to produce. Urban and suburban banks started to go bankrupt as consumers, local businesses, and homeowners defaulted on loans. At the depth of the depression, half of all mortgages were in default.

    Why did not the Fed save the banking system from collapse?  One of the Fed’s powers was to be the “lender of last resort” to member banks. Banks in a liquidity squeeze could borrow at the rediscount window at the Fed banks. This was limited since one-third of banks were members of the Federal Reserve System. But they were the larger banks; smaller banks typically held part of their reserves at larger banks. As the economic crisis deepened, small, local banks began asking for their deposits at the larger banks. This reduced reserves at the larger banks which were not balanced by new liquidity from the Fed.

    Through all this, the eleven regional Fed banks outside of New York and the governing board in Washington did virtually nothing. Controlled by local bankers and manufacturers, they did not believe it was their responsibility to save the banking system. Their governing boards limited the types of collateral they were willing to accept from borrowing banks at the discount window. They did not actively encourage local banks to apply for funds. The exception was the sixth regional located in Atlanta. They faced the first regional banking crisis and successfully contained it.  

    This attitude of letting the economy and its banks to go to hell was shared by Andrew Mellon, Hoover’s Secretary of the Treasury, who believed a major recession was good for the health of the economy. (He was too busy adding to his fabulous art collection by secretly and illegally buying art from the Soviet Union, which needed hard currency to finance its spying operations. These paintings, taken from the Hermitage, are now in the National Gallery collection in Washington. The spies later stole America’s atomic bomb secrets.)

    By the spring of 1933, the American banking system was near total collapse. Over half the states had declared a “bank holiday,” closing all the banks in their states to see which ones could be saved. This meant that depositors could not withdraw their savings. The new Roosevelt Administration’s first act in March 1933 was to declare a national bank holiday. Roosevelt’s second act was to take the United States off the gold standard. 


    INTERNATIONAL ASPECTS
    In the 1920s, New York had become the center of the global financial system. This was a consequence of World War I and its aftermath. During the war, England and France partly financed their war effort with substantial borrowing from New York banks. England and France could not borrow from the American government because Wilson was afraid isolationists could help defeat him for reelection in 1916. During the 1920s, Germany borrowed large sums from New York banks to restart its economy and pay war reparations to England and France.Central bankers and large investment banks spent the 1920s trying to rebuild the global financial system shattered by World War I. They saw the pre-war gold standard as a control mechanism to overcome the economic dislocation and instability caused by the war. The key, as they saw it, was to fix the value of national currencies in gold and thus, to each other. By 1929, almost all currencies, including the dollar, were on the gold standard. (In a bit of bad timing, Japan went on the gold standard in January 1930.)The gold standard depended critically on the pound sterling and London before the war, and the dollar and New York after the war. The New York Fed chairman (Benjamin Strong) worked closely with the chairman of the Bank of England (Montagu Norman) and other central bankers to coordinate policy, primarily changes in interest rates to influence currency and gold flows. Central banks and investment banks, mostly American, would also loan money to foreign governments to ease pressure on their currency. But America’s commitment to reforming the global financial system was limited. There were three major problems:1) Entente (Allies) war debts and German reparations. The Entente countries, including England and France, had borrowed over $10 billion in America to help finance the war. After the war, the Allies imposed reparations on Germany, payable mostly to England and France. These two countries relied on payments from Germany to meet the interest and principal payments on their debt to the United States. But the German economy had a hard time recovering from the war and taxing its people to raise reparation funds. Instead, Germany depended on borrowing from private banks in New York. Some of the funds would then go to London and Paris, to be cycled back to New York. Towards the end of the 1920s, more of the loans were short-term (“hot money”) rather than the usual long-term credits. The system functioned as long as American bankers were willing to lend to Germany, that is, to roll over rather than call short-term loans. 

    2) England went back on the gold standard in 1925 at the pre-war parity. It overvalued the pound compared to other currencies. English exports were priced out of global markets; imports were relatively cheap. As a consequence, the English economy had a hard time recovering from the war, experiencing deflationary stagnation. England ran a trade surplus before the war but a trade deficit after the war. Defending sterling’s price in gold meant high interest rates to attract foreign funds, low economic growth, deflation (with pressure on wages), and high unemployment rates.

    The New York Fed often changed American interest rates to accommodate the Bank of England’s attempts to deal with England’s economic and financial problems.

    3) Central bankers would change interest rates to influence cross-country capital and gold movements. But changes in interest rates also affected domestic economies. Interest rates in New York were actually lowered at the beginning of the stock market boom to encourage money flows to England. But lowered rates also reduced the cost of call money and brokers’ loans to speculators, fueling the stock market bubble.Gold was also “high-powered” money, a part of the banking system’s reserves. An influx of gold allowed a country’s banking system to created money by creating new loans. Throughout the 1920s there was a net inflow of gold into the United States. American banks could increase the amount of loans to American consumers, stock market speculators, farmers, and corporations.

    Just when it seemed the global financial system was stabilizing, it started to unwind. Germany went into recession in 1928. The head of Germany’s central bank threatened to stop paying reparations. Money flowed out of Germany. American bankers stopped expanding short-term loans to Germany. The American government refused to reduce Allied war debts; England and France could not reduce debt payments to private American banks. By 1929, Germany had reduced paying war reparations and the crucial cycle of American loans to Germany, German reparation payments to England and France, and their war debt payments to American banks began to unravel. American banks were now sitting on billions of dollars of bad loans. A delegation of American bankers went to Europe to renegotiate the repayment timetable of German reparations.
    A slowdown in economic growth in the industrialized countries led to a large decrease in global commodity prices (inelastic demand). Countries that depended on commodity exports went into recession and were the first countries to leave the gold standard.

    The U.S. economy went into recession and the stock market crashed. One consequence was that American banks started calling in German loans, deepening the German recession. There was a large and sudden increase in German unemployment. This contributed to the rise of Hitler and the Nazi Party, which received only 2.6% of the vote in 1928 but over 35% in 1930. The Nazi Party was the largest right-wing party, making it almost inevitable that Hitler would become Chancellor as conservatives tried to form an effective government to counter rising left-wing support. In office in January 1933, Hitler quickly renounced all reparations payments.


    By 1931, the English government realized that England would not get out of long-term stagnation without eliminating the deflationary effects of the gold standard. England and 20 trading partners left the gold standard. The English pound sterling depreciated (went down in value) against the dollar, making America’s recovery more difficult.

    THE GOLD STANDARD AND DOMESTIC POLICY


    The Hoover Administration’s and the Fed’s commitment to the gold standard limited domestic policy options. Budget deficits, lower interest rates, or increasing the money supply through Fed lending to banks would have tempted foreign central banks and depositors to withdraw gold. This was one reason the Fed did not use gold as part of the monetary base to expand credit through its discount window. Another reason:  the Fed might lose gold and contracted credit would also happen if Americans used dollars to buy gold. This was legal until President Roosevelt took America off the gold standard in early 1933. 

    The worsening recession and the gold standard led to deflation. Deflation led to the higher real cost of debt to borrowers, and then defaults as incomes and asset prices fell. The banking system weakened. Banks failures rose dramatically in 1931 and 1932. Seeing the deep recession and the weak financial sector, foreigners began pulling gold out in 1932. The Fed raised interest rates to keep the gold in the U.S. The Hoover Administration raised taxes to reduce deficits and signal “fiscal responsibility.” Again, by early 1933, the entire U.S. banking system was approaching total collapse.

    THE SMOOT-HAWLEY ACT OF 1930

    At the beginning of the Great Depression, Congress passed the Smoot-Hawley tariff bill of 1930 to protect farmers. Of course, everyone in Congress added their favorite worthy group of constituents who wanted protection. Tariffs went up to 60%. 1,000 economists, a rather conservative bunch in 1930, warned of the negative consequences of the bill.

    The main target was Canada, America’s largest trading partner. The more anti-American party won the next Canadian election. 

    Anti-American boycotts of American products started in Europe. American exports to Europe and Japan fell.

    England walled off its Dominion countries and colonies from American imports; France and Holland did the same with their colonies. Since imports and exports were a small percent of the American economy, about 5% in total, the Smoot-Hawley tariff bill was probably not a major cause of the Great Depression. Both imports and exports fell by about $1 billion, so the Act had little net macroeconomic effect. But, on the margin, it probably contributed somewhat to the length and depth of the Great Depression. 

    Tariffs and other barriers to trade reenforced America’s isolationism. To keep America out of the looming European war (on England’s and France’s side), a strong America First movement arose. Some of its members, including Charles Lindbergh and a future president of Yale, were pro-Hitler. The organization effectively disbanded in December, 1941.

    A LONGER VIEW OF THE STOCK MARKET CRASH OF 1929

    By the end of 1929, the Dow Jones Index was back to the beginning of 1928. It was only 17% lower than the beginning of 1929 – a year of above-average gains followed by larger losses. So any investor who bought stock for cash at the beginning of 1928 or earlier, was about even. Anyone bought stock at the beginning of 1929 was even by the end of the first quarter of 1930, before the market turned down again. Only speculators who bought stock on margin were wiped out. This included many large speculators. Of course, anyone who held their stock until the end of 1932 lost almost of the value anyway. And anyone who bought on “dips” between 1929 and 1932 lost money.

    It is likely that many families who still had stock after 1929 were later forced to sell because of some combination of unemployment, lose of savings in a collapsed bank, and to meet installments on borrowings for consumption and maybe a mortgage on their home.

    Anyone who bought at the top in September 1929 and held onto their shares had to wait until 1954 to break even.

    Since 2000, there has been three market contractions of similar magnitude to October 1929. The last two could have led to a prolong depression. But they didn’t. The difference is that the federal government stepped in with massive fiscal stimulus and support for failing companies.

    SUMMARYIt is a mistake to see the stock market as separate from the rest of the economy. It was part of the financial sector, which greatly expanded in the 1920s and became a more important part of the economy. The financial sector helped finance the economic growth and new products of the 1920s, especially demand for the new consumer durables. Gains from the stock market helped to finance the flamboyant life-style of a small percentage of consumers, symbolized when wealthy Americans on luxury trans-Atlantic steamers could radio their brokers in New York with stock orders. The boom in buying consumer durables and housing was made possible by the expansion of consumer loans and home mortgages. Increases in consumption and consumer loans were tied together. In contrast, small local banks were tied to the stagnant, leveraged agricultural sector. Although the bottom of the Great Depression came over three years after the start, over half the fall in output and real income occurred in the first year, by the end of 1930. This was a large and rapid decline. The stock market crash was a catalyst; it accelerated the decline in income, wealth and the demand for goods and services through feedback effects between the financial sector and the real economy.The stock market crash of 1929 was not the only reason for the depression. Many of the systemic risks were due to global and domestic problems caused by the First World War and its aftermath. There were continuous feedback effects between the real sector and the financial sector. What changed was the size and importance of the American financial sector – as an international lender, as a raiser of capital, as a provider of household credit, as a seller of financial instruments. 

    The continuous feedback effects also help explain why the depression lasted so long and was so deep. Waves of bank failures, loss of savings and assets, lack of the Fed’s responsibility as “lender of last resort” all contributed to lengthening the depression and making the recovery difficult

    Many of the government recovery programs of the Hoover Administration and the early Roosevelt Administration were substitutes for a financial sector that had ceased to function.  

    The American economy in the 1920s became not only larger but also more complex. There were more “fault lines.” Recent studies of “complex adaptive systems” indicate they can go from seemingly stable to unstable very quickly. New potential fault lines were added in the 1920s – stock market speculation,  agricultural stagnation and debt, consumer durables bought with loans, and America’s involvement in international finance. 

    The structure (including rules and lack of rules) of the financial sector when the crisis hit was important. The banking structure and much of the rest of the financial markets had not adjusted to the economic changes of the 1920s. Fragmented domestic banking, the gold standard, lack of information and analysis, absence of oversight, and widespread manipulation and fraud all contributed to a financial sector that was ill-prepared to handle the stresses beginning in 1929. Changing the rules – increasing the confidence of depositors, borrowers and investors – was an important part of the New Deal.
    The depression was made worse by the antiquated mentalities of those in power. They were faced with the instabilities and dislocations of an international financial system radically changed by World War I. Their response was to revert back to the rigidity and deflationary pressure of the gold standard. American officials and the three Republican presidents in the 1920srefused to decrease Allied war debt, a necessary condition to stabilize the international financial system. In America, an increasingly industrialized, mass consumption economy fueled by financial capital and consumer debt depended on a fragmented banking system of small, local banks designed for a decentralized agrarian economy. Fed and government officials strongly believed in market competition and laissez-faire, which was ill-suited to an economy dominated by large, mass production corporations and a greatly expanded financial sector.

    CONCLUSION

    The real economy was growing rapidly, probably around 6% in 1929. This growth rate was unsustainable. Part of it was because of pent-up demand for autos; many consumers had waited for Ford to get back to full production. There was a big increase in the purchase of autos and other consumer durables during this period. A high percent of consumer durables were bought on credit.Rising domestic optimism was behind the big increases in both output and the stock market. Employment levels were high. This optimism is hard to quantify but it was pervasive outside of some rural districts. (See video)Recessions start with an unexpected shock. They are often outside of economic models used at the time of the shock. In 1929, the stock market decline was mostly independent of the real economy recession. In 1930, stock market recovered 40% in first quarter, indicating investors believed the decline was a “correction” and stock prices were cheap. But the real economy continued its rapid deterioration. When recognized, investors realized their optimism was misplaced and the stock market turned down again. The recession of 1930 does not show up in financial figures except for the stock market and more than the usual number of small banks failing. As the buying of consumer durables and other mass-produced consumer products declined, profits fell. Investment in manufacturing declined, as the reason for increasing capacity disappeared. The government did not make up any of the loss of income in 1930 through welfare programs or fiscal deficits. (Even during the 1930s, Roosevelt’s budget deficits were much smaller than the decline in private incomes and corporate investment. A misguided policy to balance the budget in 1937 led to a severe recession that wiped much of the output and employment gains of the prior four years.)The structure of the economy had fundamentally changed since the last depression that occurred in the 1890s. New economic and financial fault lines appeared in both rural and industrial America. The situation was made more dangerous as the global economy struggled to recover from World War I and its chaotic aftermath. Only the New York Fed and large New York banks worried about international instability and its possible consequences. Eventualy, all Americans would become aware of the consequences of post-WWI overseas problems, the stock market crash of 1929, and the beginning of the Great Depression in 1930. On December 7, 1941.


    ======================================================
    The best introduction to the 1920s and the stock market crash is Frederick Lewis Allen, Only Yesterday; An Informal History of the 1920’s. This is a wonderful popular history of the 1920s and the crash. It shows how the economic, social, and psychological changes in the 1920s contributed to the speculative frenzy in the stock market. Allen lived through it all. You can skip some of the chapters the first time through; for example, skip Chapters III, VI, IX, And X.If all of this seems complicated and confusing (it is), you might want to see a summary:

    Introduction to the Stock Market Crash of 1929 and the Start of the Great Depression

    For a look at the similarities and differences between the stock market falls in 1929 and 2020 (written in 2021), see

    The Stock Market:  Party Like It’s 1929! For a (hopefully humorous) explanation of the 2007-08 financial crisis, seeExplaining Derivatives – An Analogy
    AMERICAN ECONOMIC HISTORY
    The Beginning of the Industrial Revolution in America
    How America Industrialized and Became Wealth
    Alice in Wonderland and the Origins of Silicon Valley
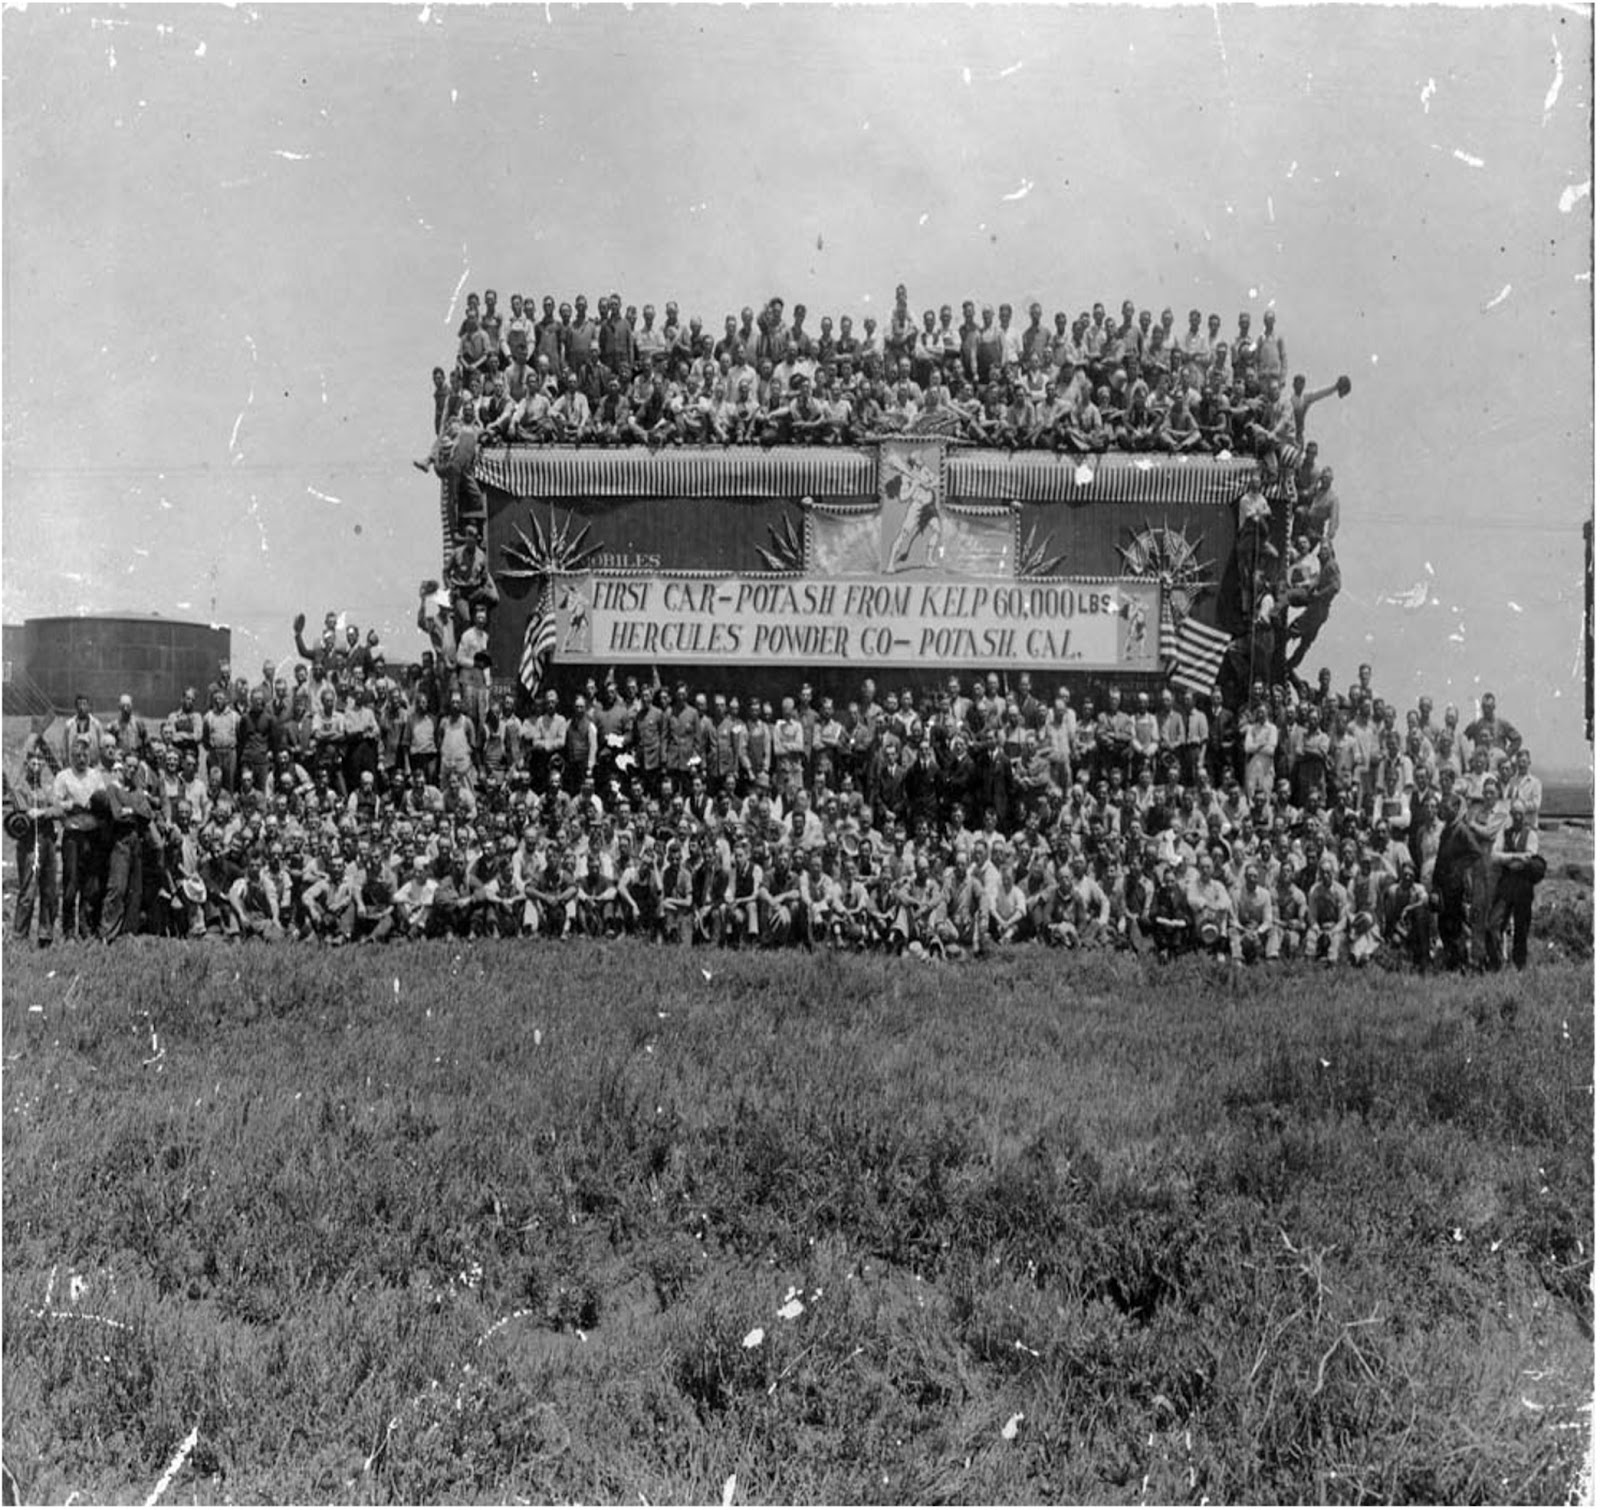
  • KELP IS ON THE WAY:  How American Kelp Helped Save the English Explosives Industry in World War I

    KELP IS ON THE WAY: How American Kelp Helped Save the English Explosives Industry in World War I


    Dr. Andrea Dragon


    Seaweed Saves England


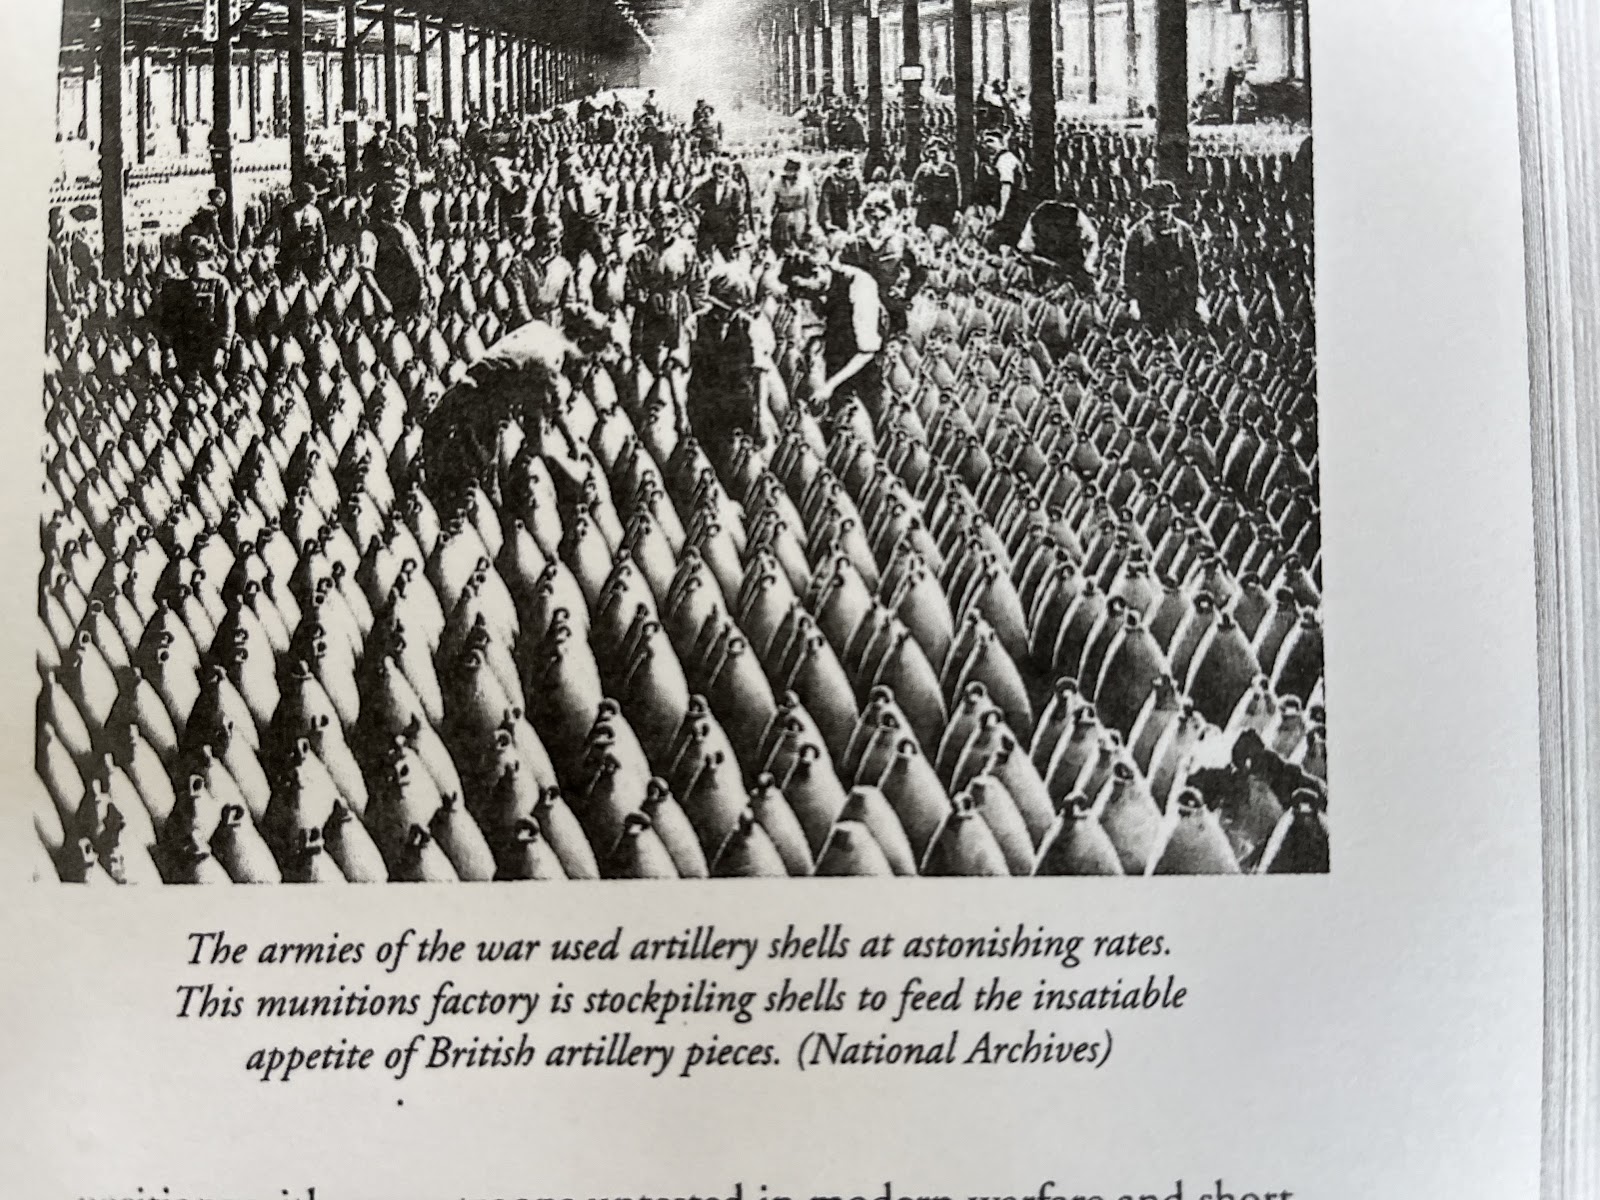
        Each of the hundreds of millions of shells Great Britain fired from thousands of field guns, howitzers and mortars during World War I contained two explosives: cordite, a kind of nitrocellulose (what Americans call smokeless powder) to propel the shell out of the artillery piece and send it flying toward the target, and TNT, the shell’s high explosive payload to blow up the target on impact.  

    In the early months of the war, the demand for cordite far exceeded the manufacturing capacity of Great Britain’s explosives factories.  To meet production demands, in October, 1914, the British Army contacted representatives from DuPont and its 1912 spinoff Hercules, who were the leaders of New Jersey’s established explosives industry, and signed agreements with them to produce nitrocellulose and cordite, load it and TNT into shells, and ship them from New Jersey ports to the Western Front.

           But cordite was different from the nitrocellulose-based smokeless powder products New Jersey explosives pioneers had been manufacturing in “powder towns” since the late 19th century. Unlike American smokeless powder, cordite included nitroglycerin transforming it into a “double-base” explosive.  Although New Jersey’s powder industry had decades of experience with nitroglycerin (at that time, anything, even a liquid, that exploded was a “powder”), no one had ever added it to smokeless powder because nitroglycerin damaged gun barrels.  That’s why the British cordite formula (30% nitroglycerin, 65% nitrocellulose, 0.8% acetone) also included 5% vaseline to coat and shield gun barrels from this kind of damage.

           At first, executives of the New Jersey explosives industry believed nothing much stood in the way of them making tons of cordite and tons of money. Not only was manufacturing nitroglycerin in sufficient quantities fairly easily done, vaseline could be sourced from the large Cheeseborough-Ponds factory in Perth Amboy. America’s vast railroad network could transport the cotton needed to make nitrocellulose from southern states to New Jersey’s powder towns.  Everything seemed to be in place to start building factories for cordite production, but there was still one very big problem the explosives industry had to solve – where to obtain acetone.

           Most readers are familiar with the organic chemical acetone because it’s useful to have around the house not only as a nail polish (which is mostly nitrocellulose) remover but also because there’s nothing better for removing paint or sticky gunk children have spread around.  Bought at the local home improvement center, acetone efficiently cleans off lacquer and oily finishes from metal surfaces before repainting.  Today, it’s one of the many products produced by the petroleum industry and is inexpensive and ubiquitous, but during WWI acetone was scarce because Germany had been the world’s leading supplier.

           It wasn’t as if Great Britain’s early 20th century chemists didn’t know how to make acetone, which was a by-product of burning wood to make charcoal.  The basic principles of acetone production had been known since the Middle Ages, weren’t covered by patents, and didn’t require sophisticated technical equipment. 

    Output estimates vary, but roughly speaking it took a hundred tons of wood to yield just one ton of acetone.  When the war began in 1914, most of Great Britain’s forest reserve was long gone, but Germany’s vast Black Forest had ample trees for making acetone and dominating the market.

           Since 1862, when Louis Pasteur discovered that alcohol was a product of fermentation by clostridium bacteria, chemists had been experimenting with fermentation to learn how the process produced various alcohol-like substances.  One of these chemists, Chaim Weizmann, a Russian immigrant scientist and one of the founders of the modern state of Israel, was researching methods of producing synthetic rubber at the University of Manchester when he discovered that acetone, butanol and ethanol could be created by fermenting starchy grains or potatoes using a type of clostridium bacterium (other, more sinister clostridia bacteria cause botulism and C. difficile) commonly found in soil.  Weizmann patented it two years later.  This breakthrough meant that instead of clear-cutting and burning up Great Britain’s meager remaining forests, acetone could be produced much more efficiently by fermenting an (easily) renewable crop like corn.

           Soon tons of American-grown corn were being shipped to Great Britain to be fermented into acetone, but this process became problematic for three reasons.  First, German U-boat activity made trans-Atlantic shipping  risky.  Second, corn took up precious space in ships that could be used for more high-value cargo.  Third, corn was a food crop and during the war many people in Great Britain were hungry, making it hard for the government to justify turning food into an industrial chemical.  England was importing 30% of its food consumption from U.S. and Canada.  Clearly, other sources of fermentable starch had to be found.  For a while, British children were encouraged to gather horse chestnuts, but fermenting them was unsuccessful and the search for ways to make acetone continued.  

    In 1916, the situation had become so desperate that Prime Minister Lloyd George proposed taking over all distilleries in the United Kingdom and transforming them into acetone factories.

             American explosives manufacturers weren’t sure how they would solve the acetone problem.  Nevertheless, in February of 1915 Hercules Powder Company signed a contract to produce millions of pounds of cordite at its New Jersey nitrocellulose “powder works.”  The contract stipulated that Hercules would have to find an acetone supplier who wasn’t part of any current supply chain to prevent Hercules from either reducing the existing supply of acetone, or from cornering the market.  Not only that, to get the cordite contract, Hercules promised to keep track of all the acetone it used and supply Great Britain with an equal amount. 

           Why was acetone required to make cordite?  Why was a solvent needed to make any kind of smokeless powder?  At its most basic level, nitrocellulose is simply cotton that has been soaked in nitric acid and then dried until it forms a stiff, white mass.  Because ignited nitrocellulose burns first on its surface, forcing a solid mass of nitrocellulose through a large extruding machine not unlike a modern pasta-maker increases its external surface by transforming the single mass into many spaghetti-like strands, or cords.  But before that could happen, the stiff lump of nitrocellulose had to be mixed with a solvent to change it into a gelatinous dough pliable enough to go into the hopper of the extruding machine, be forced through the holes, and come out the other end as strands of cordite.

           Hercules and other American smokeless powder manufacturers used ether-alcohol as a solvent, but the British specified acetone because cordite made with it required less of the gun barrel-corroding nitroglycerin than powder made with ether-alcohol.  At first, Hercules management tried to make acetone from acetic acid bought from manufacturers of table vinegar but weren’t successful.  Then the company tried arranging with industrial distillers of wood alcohol to produce acetone, but the process was developing too slowly and didn’t produce the quantities needed to fulfill the cordite contract.  Not only was Hercules falling behind the cordite production schedule to the tune of a million pounds a month, it was also woefully short on its promised deliveries of acetone to Great Britain.

             Hercules’s management investigated making acetone from beer slop, molasses, and wood pulp without much success.  The company’s situation was bleak when George Markell, vice-president and general manager of the company’s New Jersey operations, read in an old encyclopedia that Scots living near the coast once gathered kelp from the ocean, dried and burned it in retort-like ovens recovering potash which they used as a fertilizer.  After he learned that acetic acid could be produced by fermenting kelp, Markell developed a plan to harvest kelp from the Pacific Ocean off the coast of Southern California, put it in vats, allow it ferment like beer, capture the acetic acid given off in the fermentation process, and make acetone from the acetic acid.

           Markell knew a huge bed of kelp existed a short distance from San Diego and best of all, it was essentially free.  Markell went to California in 1915 and began buying up land near Chula Vista, then contracted with a Midwest farm equipment manufacturer to design and build a large hay-mower capable of operating in sea water.  Hercules wasn’t the only explosives company seeking to cash in on the skyrocketing demand for acetone so Markell concocted a cover story claiming his company was going to “farm” kelp to make potash fertilizer.  Soon 1,500 Hercules employees were using the special mowers to harvest tons of kelp, load it onto barges which transferred it to shore where some of it was used to make potash while the rest was put into two-hundred 50,000-gallon wooden tanks and allowed to ferment producing acetic acid that was further processed yielding not only acetone, but other useful ketones such as methyl-ethyl ketone, a lacquer thinner, as well as potassium nitrate (saltpeter) one of the ingredients of black gunpowder. By the middle of 1917, nearly one million pounds of acetone, produced from 600,000 tons of kelp, had been loaded into railroad tank cars and shipped to New Jersey where 5,000 tough, brave powder men and women working in hazardous conditions made cordite for Great Britain at a rate of 100,000 pounds per day.

           After the war, Hercules closed its Chula Vista operation in 1919 and today the site is a nature center.

           Recently, I ran across a 2022 scholarly article describing new efforts to produce acetone from kelp harvested off the coast of Scotland.  This article ran to forty-two pages, had eleven authors, and contained eighty-five footnotes but not a single word about the Americans who fermented kelp, produced acetone, and made the cordite that helped Great Britain achieve victory in World War I.


    Dr. Dragon teaches a course at Rutgers University, New Brunswick, New Jersey on the New Jersey explosives industry.


    Related essays by Dr. Dragon:


    The Maxim Machine Gun and Smokeless Powder


    New Jersey Artillery Explosives Production in World War I


  • New Jersey Artillery Explosives Production in World War I

    New Jersey Artillery Explosives Production in World War I


    Written by Andrea Dragon, Ph.D. Dr. Dragon investigates and writes about New Jersey’s industrial history. Professor Dragon will be teaching a continuing education course on “New Jersey’s Explosives History” at Rutgers – New Brunswick on October 8, 2025. See details at the end of this essay. 


    1914:  World War I Breaks Out


    Russia started to modernize its army in 1913, with substantial French financial and weapons support. The beginning of a five-year plan, one of the main goals was to expand artillery to catch up with Germany. But war broke out. 


    After the first four months of the war, all combatants realized they were in for a long war with deadly modern weapons. Every country’s strategy of a quick victory through offensive warfare failed. Germany did not defeat France and England in the west, and the Russian offensive against Germany in the east ended in disaster. The result was four years of trench warfare in the west and three years of large-scale but inconclusive warfare in the east. Russia stayed in the war only because of imports of weapons, especially through large orders in the U.S.


    Russia, like all combatants in World War I, was not prepared for a long war. Russia’s stockpile of shells was inadequate for the high rates of fire. The Russian army used up most of its inventory of shells in the first four months of the war. Russia did not have the production capacity to resupply shells for its large army.


    Financing Russia’s Need for Artillery Shells and Explosives: First England and then J. P. Morgan and American Loans


          Russia needed foreign loans because it couldn’t produce the quantity of war materiel needed to engage in modern warfare. When the war began in the late summer of 1914, Russia had a large standing army of over one million soldiers and through conscription and reserves Czar Nicholas II had the ability to draft and call up millions more for the army. What Czar Nicholas didn’t have was the industrial capability to manufacture artillery, artillery shells and ammunitions in the quantities necessary to turn his large army into a modern fighting force. 


          The Czar’s cousin, King George V of England, and his parliament, were willing to spend whatever it took to keep the Czar’s army fighting on Germany’s eastern borders because every German soldier sent east to fight the Russians meant one less soldier to fight British soldiers in the trenches of France and Belgium.


          In the early months of the war, Britain loaned Russia money to buy armaments on the world market, but Britain attached conditions to the loans (buying in England?). Although the munitions themselves would be made to Russian specifications, the contracting for their manufacture would be handled by the British.


          Russia chafed under these conditions and wanted a free hand to choose the manufacturers, delivery times, and most important of all, how and when the contracts would be paid.  Russia tried to go around Britain and seek loans directly from bankers in the neutral United States believing those conditions would be less onerous than the British ones.  


    Obtaining U.S. Financing


    J.P. Morgan was an investment bank. It did not have the financial assets of a large commercial bank. Morgan syndicated loans through wealthy corporate and individual clients and other banks. It made its money from commissions.


          A compromise of sorts was reached in the fall of 1914 when Chancellor of the Exchequer and later Minister of Munitions David Lloyd George asked J. P. Morgan, Jr. who was heading up his father’s banking house, to loan Russia $12,000,000 (about $300 million in today’s dollars) to buy weapons and ordnance. A few months later, Morgan responded to additional requests by beginning a long process of bundling a staggering $500,000,000 worth of loans from his bank and from other American banks.


    Only a few people in the United States outside of the government knew that seventy-five percent of the Morgan-brokered money was designated to be funneled through obscure channels to Russia to buy munitions from American ordnance companies. Although these direct loans from privately owned banks to governments at war with Germany were not illegal because they did not violate America’s official policy of neutrality, they were the subject of fierce debate among members of President Wilson’s cabinet.  The new loans granted Russian officials the ability to act without British oversight enabling them to add layers of regulations to manufacturing contracts by inserting a boggling array of parties, terms, penalties and conditions. The U.S. government refused to make or guarantee loans because of Wilson’s policy of neutrality. America was still strongly isolationist, so any government loans would probably be politically unpopular. And Wilson was facing reelection in 1916.


          On September 22, 1915, representatives of the Russian and British government, with J.P. Morgan, Jr. acting as purchasing agent, signed a contract with New Jersey’s Union Powder Company for the manufacture of several million rounds of both high explosive and shrapnel shells for the Russian version of the French 75mm (76.2mm due to Russia’s unique system of measurement) field artillery gun. These were the first Allied shells made in America.


    New Jersey Artillery Explosives Production and Shipping for Russia


    Russia contracted with American companies, mostly in New Jersey, to produce shells and explosives as early as 1915. 


         ”Soon to be erected on the north side of the Raritan River between the towns of Fords and Metuchen will be the world’s largest munitions factory.”

          Daily Home News, New Brunswick, New Jersey, July 17, 1915.     


          The newspaper didn’t name the Raritan River factory, but it was the Nixon Nitration Works and its sole customer was the Russian Imperial Army.  It was owned by New Jersey explosives pioneer Lewis Nixon.


    Lewis Nixon was the top graduate of his 1882 U.S. Naval Academy class.  After graduating, he pursued graduate work in naval architecture at the Royal Naval College in England where the future King George V was his classmate.  After finishing his studies in England, Nixon moved to Russia where he spent a few years building torpedo boats for the Czar’s navy before returning to the U.S. and managing shipyards in Philadelphia and Elizabeth, New Jersey. In 1897, he supervised the building of the U.S. Navy’s first commissioned submarine.  


          Despite his success in ship building, Nixon lost interest in naval architecture and decided to switch to manufacturing the explosive propellant nitrocellulose, commonly known as smokeless powder.  Even though he knew the basics of smokeless powder manufacture (soaking cotton in nitric and sulfuric acid with the aid of a solvent) Nixon couldn’t just start manufacturing because unlike gunpowder, smokeless powder was proprietary and he risked being sued for patent infringement if he proceeded without a obtaining a license from a patent holder.  He contacted a Naval Academy classmate, John Baptiste Bernadou, who was conducting research on smokeless powder at the Naval Torpedo Station in Newport, Rhode Island.  Like Nixon, Bernadou had traveled to Russia and spoke the language which came in handy because he was also the naval station’s official translator of international research articles including those written by the Russian chemist Mendeleev, the same Mendeleev who devised the periodic table.  In 1897, Bernadou and a colleague, George Converse, received an American patent for smokeless powder that was very similar to the one Mendeleev had patented years earlier. (For the story of the development of smokeless powder, see my post The Maxim’s Machine Gun and Smokeless Powder.)


          After buying a license from Bernadou, Nixon began manufacturing smokeless powder in the Raritan River town of Sayerville.  Unsurprisingly, right away Nixon received orders from the U.S. Navy and from several European armies and by 1902 his factory was producing 6,000 pounds of power a day.


           In 1904 Nixon sold his business to the explosives giant DuPont and returned to naval architecture. But the advent of war revived his interest in smokeless power and utilizing his knowledge of Russian, and his royal contacts in Britain, he obtained a contract to supply Russia with 1,000,000 pounds of smokeless powder in 1915. In his new company (the world’s largest munitions factory referred to in the above quote) which was spread out over twelve square miles along the Raritan River, hundreds of powder men and women and their Russian supervisors produced 75,000 pounds of smokeless powder a day, producing over 200,000,000 pounds by the end of the war.


          Nixon wasn’t the only New Jersey powder man who made explosives for the Russians in WWI, but he was among the largest.  One thing all manufacturers had in common was all received payment for the powder and shells they produced from the money Russia had borrowed via a bewilderingly complex system of loans.


    Union Powder company was owned by another New Jersey explosives pioneer, T.A. Gillespie, who had no experience making munitions but as owner of an important New York civil engineering firm he had experience getting government contracts.   His company was one of several New Jersey shell-loading subcontractors doing business with the lead contractor, Canadian Car and Foundry, a Montreal-based manufacturer of heavy railroad equipment.  In October, 1914, just few weeks after the war began, Canadian Car had received a contract from the British government to manufacture 5,000,000 shells for Russia even though the company had no experience making munitions.  Early in 1915, Canadian Car purchased fifty acres of New Jersey swamp land near the town of Lyndhurst and began building what was billed as the world’s largest shell-loading facility, “Kingsland,” where hundreds of employees working under Russian supervision would load smokeless powder propellant that had been made by Nixon and other powder men plus shrapnel and high explosives into shell bodies shipped to Kingsland via railroad.


          Only about half of the shells specified in the contract had been delivered in January of 1917 when a devastating explosion nearly destroyed the facility, but Canadian Car partially rebuilt and loading operations limped along at a reduced pace until August of that year when the political situation in Russia began to change following Lenin’s return from exile.   Because the Russian Imperial Army was Kingsland’s only customer, the facility’s future depended on whether the new government in Petrograd was going to continue to fight on, or get out of the war altogether.  Sensing which way the wind was blowing, Canadian Car closed down their Russian shell-loading operation in Kingsland a few weeks later.


    The three largest shell-loading plants in the United States were in New Jersey.


    The United States Enters the War


          Russia left the war late in late 1917 because of the Russian Revolution. The new Bolshevik (Communist) government defaulted on Imperial Russia’s obligations to pay for the munitions it had received from American suppliers and subcontractors. Fortunately for New Jersey explosives manufacturers, the United States entered the war in April, 1917.


    After the U.S. declared war, the New Jersey explosives industry shifted into a much higher gear. For example, an all-female crew working at DuPont’s explosives plant in Carney Point, New Jersey, produced 1,000,000 pounds of powder a day


    The United States army had little artillery. The French “rented” artillery to the U.S. Army who paid the rent in picric acid (TNP) filled shells. The French supplied the hardware and the U.S. supplied the manpower and the explosive shells. This was General Pershing’s deal. New Jersey workers made the picric acid, loaded it into shells, then shipped the shells to Europe via South Amboy and Jersey City.


    For security reasons, shell production figures were never published and exact numbers remain elusive. A reasonable guess is that between four and five million high-explosive shells were manufactured at all the shell-loading plants in the U.S. between April 1917 and November 1918.


    In the summer of 1918, the U.S. government contracted with Gillespie to build a giant shell-loading facility, one of the largest in the world. 


          How many of that number Gillespie’s Morgan plant produced may never be known because on October 4, 1918, the Gillespie plant was destroyed by an explosion that killed over 100 workers, many of them women and teenage girls.  The explosion destroyed twelve million pounds of high explosives. 


          No evidence of sabotage was ever found.


    Conclusions


    This is a good example of two key aspects of World War I.


    First, the United States as the world’s largest and most diverse industrial power could provide Russia and later France with war materiel they could not produce themselves in sufficient quantity.


    Second, England, France and Russia had resources beyond what they could domestically produce or provide. In this example, access to artillery shells from Canada and the United States. In addition, England and France could call upon substantial numbers of troops from colonies and Dominion countries (Canada, Australia, New Zealand and South Africa).


    NeJersey’s Explosive History 


    WednesdaysOct. – Nov. (weeks10:30 a.m. – 11:30 a.m.

    Locationinperson in New Brunswick Member$40 NonMember$60 

    The explosives industry in New Jersey began in the late 19th century when handful of entrepreneurs built an industry and powder town” near the Raritan River with the help of few eccentrics including crook or twoand former New Jersey resident sharpshooter Annie OakleyDecades later during WWIthe New Jersey explosive industry had expanded to other sites in the state and had grown so large it was able to supply half of the explosives used by all the AlliesAlthough their story is largely forgottenthousands of brave New Jersey menwomen and teenage girls made millions of tons of explosives and loaded them into shells destined for the battlefields of Europe and over hundred of them lost their lives in terrible explosions(course code NBV38

    InstructorAndrea Dragon


    ========================================================


    For related posts by Dr. Dragon, see


    The Maxim’s Machine Gun and Smokeless Powder


    KELP IS ON THE WAY:  How American Kelp Helped Save the English Explosives Industry in World War I


  • Examples of Bilateral Oligopolies

    Examples of Bilateral Oligopolies

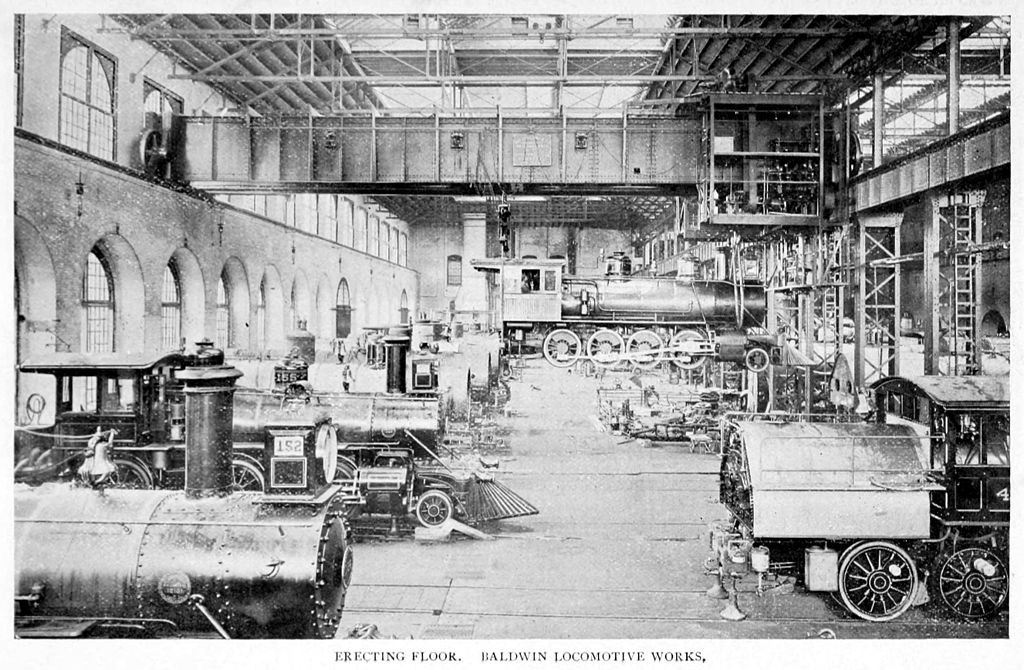
    Baldwin Locomotive Works:  Erecting Floor

    BALDWIN LOCOMOTIVE WORKS:  A HISTORICAL EXAMPLE OF BILATERAL OLIGOPOLY

    Baldwin, the largest producer of steam locomotives in the nineteenth and early twentieth centuries, faced problems typical of a dominant company in a bilateral oligopolistic industry. A highly cyclical, almost unpredictable competitive environment conditioned almost everything that happened at Baldwin. A high level of business risk followed from sudden, large fluctuations in demand from railroad companies. This meant that Baldwin often had excess capacity with substantial fixed investment. There were few opportunities for economies of scale. 

    Baldwin also depended on a skilled labor force with firm-specific knowledge and experience that was exposed to sudden and massive layoffs followed by the company’s attempts to rehire the same workers.  It is hard to imagine a more challenging competitive environment.  

    Baldwin was a large and dominant firm, accounting for approximately one-third of all steam locomotive production.  The buy side of the market was dominated by a small and increasingly concentrated number of railroad companies, five by the early 20th century, which were some of the largest corporations in America in the nineteenth century.  The sources of market power of the locomotive builders were their specialization and flexibility in production, although some of the larger railroads – Baldwin’s largest customers – also built locomotives in their own machine shops.  The sources of market power of the railroads were their large purchasing power, technical knowledge of their “master mechanics” who ordered equipment, and knowledge of the optimal mix of equipment for their particular company.  In such an environment, Baldwin had market power because of its size and assembly expertise, but never enjoyed the market control of a mass producer of standardized products.  Market power based on marketing to final consumers was not feasible; railroad customers did not demand that railroads use Baldwin engines.

    Every large railroad developed its own specifications and demanded customized equipment from Baldwin.  In addition, there was continuous technological improvement of the basic steam locomotive, often innovated by railroad technical staffs.  As a consequence, Baldwin could never control the pace of design change.  The company could not totally incorporate mass production techniques because of constantly changing customized design and finish.  On the other hand, by working closely with its customers over a long period of time, Baldwin probably had lower transaction costs than if its sales were arms-length market transactions.

    This mutual dependence, along with railroads’ credible threat of internal production and the importance to Baldwin of every sale, usually gave the railroads a bargaining advantage when negotiating design customization and price with Baldwin.  But working closely with its largest customers, particularly the Pennsylvania Railroad, also increased the probability of Baldwin’s long-run survival. 

    This symbiotic relationship between steam locomotive builders and the railroads worked as long there was no fundamental innovation in engine design and both sides benefited from continuous improvement in the steam locomotive. But the market radically changed with the introduction of the diesel-electric locomotive. Baldwin and other steam locomotive companies could not compete with the new technology and went bankrupt.  

    The bilateral relationship would be much different in the later market for diesel engines in which General Motors controlled the technology and forced railroads to buy standardized products.

    Baldwin’s management objectives were to minimize risk and maximize operating flexibility by sharing risk with suppliers through subcontracting out much of its parts production.  Since production was to order, Baldwin managed a “just-in-time” parts inventory system that minimized working capital requirements. When times were bad, Baldwin could delay payment to its suppliers and thus use them as a major source of working capital.  This was one way the company dealt with severe cash flow problems in economic downturns.

    The company countered the potential loss of skilled workers after massive layoffs with high wages, skill development through apprenticeship training for employees and sons of employees, and the hope of higher income for long-term employees through a system of internal promotion and inside contracting.  Inside contracting, usually managed by long-term employees, put pressure on contractors to keep labor costs down.  This led to cooperative, less confrontational labor relations policies than those of other large-scale employers like Carnegie Steel.

    Because of the complex nature of its production, Baldwin needed sophisticated internal systems to keep track of parts, subassemblies, and final production schedules.  The company substituted detailed cost and internal job flow information for management control bureaucracies. While Baldwin did little internal product development, it was very quick in applying advances in product design and production technology. 

    When diesel locomotives became less expensive to operate and maintain than steam locomotives, Baldwin tried to adjust but its technology and skill base was too specialized to adopt the new technology.  Baldwin did innovate, designing and producing more powerful and efficient steam engines.  But to no avail.  Baldwin was doomed, another victim of “creative destruction.”

    COMPANIES SIMILAR TO BALDWIN

    Many transportation companies – companies that produce airplanes, ships, or railroad equipment – are similar to Baldwin. The American companies most similar to Baldwin are capital goods and information technology companies that sell large, complicated systems to other large corporations. Corporations that offer oil field equipment and services to large oil drilling companies fit this category.

    Boeing and Airbus are in a similar position as Baldwin. As are the three remaining corporations that produce jet engines.

    Strategies adopted by organizations such as financial software companies that build large, complex systems for large corporate customers, such as SAP or Oracle, are similar to Baldwin’s. These companies start with offering complicated systems and then work with their corporate customers to customize them to meet a company’s particular requirements.

    A special case is the market for the most advanced chips. ASML dominates the market for the machinery that produces the chips. Taiwan Semiconductor (TSMC) dominates the market for the actual production of the chips. Nvidia dominates the market for advanced GPU chips. Competition is often a matter of new technology leading from one dominant company to another – from IBM to Intel to Nvidia. On the other side of the market are the data center companies – Microsoft, Amazon and Google.

    A suggestive line of inquiry might be the similarities between Baldwin’s strategies and those of Japanese companies in keiretsu supply chains to minimize risk, coordinate strategy with subcontractors, and maximize innovation in highly uncertain and changing environments.  Large Japanese companies followed similar strategies in the early phases of their industry growth. A big difference was that zaibatsu risk before WWII was underwritten and reduced by the actions of the Japanese government and related financial institutions.


    The New York Times Discovers Bilateral Oligopoly


    On Sunday, November 1, 2015, The New York Times ran an editorial titled “How Mergers Damage the Economy.”


    The article begins by citing an article in the Wall Street Journal summarizing a study done by two finance profs that estimate “nearly a third of American industries were highly concentrated in 2013, up from a quarter of all industries in 1996.” Much of the editorial mentions a few of the recent proposed large mergers and goes on to list the possible evils from large companies merging.


    But why do large companies merge?  One reason the article gives, without naming the concept, is bilateral oligopoly. To quote:


         Mergers tend to lead to more mergers. In the health care industry, big insurers like Anthem and Aetna say they need to get bigger to have more leverage in negotiations with hospitals and doctor’s practices that have become bigger through acquisitions in recent years.


    Anthem attempted to acquire Cigna ($48 billion) and Aetna attempted to acquire Humana ($38 billion).  There would have been only three large health insurance companies (UnitedHealth is the third). Both mergers were blocked by the Justice Department and the courts. Instead, insurance companies are buying or signing exclusive contracts with pharmacy benefits managers, hospital chains, clinics, and other health care providers. 
    Even without mergers, the five largest health insurers cover over 130 million people, about half of Americans with health insurance. Since then, Aetna was acquired by CVS Pharmacies.
    Pharmacies make the same argument.  Walgreen’s, the country’s largest pharmacy, wanted to buy Rite Aid, the country’s third largest pharmacy.  This is an industry that has seen massive consolidation over the last few decades.  Walgreen’s argument to the government is the same as the health insurers.  They have to get bigger to be in a stronger position when negotiating drug prices with the huge drug companies and pharmacy benefits managers. CVS, the second largest pharmacy chain, took it a step further. They acquired Aetna. CVS combines a dominant pharmacy chain, a health insurer, clinics, and a pharmacy benefits manager.


    Every sector of the health care industry makes the same argument. Hospitals are merging into regional health systems which dominate local and regional markets. Physicians are also joining local and regional groups.  As any one part of the health care supply chain consolidates, partly through mergers and acquisitions, their suppliers and corporate customers feel pressures to also consolidate. In game theory, this is called an “arms race.”
    Health care providers are consolidating because over half of all health care costs are paid by various government programs. Prices are set by negotiations with the government, not by supply and demand. With third-party payment, ultimate consumers can demand high levels of health care with no or low out-of-pocket costs.    


    Corporate managers may not believe in the economists’ quaint ideas about competition but they understand the advantages of market power, the power to influence prices.  They believe they have to gain market share not necessarily to be more competitive in their own industry but when dealing with their suppliers and customers in increasingly concentrated industries.  If not, they believe they will be forced during negotiations to accept lower prices and profits.


    By the 2020s, all markets have become more concentrated. About 2,500 hospitals have closed or merged into regional chains. Walgreen’s and CVS dominate retail pharmacies. Pharmacy benefits management, a key link in the drug supply chain, is dominated by three companies, as is the wholesale drug industry. Independent doctors are joining doctor’s groups, some of which are being bought by Optum, a subsidiary of United Health. Health insurance is dominated by three companies, including United Health. While rural clinics (and hospitals) are closing, private clinics, often owned by hospitals or large healthcare companies, are opening in urban areas.


    This mergers and acquisition activity is a new form of vertical integration, where companies are buying companies on the other side of bilateral oligopoly markets.


    The drug industry is more complicated. Very large companies have been formed through mergers and acquisitions. But most of the new drugs have been developed by hundreds of new drug companies. Some of these companies have been acquired by the large corporations. Others have drug development or marketing arrangements with large companies. (In effect, the large companies have become venture capitalists in their own industry.)


    Mergers and acquisitions continue to be a major corporate strategy.


    Mergers and acquisitions in the United States have averaged over $1 trillion a year in the last five years. Globally, mergers and acquisitions are over $3 trillion a year, creating larger and larger multinational corporations.


    The government bailed out the entire financial sector (and General Motors) during the last recession.  Rather than breaking up the big financial firms, the government allowed (or forced) them to buy other large firms. The number of banking companies is rapidly declining; mergers and acquisitions are creating large regional banking corporations. The banking industry is now more concentrated than before the financial crisis.  


    The article really doesn’t make a strong case for “how mergers damage the economy.”  Maybe the “damage” isn’t so great because of the “countervailing power” (a phrase from John Kenneth Galbraith, used in a different context) of a small number of large companies on both sides of a bilateral oligopolistic market. But health care mergers across industry lines, creating dominant companies in local or regional markets, reduces the “countervailing power” effect.

    ===========================================================

    For the concept of bilateral oligopoly and why this is often the dominant form of market structure, see Bilateral Oligopoly.


  • The Beginning of the Industrial Revolution in America

    The Beginning of the Industrial Revolution in America


    In the Beginning

    PRECONDITIONS OF THE INDUSTRIAL REVOLUTION IN AMERICA

    Before industrialization began in the 1820s, there was a set of political institutions and cultural values, mostly inherited from England, that encouraged profit-seeking individuals to start new companies.  They included fairly secure property rights, increasing legal limits on monopolies, an independent judiciary that enforced contracts, emphasis on individual rights rather than social obligations, patents, tolerance of markets, and less government regulation of markets than in the past.  Much of this was stated or implied in the Constitution; an activist Supreme Court under John Marshall extended these trends. The Constitution also helped to create a national market and reduce transaction costs by mandating a national currency and limiting states’ ability to make economic policy that favored their own residents.


    What America did not inherit from England was important. Unlike England, the new United States did not have a king and a landowning nobility to siphon off capital. Settled by members of dissenting sects and persecuted religious minorities, there would be no state-supported national religion. As a consequence, capital would not be diverted to royal palaces, aristocratic castles, or cathedrals.


    Economists interested in economic development often advocate land reform in a traditional agricultural society as a necessary first step to modernization. This breaks the power of the conservative landlord class. America did not have to go through this step. Laws were passed even before the Constitution that made free and cheap land available to everyone. America began as a nation of landowning farmers. Thomas Jefferson saw independent farmers as the foundation of a democratic society.


    By winning the American Revolution, the new United States retained from England the political policies and ideas that would encourage individual economic “striving” and reject most of the English institutions opposed to progress and change. America was fortunate that it created a political structure, a democratic society, and an ideology that would support the coming Industrial Revolution. 


    In the early period of industrialization (1820-1870), a rapidly growing population (from 3 million in 1790 to almost 10 million in 1820 to 30 million in 1860) created an increased potential demand for new consumer products. Western expansion generated an agricultural surplus of commercial crops that were exchanged for cash to buy manufactured goods. Exports of cotton helped pay for imports of machinery, locomotives and manufactured goods.


    These conditions together could encourage economic growth but not necessarily industrialization, the large-scale production of capital goods (machinery) and consumer goods using inanimate power (steam engines and waterwheels) to drive faster, more powerful machinery. For that to happen, mechanics, tinkerers, investors, and entrepreneurs had to invent, innovate and organize new finance, production, distribution and marketing methods. Economic development drove economic growth.

    THE BEGINNING OF THE INDUSTRIAL REVOLUTION IN AMERICA

    A key factor explaining why America industrialized so early and so quickly was the country’s continuing ties with England after the American Revolution. Americans quickly understood the profitable opportunities of the new production methods being created in England. Americans also had access to much of the scientific and technical knowledge being created and applied in England. Ambitious Englishmen with technical knowledge, like Samuel Slater the founder of the American textile industry, came to America because they had more opportunity here to get rich. Americans read English scientific and technical journals; often, American like Robert Fulton went to England to see the new methods and machinery. The future Baltimore and Ohio Railroad sent an engineer over to England to find out about English railroad technology even before England had completed its first general purpose railroad. American mechanics and engineers quickly adapted English railroad technology to the American environment.

    One reason industrialization spread was the association of entrepreneurs with investment capital looking for new profit opportunities with mechanics interested in designing and developing new power-driven machinery, especially metal-working machinery.  In the beginning, many of the machine tools and power-driven machinery could be built using traditional craft skills, using traditional materials like wood and hand (or foot) operated tools. The power sources to drive the machinery were not a problem. Waterwheels had been used for hundreds of years in Europe; steam engines could be imported from England. They would soon be designed, improved and produced in America.

    America’s wealthy merchant class was more willing than England’s merchant class to invest in new industrial ventures.  The exception was railroads. There were speculative railroad investment booms in England in the 1840s and 1860s. 

    There were inspired geniuses like James Watt in England and Oliver Evans in America who greatly improved the steam engine, which had been in use in England since the early 1700s. Then modifications and adaptations of existing power-driven machinery and machine tools like lathes often led to large increases in productivity of particular products. In one early example, an American axe manufacturer hired a mechanic to design and development a die forging machine to produce axe heads. His machine increased the productivity of a single skilled striker and an assistant from 12 to 300 axe heads per day. It was these kinds of innovations that drove the Industrial Revolution.

    Americans often surpassed the English in their ability to mass-produce products at a lower cost. American products were generally not as good as English products but their lower cost, plus constant improvement, led to a great deal of innovation and high growth rates. Americans developed a reputation of making it fast, making it cheap today and improving it tomorrow. 

                                                                                                                 
    LABOR

    There was no labor shortage for the factories and mines because of high birthrates, high rates of population growth, open immigration, and the use of women in the industrial workforce. This was also a high quality labor force with high literacy rates among native-born workers. Also, there were no entrenched guilds of craft workers to discourage introduction of new production techniques or influence the organization of work in the factories.

    ADVANCES IN RAW MATERIAL PRODUCTION

    The Industrial Revolution would have been a limited affair if not for the huge increase in the production of metals, especially iron. The new steam engines, machine tools, and machinery were made out of iron and other metals. Fortunately, much of the new production technology – smelting iron ore with anthracite (hard) coal or coke and puddling pig iron to reduce the carbon content for forging – had been worked out in England and Wales in the 1700s. Americans had access to or knowledge of this technology when the demand for iron skyrocketed after 1820. Entrepreneurs built larger furnaces, brought over the new Welsh technology of smelting iron ore with anthracite coal, installed steam engines to heat and blow air into the furnace, and recycled waste heat to raise temperatures. The result was a big increase in iron production at a lower cost per ton. The increasing production of iron for casting and forging eliminated a potential bottleneck to rapid industrialization.

    Large amounts of iron would be vital to the development of the railroad industry.

    TRANSPORTATION COSTS

    The single largest transaction cost at the beginning of the Industrial Revolution was transportation costs. High overland transportation costs because of long distances and rugged terrain limited the size of markets and made products expensive.

    These high costs were first attacked on a large scale with the building of canals, inspired by the spectacular success of the Erie Canal (fully opened in 1825). Overland transportation costs fell by about 80%. At the same time, steamboats on Western rivers reduced costs and permitted upstream navigation. America had the largest navigable river network in the world. Then, starting in the 1830s, came railroads, another new technology developed in England. Within two years, American mechanics and engineers were modifying English designs to match America’s harsher conditions. American companies began producing locomotives and other rolling stock. American railroad companies figured out how to lay down track quicker and at a lower cost than the better built railroads of England. This was an early example of the American business ethos – build it fast, build it cheap, get it up and running, generate revenue, then fix and improve it.

    Compared to canals and steamboats, railroads offered huge increases in total carrying capacity, year-round operation, lower cost, greater flexibility and reliability, and big savings in time moving goods, people, and information. The explosion of needed information to run a large railroad created serious management problems, to say nothing of trains crashing into each other. The problem was partly solved by the creation of the telegraph. Railroads financed many of the early telegraph lines, often strung alongside railroad tracks. 
    Railroads also pioneered the decentralization of operations management into divisions that suggested the organizational structure for later industrial corporations.

    Throughout the Industrial Revolution, America had by far the largest railroad transportation system in the world. It overcame large distances and supported western expansion. Railroads moved agricultural goods to urban markets and ports, and manufactured goods to rural areas. They were vital to the creation of a national market.

    THE SPREAD OF THE INDUSTRIAL REVOLUTION

    The thinking of Francis Cabot Lowell, a Boston merchant, was indicative of a new kind of mentality that was crucial to the success of the Industrial Revolution in America. He was a newly rich merchant looking for new investments. Lowell saw cotton textile production as an integrated system in one factory. He thought about how the different production steps could be coordinated in one, large mill to reduce handling costs and increase overall productivity. Lowell raised the investment funds from fellow Boston merchants to pay for the high upfront capital costs of constructing large buildings and textile machinery. He was the founder of America’s first large-scale manufacturing industry – cotton textiles. He is also famous because he went to England to steal the designs of power-driven looms.

    What mill managers and mechanics subsequently learned from experience was that whenever they increased the productivity in any part of the production system it created bottlenecks elsewhere in the system. Better, faster machines would then have to be designed for other stages of production. This would create new bottlenecks; the process was one of continuous improvement in the production flow.

    Back to the axe example. When die-forging machines made many more axe heads per hour, this created a serious bottleneck problem in the milling (or grinding) of the head into the right shape.  New power equipment was invented to plane (or sand) the heads faster than the old technology. This, in turn, put pressure on the methods to temper (or harden) the heads; innovative new specialized ovens were designed to increase the product flow and improve quality. This same process worked in all successful companies in all industries that adopted power-driven machinery.

    Americans like Thomas Jefferson, Eli Whitney, and the technically trained officers of the army realized early the potential of the mass production of interchangeable parts that could be fitted together quickly by unskilled labor to produce and repair guns. Interchangeable parts, when fitted together with other interchangeable parts, eliminated the slow and expensive need for hand filing and fitting to make metal parts fit together. It took over 30 years to make the system operational. It made possible the mass production of new metal products such as sewing machines, typewriters, and automobiles. This new manufacturing process was so radical that English engineers called it the American System of Manufacturing.

    The cumulative effect of this industrializing process was increasing productivity, higher volume of output, better quality and lower unit cost. This trend spread to other industries with the application of general-purpose machine tools to new uses. Itinerant mechanics adapted their knowledge and experience to modernize the production of new products. Techniques developed in one industry were often transferable to new industries. Success in one industry inspired entrepreneurs to apply the same methods in other industries.  This is how the Waltham Watch Company got started; the founder was inspired by a visit to the Springfield Armory, famous for the mass production of rifles. Sometimes this occurred in the same company; Remington went from producing guns to producing sewing machines to producing typewriters.

    At first, industrial products were familiar products just produced at a lower unit cost by power-driven machinery in factories. Examples included cloth, shoes, paper, nails, clocks, and guns. Lower prices had the same effect as higher income; consumers had money left over to buy more of other products. But as production technology advanced – new and more specialized machine tools, the mass production of steel and the ability to work new materials – it became possible to design and produce new, complicated metal consumer and producer durables. New production techniques developed, such as the stamping rather than the grinding of parts. This led to the mass production of the automobile.===============================================================

    For a general discussion of American history between 1789 and 1860, see


    A New Nation, American History from 1789 to 1860


    Compare the American experience with that of England:

    The Beginning of the Industrial Revolution in England


    For the limits of Adam Smith’s thinking in explaining the origins of the Industrial Revolution, see

    Adam Smith’s Pin Factory


    For an excellent example of an entrepreneur at the beginning of the Industrial Revolution in England, see


    Josiah Wedgwood, the Wedgwood Pottery Company, and the Beginning of the Industrial Revolution.

    For the story of how England lost its economic leadership, see 

    A Cautionary Tale:  England and the Industrial Revolution.

    For a list of all posts, see List of Posts by Topic.


  • A Historical Example of Bilateral Oligopoly:  Baldwin Locomotive Works

    A Historical Example of Bilateral Oligopoly: Baldwin Locomotive Works

    Baldwin Locomotive

    Baldwin, the largest producer of steam locomotives in the                 nineteenth century, faced problems typical of a dominant company in a bilateral
    oligopolistic industry.  Almost everything that               happened at Baldwin
    was conditioned by a highly cyclical, almost   unpredictable competitive
    environment.  A high level of business       risk followed from sudden, large fluctuations in demand. This         meant that Baldwin
    often had excess capacity with substantial         fixed investment, leading to a
    strategy based on economies of scope and not economies of scale.  Baldwin also depended
    on a skilled       labor force with firm-specific knowledge and experience that was    exposed to sudden and massive layoffs followed by the company’s   attempts to
    rehire the same workers.  It is hard to
    imagine a more    challenging competitive environment.                                                    


    Baldwin was a large and dominant
    firm, accounting for approximately one-third of all steam locomotive
    production.  The buy side of the market
    was dominated by a small and increasingly concentrated number of railroad
    companies, which were some of the largest corporations in America
    in the nineteenth century.  The sources
    of market power of the locomotive builders were their specialization and flexibility
    in production, although some of the larger railroads – Baldwin’s
    largest customers – also built locomotives in their own machine shops.  The sources of market power of the railroads
    were their large purchasing power, technical knowledge of their “master
    mechanics” who ordered equipment, and knowledge of the optimal mix of equipment
    for their particular company.  In such an
    environment, Baldwin had market power because of its
    size and assembly expertise, but never enjoyed the market control of a mass producer
    of standardized products.  Market power
    based on marketing to final consumers was not feasible; railroad customers did
    not demand that railroads use Baldwin engines.


    Every large railroad developed its own specifications and
    demanded customized equipment from Baldwin.  In addition, there was continuous
    technological improvement of the basic steam locomotive, often innovated by
    railroad technical staff.  As a
    consequence, Baldwin could never control the pace of
    design change.  The company could not totally
    incorporate mass production techniques because of constantly-changing
    customized design and finish.  On the
    other hand, by working closely with its customers over a long period of time, Baldwin
    probably had lower transaction costs than if its sales were arms-length market
    transactions.


    This mutual dependence, along with railroads’ credible
    threat of internal production, usually gave the railroads a bargaining
    advantage when negotiating design customization and price with Baldwin.  But working closely with its largest
    customers, particularly the Pennsylvania Railroad, also increased the
    probability of Baldwin’s long-run survival. 


    This symbiotic relationship between steam locomotive
    builders and the railroads worked as long there was no fundamental innovation
    in engine design and both sides benefited from continuous improvement in the
    steam locomotive.   The bilateral
    relationship would be much different in the later market for diesel engines in
    which General Motors controlled the technology and forced railroads to buy
    standardized products.


    Baldwin’s management objectives were
    to minimize risk and maximize operating flexibility by sharing risk with
    suppliers through subcontracting out much of its parts production.  Since production was to order, Baldwin
    managed a “just-in-time” parts inventory system that minimized working capital
    requirements. When times were bad, Baldwin could delay
    payment to its suppliers and thus use them as a major source of working
    capital.  This was one way the company
    dealt with severe cash flow problems in economic downturns.


    The company countered the potential loss of skilled workers
    after massive layoffs with high wages, skill development through apprenticeship
    training for employees and sons of employees, and the hope of higher income for
    long-term employees through a system of internal promotion and inside
    contracting.  Inside contracting, usually
    managed by long-term employees, put pressure on contractors to keep labor costs
    down.  This led to much more cooperative,
    less confrontational labor relations policies than those of other large-scale
    employers like Carnegie Steel.


    Horace L.Arnold – “Modern Machine-Shop Economics.” in Engineering Magazine, 11. 1896


    Because of the complex nature of its production, Baldwin
    needed sophisticated internal systems to keep track of parts, subassemblies,
    and final production schedules.  The
    company substituted detailed cost and internal job flow information for
    management control bureaucracies.  While Baldwin
    did little internal product development, it was very quick in applying advances
    in product design and production technology. 
    But the company never “bet the ranch” on internal development of a
    radically new design of steam locomotives.


    The long-term success of
    Baldwin, under highly uncertain market conditions,
    raises the issue of the limitations of the multidivisional form of
    organization.  Multidivisional
    corporations often do not stay focused on production of key product lines and
    the development of core competencies. 
    Rather, they are prone to the danger of more diversification than they
    can efficiently manage, with the related danger of diseconomies of scale.


    When diesel locomotives
    became less expensive to operate and maintain than steam locomotives,
    Baldwin tried to adjust but its technology and skill
    base was too specialized to adopt the new technology. 
    Baldwin did
    innovate, designing and producing more powerful and efficient steam engines.  But to no avail. 
    Baldwin was
    doomed, another victim of “creative destruction.”


    COMPANIES SIMILAR TO BALDWIN

    A suggestive line of inquiry might be the similarities between
    Baldwin’s strategies and those of Japanese companies to
    minimize risk and maximize innovation in a highly uncertain and changing
    environment. Large Japanese companies
    followed similar strategies in the early phases of their industry growth. A big difference was that zaibatsu risk was reduced by the actions
    of the Japanese government and related financial institutions.


    Probably the current companies most similar to Baldwin
    are capital goods companies that sell large, complicated systems.  Another suggestive analogy might be the
    similar strategies adopted by organizations such as financial software
    companies that build large, complex systems, such as SAP
    or Oracle. 
    Any company that relies on
    employees with firm-specific skills and experience, including knowledge of the
    requirements of large customers, face many of the challenges that Baldwin
    did.