Tag: Global Economy

  • The English East India Company (EIC):  Trade with Asia

    The English East India Company (EIC): Trade with Asia


    The Mughal emperor Shah Alam hands a scroll to Robert Clive, the governor of Bengal, which transferred tax collecting rights in Bengal, Bihar and Orissa to the East India Company. Illustration: Benjamin West (1738–1820)/British Library

    INTRODUCTION


    The English East India Company (EIC) was an innovative new type of corporation. It is a model for the modern limited-liability, stockholder-funded modern corporation.


    The EIC also illustrates that the prototype of the modern multinational corporation was created to develop global trade.


    HISTORIC BACKGROUND


    The creation of the English East India Company (EIC) and its Dutch equivalent (the VOC) were part of the 400-year expansion of European power, trade, and influence. Much of the rest of the world became colonies, part of imperial empires.


    By 1600, both England and Holland had a wealthy merchant and shipping class, bankers, substantial liquid capital (wealth) not tied up in land, and risk-takers. These categories overlapped.


    Both countries had limited monarchies. In England, the king and Parliament were about to begin a long struggle for power. In Holland, the monarch was mostly subservient to Holland’s powerful and wealthy merchant class.


    THE EIC: STRUCTURE AND STRATEGY


    The East India Company (EIC) was chartered in 1600 by Queen Elizabeth I to promote and monopolize English trade with Asia. England, a poor country in the 1600s but with colonial ambitions after defeating the Spanish Armada in 1588, outsourced its colonial ambitions to the East India Company and other private companies. 


    The East India Company was originally privately funded by 218 merchants and other investors. It was the first modern multinational corporation. The EIC was a joint stock company, that is, a company with publicly traded stock bought and sold in a secondary stock market. Like modern companies, the EIC issued financial reports, held annual meetings for stockholders, and had quarterly meetings of the Board of Directors.


    It was also a limited liability corporation. Stockholders’ potential personal financial loss was limited to their investment in the company. Creditors could not go after their personal assets.


    The EIC was vertically integrated. The company designed, built and repaired its own ships, built its own docks and warehouses in London and in India. It had a large corporate headquarters in London. The company held sales auctions of its imports in its headquarters. It was a major employer in London. It was an “enlightened” employer, offering fringe benefits, including pensions. It provided a retirement home in London for sailors.


    The EIC designed and built a new type of ship, called East India Indiaman. They were built for long-distance trade. Because of commercial rivalry with other European states and local hostilities in Asia, EIC merchant ships were heavily armed and often contained marines.


    East India Company Indiaman Armed Merchant Ship

     ©National Maritime Museum


    The EIC had to build forts to protect its warehouses and trading stations. It hired a mercenary army and develop a navy (Bombay Marine) to protect property and trade routes. It negotiated with local rulers and signed treaties. 


    In short, the company built its own self-contained infrastructure and pursued its independent strategies. 


    The company ran its own management training programs and military academy. The selection process of employees was highly competitive, including written exams. Many of its recruits were ambitious young men from the lower and middle classes who were barred from the traditional paths of upward mobility and status. It employed “foreigners,” Scots and Anglo-Irish. Later, the EIC employed Asians and Anglo-Indians in secondary positions.


    Economists have a warm spot in their hearts (yes, economists do have hearts) because the EIC was the first organization to employ and pay economists – Thomas Robert Malthus, James Mill, and his son John Stuart. John Stuart Mill was effectively the CEO for many years. Contrary to their economic writings, they did not support free trade with Asian countries. 


    EIC “officers” and employees were loyal to the EIC. They saw personal opportunities and advancement within the company. They had opportunities for personal power and wealth that were not available at home. Because of their lower class origins and nationality, wealthy returning EIC officers were often resented as upstarts.


    The EIC created a powerful lobbying group in England. The company attempted to get the English government to continue to support its monopoly on English trade with Asia. Important politicians and royal officials were bribed.


    Unlike other private trading and colonization corporations established in England at about the same time, the EIC was set up as primarily an importing company. The company had the problem of how to pay for products bought in Asia. English exports to Asia such as English woolens were in limited demand. Asian sellers wanted silver. This created a drain of silver out of England, which was a source of friction between the company and the government.


    CORPORATE STRATEGIES AND POLITICAL ENVIRONMENT


    Besides the English-Asian trade, the East India Company was willing to trade anywhere in Asia, looking for profitable opportunities. Its resources, both ships and men, were highly mobile.


    The EIC operated in a violent, insecure environment in Asia. Beside pirates and local conflicts with Asian rulers, England was usually at war with one or more European countries. The conflicts extended to trade rivalry in Asia. The EIC had to fight battles with other national trading companies, foremost of which was the Dutch East India Company (VOC, the initials of the Dutch name of the company). The EIC could not expect much support from England, which was unable to consistently project power in Asia until the 1800s.


    The EIC lost out to the Dutch East India Company in its attempts to control the Spice Islands, the source of much of the profitable spice trade. The EIC also lost its footholds in Java and nearly islands, which became the Dutch East Indies (later Indonesia) controlled by the VOC. 


    Many early trading stations failed in other parts of Asia. Eventually, operations were centered on trading ports (entrepots) and stations in India, the traditional transit area for Asian products bound for the Middle East and Europe. India was also an important source of pepper.


    The EIC was caught up in the Seven Years War (1756-1763) between England and France for dominance in Europe, North America (called French and Indian War in America), the West Indies, and India. The EIC, under the leadership of Robert Clive, was able to defeat the French in India and expand alliances with many local rulers. The company’s well-organized military assets with superior firepower made the company a prized ally for local rulers. In exchange, the company was given extensive privileges including the right to collect taxes.


    At the same time, the company was developing what would be its most important trade – importing Chinese tea to England. To support this trade, the EIC established new stations that would grow to be Singapore and Hong Kong.


    They immediately ran into an old problem – China didn’t want any English imports. Chinese merchants only wanted silver, which led to a major drain of silver out of England. The EIC solved the problem by growing and selling opium produced in India to private traders who smuggled it into China. Some of the financial transactions were handled by a bank that eventually became HSBC.  (One the traders was Franklin D. Roosevelt’s grandfather.) 


    Chinese attempts to ban this trade resulted in a war between China and England (the Opium War, 1839-1842). China was defeated by superior English warships; the subsequent treaty was the first of many that opened up China to foreign influence and then domination. This would have important long-run consequences.


    The demand for tea exploded in the 1700s. The EIC had trouble fulfilling the demand with tea from China. Growing and processing tea was a closely guarded secret in China. But the company smuggled out plants to start new tea plantations in northern India (Assam). These plantations were successful and an increasing source of tea for the EIC. By 1770, EIC exports of Indian tea to England reached £800,000.


    ORGANIZATION STRUCTURE, CONTROL, AND GOVERNANCE


    Besides the EIC’s legal, financial, and governance structures which were innovative, the EIC had an internal management and control structure very much like a modern multinational corporation. It had to find a balance between home office control and branch management initiative. Given the problems of long distances, slow communication, and changing local operational information, the company was forced into a decentralized structure. 


    The Board of Governors combined the oversight of corporate managers with the setting of governing rules and regulations. Much of their control was financial. There was also detailed supervision and control of the voyages sent out from England.


    While officers of the company often sent detailed instructions about policy to local managers, direct operational control was difficult. It often took over two months for a letter from London to reach India. Local managers had discretion to react to local problems and trading opportunities. They had their own staff and resources. They were similar to “divisional” managers of early railroads and large industrial corporations. Even more similar to corporate presidents and their local staffs of national subsidiaries of multinational corporations.


    THE EVOLUTION OF THE EIC FROM A GLOBAL TRADING COMPANY TO A VIRTUAL SOVEREIGN STATE


    The painting above shows the moment when the EIC began its evolution from profit-making global trading company to de facto sovereign state. The year was 1765. The Mughal emperor was forced to turn over tax collection in Bengal and two other states

    to the EIC.


    It was at this moment that the East India Company (EIC) ceased to be a conventional corporation, trading in silks and spices, and became something much more unusual. Within a few years, 250 company clerks backed by the military force of 20,000 locally recruited Indian soldiers had become the effective rulers of Bengal. An international corporation was transforming itself into an aggressive colonial power.


        William Dalrumple, The Guardian, “The East India Company:  The Original Corporate Raiders,” March 4, 2015.


    The EIC was profitable in its early years. The EIC started its evolution from a purely private commercial company to an organization with its own substantial political and governmental responsibilities. For almost 100 years after the Seven Years War, it governed much of India from Bombay (Mumbai), Calcutta (Kolkata) and Madras (Chennai). The large areas around company headquarters in Calcutta, Bombay, and Madras were also effectively ruled by the company, often through “concessions” offered by regional rulers.


    The company performed the major functions of a government – collected taxes, funded a military, made laws and regulations, and established a national bureaucracy. Many of its officers became rich because of IPOs (Indian Political Opportunities – aka bribes, private deals, kickbacks on contracts). Stockholders back in London just wanted profits but EIC officials in India saw the personal possibilities as tax collectors and political administrators.


    As the EIC evolved from a commercial venture to ruling much of India, it became unprofitable almost from the beginning. By 1773, low tax revenue partly due to famines contribute to £1.5 million in debt and a £1 million unpaid tax bill owed to the English government. The company asked for a large loan, over £1 million from the Bank of England, but received only £200,000. 


    This began many rounds of negotiation between the EIC and the English government. The company began borrowing large sums of money from the English government. In the early 1800s, the company exchanged loans from Parliament for government over-site and military support. Parliament stripped the EIC of its trading monopolies between Asia and England. Finally, after the 1857 Sepoy Mutiny, the English government took over overall management and supervision of the company and then annexed India as a British colony.  


    The EIC also came into conflict with the English government when the government tried to impose mercantilist goals on the company. The government, under pressure from its woolen textile industry and then the new English cotton textile mills, banned the company from exporting competing Indian cotton goods (calicos) into England. India cotton, not cotton textiles, was exported to England. India became a large market for the export of English cotton goods.


    The EIC start out as a profit-seeking trading company and ended up ruling much of the Indian subcontinent. The costs of administering India would eventually contribute to bankrupting the company; it was forced to turn over the rule of India to the English government.   


    The home nation-states such as England were becoming more powerful and were able to project power and influence globally. They did not need private trading monopolies to further mercantilist or economic goals.

    CONJECTURE

    This conjecture is a bridge to the next essay on the EIC :

    The English East India Company:  Model for Future Multinational Corporations?


    In 1765, the EIC took over the running of a large territory in India – policing, military, tax collection, and administration. By 1772, it would deeply in debt and needed a large bailout from the English government. They gave it. It was followed by subsequent bailouts until the English government finally took over the EIC after the 1857 Sepoy Mutiny.  Why? Why not take it over earlier?


    Subsidizing EIC was the least bad option.  In 1763, England completed its victory over France. It was the third war with France in the 1700s. England was deeply in debt. As a result of incredible stupidity, England had to commit naval and army assets to control the restless American colonies. The English navy also had to protect the sugar islands in the West Indies, and to its primary task of securing the English Channel. It did not have the military assets to commit halfway around the world to India. It was not necessary – The EIC had a private army of over 20,000 troops that grew to 260,000 in the early 1800s, plus a heavily-armed merchant maring, as the EIC took over governing most of India. This number was far larger than the English army.


    Ten years after the EIC became sovereign in Bengal, the American Revolution broke out. England sent a large part of its army and about half of its navy to quell the revolt. After a few years, when English officers realized the cause of subduing the colonies was hopeless, some of the assets were withdrawn but sent to the West Indies. England withdraw its armed forces from America in 1783. Ten years later England was at war with France; the war, mostly with Napoleon, lasted 22 years. At the end, England was deeply in debt.


    With the loss of the American colonies, India was the foundation of the British Empire. Although losing money, the EIC was responsible for generating nearly half of England global trade. India was a major market for English exports. Quite simply, the EIC was England’s surrogate colonial masters in Asia. It was cheaper to subsidize the EIC than to take over direct governing of India.


    Another reason was that the EIC have bribed government ministers and members of Parliament. Returning EIC personnel, often personally wealthy, also formed a strong lobbying group in England.


    But after four decades of peace in Europe and reducing its public debt, England was ready to begin governing India and projecting imperial power throughout Asia.

    ======================================================


    One starting point of reading about the East India Company is:

    K.N.Chaudhuri, The English East India Company:  The Study of an Early Joint Stock Company, 1600-1640, Frank Cass & Co Ltd, London, 1965.

    For the historical background and context on the EIC, and its role in helping England become a global economic and political power in the 1600s, see

    England in the 1600s:  The Beginning of England’s Rise to Global Power and Wealth

    For the argument that the EIC may be a model for future multinational corporations, see

    The English East India Company:  Model for Future Multinational Corporations? 

    Elsewhere in this blog, I argue that the main form of America’s economic competition, and probably geopolitical competition, with China will depend on the success of American companies in developing new technologies and global links. See


    American Tariffs and the U.S. Economic War with China

    For a case study of a country that became independent after World War II and illustrates the internal chaos of many countries, see


    Nigeria


    You might also be interested in

    The Stock Market Crash of 1929 and the Beginning of the Great Depression


    In the 1920s, the United States developed new technologies in virtual isolation from the rest of the world. It didn’t end well.


    For a list of all the posts on this blog, see List of Posts by Topic

    with links to all other posts. There are posts on Adam Smith, the Beginning of the Industrial Revolution, American Economic History, American History and even economics.


  • Demographics and Population Projections of Japan

    Demographics and Population Projections of Japan


    INTRODUCTION


    Japan gets special consideration because it is further along the demographics declining population curve than any other large country. It has the oldest population (highest average age) in the world. It has one of the world’s lowest birth rates. Unless there are major changes in healthcare technology, immigration, public policy, and birth rates, most industrialized countries will follow Japan down the path of declining and aging populations, and smaller labor forces.


    Japan’s demographics and immigration have become major political issues. In the July 2025 elections, two right-wing parties made substantial gains against the long-ruling Liberal Democracy Party (LDP). Two of their main issues were the rapid rise of immigration and the repeal of a 10% consumption tax used to pay for the rising costs of supporting the aged. Both parties appealed to young voters. The LDP has nominated a candidate for prime minister who also takes a hard line on immigration.


    PROJECTIONS


    Japan’s current (2024) population is around 122 million people. This is the 15th year of population decline, down from a high of 128 million. The yearly decreases so far have been small, both in numbers and as a percent of the total. This is expected to continue until 2030. Then population decreases are expected to accelerate to a population of 104 million in 2050 and 87 million in 2070. At the end of the century, Japan’s population is projected to be 60-65 million people, about half its current size.


    The high dependency ratio (the number of elderly divided by the number in working age groups – 46%, the highest in the world) is expected to rise to about 70% in 2050, about 75% in 2070 and about 80% in 2100. Not everyone in the working age group is in the labor force. Thus, by 2100, there will be almost one Japanese over 65 for every employee in the labor force. Government budgets will find it increasingly difficult to raise tax revenue to meet the rising social costs of an aging society. 


    Figures are from The Economist, “Japan’s economic troubles offer a glimpse of a sobering future,” December 5, 2019.


    Japan has one of the lowest birth rates in the world at 1.2 in 2023. Also in 2023, the number of deaths was twice the number of births.

    Japan has the world’s oldest population, both as measured as average age and with the highest percent of residents over 65. 


    LABOR FORCE AND FUTURE ECONOMIC GROWTH


    Over the past 20 years, Japan’s working-age population has declined by more than 10 million workers, about 14% of the workforce. The current labor force (age group 15-64) is 73 million. By 2050, Japan’s working-age population is expected to fall to 53 million. (U.N. World Population Prospects 2022) In 2100, the labor force age group is expected to be about 32 million, about 40 million less than the current size. 


    Japan’s 65 and older population of 37 million is about 25% of the total. As early as 2050, about 40% of the adults will be over 65. Surprisingly, the number of Japan’s elderly is already near the projected maximum.


    Current statistics from Japan’s Internal Affairs Ministry, July 24, 2024.


    Projections from:

    Statistica, ”Forecast of the total population in Japan from 2023 to 2120,” November, 2023. https://www.statista.com/statistics/607427/japan-forecast-total-population/


    Statistica, “Forecast of the total population in Japan from 2023 to 2120, by age group,” November 2023. https://www.statista.com/statistics/612575/japan-population-age-group/


    Japan admitted few immigrant workers in the past to increase its labor force but the yearly number has been rising, up 330,000 in 2023.  In 2025, there were 3.8 million immigrant workers in Japan. This was over 3% of its labor force. Most are on short-term or work visas (Japan calls them “trainees”) and are not expected to stay. Japan rejects 99% of applications for asylum. Under current law, it is very difficult for immigrants to become citizens or permanent residents.


    In Japan, the labor force and the population are decreasing at about 1% per year. Productivity is increasing at about 1.3% per year, giving economic growth of 0.3% per year. But because of decreasing population, output per person is increasing at about 1.3% per year, or about the same as in the U.S. Growth rates are much lower but the increase in output per person is about the same. This may be one reason there is very little call for any economic, political or social reform in Japan despite almost no economic growth. And this has been going on since the 1990s. But the demographic trends may increase tensions between younger workers and retirees.


    Japan’s real GDP has been basically stagnant over the last 25 years. Without structural changes to Japan’s political and economic system, Japan’s real GDP in the future will grow slowly at best and eventually decline along with its labor force and population.


    As the size of the labor force decreases at a higher rate, and faster than the older age group, it is likely that output per capita will start to decrease.


    THE STRUCTURE OF THE JAPANESE LABOR MARKET


    The number of employed Japanese has not fallen as much as the decrease in the number of people in the prime labor force age groups. Until recently, this has been due to the increased participation rates of women in the labor force. But the high current female participation rate suggests little if any increase in workers from this past trend.


    While female employment rates are high, over 50% of female employees hold part-time positions as seasonal or temporary workers. This means they are not covered under lifetime employment or job security guarantees. Many full-time female workers are classified as temporary to avoid giving them lifetime employment protection. As a group, female workers are probably underemployed.


    As in other countries, employment does not stop at retirement age.

    In Japan, as in the United States, many people over retirement ages own or work in small businesses. So the numbers in the prime working ages do not coincide with the number of employees. 


    Japan’s retirement age is 60, although older workers can request to work until they are 65. Many retired Japanese buy or work in small, local businesses such as noodle shops, small grocery stores or other kinds of small stores to supplement public or private pensions. Over 1/2 of Japanese aged 65-69 and more than 1/3 aged 70-75 are employed to supplement small retirement benefits. The percent falls to 12% for over-75. There are about 22 million in the over-75 category. Over-75s in Japan is about the average of over-65s in industrialized countries.


        The Economist, “Japan’s 2025 Problem,” in The World Ahead

        2025, 38.

    As more people work beyond retirement age, countries will have to reassess retirement benefits and taxes on the elderly.


    The Japanese government projects that social-security costs, including pensions, will increase by 60% between 2025 and 2040. A change in the pension system, probably to increase pensions, is scheduled for 2025.


    Over 1/3 of the total foreign workers are from Vietnam, China or the Philippines. They tend to work in manufacturing or construction. Many recent immigrants come from Nepal or Myanmar. There is a lack of Korean workers. Japan is now attempting to attract foreign employees with technical skills or higher education.


    About half of Japanese employees are between 45 and 54 years old. This indicates that about half of Japan’s current labor force could retire in the next 20 years.


    Japan’s unemployment rate is low, between 2% and 3%. There is much discussion about companies finding it hard to hire as many employees as they would like. Government ministries are concerned about a national labor shortage that can only get worse. This would probably contribute to low economic growth in the future.


    A peculiarity about the Japanese labor market. The definition of unemployed is more restrictive than in other countries. No one knows what the unemployment rate would be if Japan used the American definition.


    The low unemployment rate, a slight decrease in the number of employed Japanese and the labor shortage, combined with higher inflation rates, are putting pressure on wage rates. In 2023, the average wage increase was around 5%, which is high for Japan. Wage increases might continue.


    The overall impression is that the Japanese labor market is not very flexible and that workers tend to be less mobile than they might be under different rules and regulations. This may also be obstacle to raising labor productivity and a barrier to higher economic growth in the future. 


    JAPAN AS A MODEL – OLD AND RICH


    Japan might serve as a model for future demographics of other countries in two different ways. One is as a model for countries with a high per capita income. The other is for countries that have a lower, often much lower, per capita income but are aging rapidly. This includes China and most of the countries of east and southeast Asia. They will grow old before they grow rich.


    Most of the countries in east Asia, including China, have a birthrate equal to or lower than Japan’s. They are on a similar demographic curve, only a little behind. The difference is that Japan is much richer, with a substantially higher income per capita. If managed right, Japan has the resources to pay for adequate levels of support for its increasing numbers of senior citizens. The other countries will age before they achieve per capita incomes anywhere near Japan. This will probably put a greater strain on their public finances and they will not be able to provide adequate health and services support for their aging populations.


    In economic theory, deficit-financed government spending is expected to make up for weak private consumption and domestic investment spending to ward off deflation and recession. In the future environment, however, demographics can overcome aggressive monetary and fiscal policy to stimulate economic growth. These policies have already failed in Japan. Zero interest rates on public debt, large budget deficits, high levels of government infrastructure spending and the highest national debt/GDP ratio in the world have not improved very low economic growth. A current (2025) rise in inflation rates and wages will put further strain on the Japanese economy.


    The large budget deficits are financed by borrowing much of the country’s household savings at near zero interest rates. Japan’s central bank has just raised its equivalent to the Fed funds rate to 0.25%. Other central bankers are not impressed.


    There is no chance of balanced budgets in the future. A rise in interest rates would make Japan’s financial problems worse.


    Domestic demand is weak even though unemployment is low. Rather than raise wages, Japanese companies export manufacturing to other countries, especially China and other Asian countries. The is accompanied by substantial investment outside of Japan.


    Japanese companies are starting to substitute robots for workers in Japan. Japan expects to greatly increase its use of robots, partly in health care services.


    An aging population contributes to social and political resistance to structural reforms. The dominant political party substitutes government spending and subsidies, combined with appeals to Japanese traditions, for reforms that might threaten social stability. But there is a political backlash among young voters against the dominant party that they feel represents the interest of older voters.


    All of this is before the economic costs of climate change and global warming. Japan in the past has suffered from devastating earthquakes. A recent tsunami destroyed a nuclear power complex.


    HOW JAPAN IS DEALING WITH DECLINING LABOR FORCE


    Japan is admitting foreign workers to increase its labor force. There are now about 3.8 million foreign workers, about 3% of the labor force. Foreign workers, as in Saudi Arabia, the United Arab Emirates and Singapore, are mostly segregated from the locals. Immigrant workers have no citizenship rights and can be deported at any time.


    If Japan makes up the decrease in the size of its labor force with foreign workers, then by 2100 foreigners will make up about half of Japan’s workers.


    Japan is a major producer of robots but the number of robots as a percent of employed workers is below China and South Korea but above other industrialized countries. This percentage (robots per 1,000 workers) is expected to rise. Japan is using some of its robots to provide services and companionship for senior citizens.


    CONSEQUENCES OF JAPAN’S DEMOGRAPHIC DECLINE


    Small number of children


    The projection for Japan is that in 2100 there will be five times as many senior citizens over 65 then children aged 0-14. Children will make up less than 10% of the total population. No one seems to be thinking about the social and psychological consequences of this trend. Importing children for adoption? Surrogate mothers from other countries? Robotic pets and children as substitutes? (No joke – there are already robotic dogs and ponies.)


    Continued cultural isolation?


    Japan has been the most successful country in segregating its culture and moral values from outside influence, first as an island closed to outside influences (1600-1850s) and even now in the global communication world. Despite surface similarities to other modern economies and cultures, Japan remains opaque to outsiders. This might make it difficult to attract permanent immigrants and integrate them into Japanese society. 


    More outmigration of Japanese?


    As the dependency ratio increases, putting a larger tax burden on working Japanese, it is possible that more Japanese will emigrate. One way might be to work for the overseas operations of Japanese corporations. Or join the Japanese communities in other countries such as Brazil or the United States. Or imitate the strategies of wealthy Chinese who are planning to leave their country. This will further decrease the number of births, the size of the labor force and the tax base.


    Family vs. state care of the aged


    With more Japanese not having children, the cultural imperative of children supporting elderly parents will be impossible to fulfill for many families, putting more of the burden on the state.


    Part of the global economy


    It is hard to see what future role Japan will play in the global economy besides as a source of financial capital. Japan might be relatively less important in the future. Already, Japan is not particularly innovative. The country is not a leader in most new tech industries – mostly robotics companies, a few pharmaceutical companies, some legacy technology in consumer electronics and online entertainment. Japan has already outsourced much of its manufacturing to other Asian countries, particularly China.


    ============================================================


    For a other essays on demographic topics, see


    Global Demographics and Population Projections


    Demographics and Economic Growth


    Demographics, Immigration and Future Economic Growth of the United States


  • After the Virus: Economic Consequences

    There are a number of forecasts of what the world will be like after the virus. Let’s take a look at some of them.

    Many long-term trends have been accelerated by the virus. Probably the most cited example has been the accelerated move to digital-based transactions and behavior. This has occurred among both consumers and businesses.

    I think we have hit an inflection point. Before, there was a great deal of discussion about how one industry or market was becoming more dependent on digital platforms and automation based on artificial intelligence. The Internet of Things, online shopping and ordering, business conferencing, telemedicine. Or how a particular company was transforming an industry (Amazon, Uber). But now we see that the entire economy – all industries and markets – rely on digital. The technology and rapid adaptation are accelerating the shifts.

    Income inequality is bad and probably getting worse. The usual reasons given are outsourcing in the global economy and the effects of automation. The two reasons are related. Advances in telecommunications, including global digital networks, and management software have made the management of multinational companies possible. 

    There now appears to be another reason. We talk about the growth of the service economy. What this means specifically is that most of the new jobs created over the last few decades have been relatively low-paying service jobs. About 15% of the entire labor force (about 25 million people) works in restaurants and bars. Much of the service industry consists of services that relatively low-paid workers provide to relatively high-paid and wealthy customers. A recent study indicated that unemployment among service workers in the affluent parts of New York City was higher than in the rest of the city. On the other end of the income scale, the upper-middle class, dominated by the technological and professional elite, have seen their average incomes rise much faster than low-paid service workers. As digital replaces service workers, including office workers, income inequality and its political consequences will probably get worse.

    The move to the digital economy will also threaten many owner-managed small businesses. Because of economies of scale and scope, large digital-based corporations will lead the trend towards more concentrated industries and markets. 

    Another consequence of the accelerating use of digital platforms is the demand for technological workers will probably also accelerate. Salaries will go higher. Automation and AI software will “deskilled” (lower salaries) professions based on specific knowledge and eliminate many manufacturing and office positions. Online business collaboration will become more common. Video conferences may not be as effective as face-to-face conferences and interaction but they are a lot cheaper than leasing office space in Manhattan.

    We don’t have to worry about the huge increase in government debt. Well, maybe. Almost all of the government “stimulus” programs are income maintenance programs. They are paid for through government borrowing, a large part of which is directly or indirectly selling debt to the Fed. The Fed pays for the debt by creating money. All this does is transfer federal debt from one part of the government balance sheet to another part. 

    As long as the Fed keeps interest rates extremely low, the cost of debt service (federal interest expense) as a percent of nominal income will be low.

    A few comments. Large yearly deficits and the total national debt will continue to increase for years after the virus comes under control. None of this debt will disappear. Total debt service costs will rise, even at extremely low interest rates. If for some reason, such as inflation, interest rates rise, the cost of interest expense could rise dramatically. By fiscal 2022, a one percent increase in federal borrowing costs could add at least $250 billion to the yearly deficit. The federal government could avoid most of any potential future interest expense increases by financing the national debt at the current rate of 0.6% for 10 year bonds.

    The Fed might want to sell off some of the government debt they have accumulated. They basically have to sell it to someone else who wants to hold U.S. government debt. This increases the supply of U. S. government debt offered to be sold. It might raise interest rates on all of the national debt. 

    Even if tax revenue increases, which will happen if there is an increase in taxable nominal income without tax cuts, the continuing large deficits will put pressure to reduce outlays on “discretionary” spending. That is, all spending after Social Security, Medicare, defense, federal pensions and interest on the national debt. Unless taxes are raised substantially, it is likely that in a few years all “discretionary” spending will be funded by new debt.

    There will be little, if any, distinction between monetary and fiscal policy. The pretense that the Fed makes monetary policy independent of the rest of the government will not be credible.

    The amount of lost income should go down as the economy expands and employees go back to work. The fiscal stimulus programs basically replace the lost income of workers and small business owners. Lost income may be about $400 billion per month, including PPP subsidies of salaries. $3 trillion in income maintenance programs won’t last long. The programs are expected to end or be reduced between August and October. 

    To avoid a worse recession, income maintenance programs will probably be renewed. With the number of virus cases rising rapidly, the recovery of the service economy may be slower than forecasted. If the number of virus cases do not go down soon, service businesses either cannot open, are restricted, or customers will be afraid to patronize service establishments or entertainment venues. Many small businesses will go bankrupt. Income maintenance programs may have to be greater than assumed and continue for a longer time. Or both. We could see high unemployment levels, a surge in bankruptcies, and even higher future government debt levels.

    State and local finances are even worse. State and local governments cannot create money to cover deficits. Inadequately funded public pensions were already killing some state and local budgets before the virus hit as more public employees were retiring. These governments, which provide most of the public goods and services, will have to cut services. Already large numbers of employees, including health care workers, have been laid off. Public office workers will be laid off as more interaction with citizens will be done online. Possibly more public education will also be done online, especially at the college level. Many of these employees qualify for pensions. The federal government would have to borrow trillions of additional dollars to support state and local governments.

    Longer term. Health care is now the largest industry in the United States and growing faster than the rest of the economy. It is also a major and growing part of the federal budget. But there is no way health care benefits paid by Medicare programs are going to be cut. The number of senior citizens is expected to double in the next 20 years. Senior citizens make up a large percent of voters. Over 30% of the Florida voters in this year’s presidential election will be senior citizens. In a close election, the winner must take Florida. I doubt if a candidate campaigning on a platform of cutting health care services to slow down the growth in Medicare costs would do well in Florida and elsewhere.

    All of this indicates that government money to tackle societal problems – large increases in investment in infrastructure, funding the huge costs of climate change, programs to increase the low rates of economic growth and productivity, new income maintenance programs, and many others – will not be available in adequate amounts. What this means is that the costs of mitigating the damage from climate change will be higher than expected. 

    One partial answer to these problems is accelerated innovation in new technology, especially in health care. This is likely to happen. Senior citizens, technology companies, and their employees and stockholders will benefit. But unlike the past, the new technology may be highly disruptive by increasing long-term unemployment and income inequality. Whether or not new public programs and policies will be created is uncertain in the current political climate and the future reality of government budgets. If not, the types of social, economic and political conflicts we are currently experiencing could get worse.

    For background on understanding government finance, budget deficits, trade deficits, and how they are related, see my Government Finance 101. This post also discusses the fiscal effects of Covid-19.

    You might also be interested in my extended explanation of The Stock Market Crash of 1929 and the Beginning of the Great Depression. Some of the analysis and conclusions may surprise you.


  • Global Demographics and Economic Growth

    Global Demographics and Economic Growth

    1. Jakarta – 30 million people and sinking

    GLOBAL DEMOGRAPHICS

    Demographics, the study of the size and composition of population, will shape national and global economic growth and economic policy.  

    The period from 1950 to 2000 was highly unusual. The American “baby boom” started, temporarily reversing the long-term decline in birth rates.  Not just the United States but the global population experienced high birthrates and high population growth rates. In the middle of this period, partly due to more effective and more available birth control, birth rates began a rapid decline. The growth rate in world population began to fall. At the same time, much of the world’s population experienced rising standards of living. One consequence was longer life expectancies and rising average ages in industialized countries.  

    Countries with over a third of the world’s population and most of the world’s output now have birth rates below replacement. They are mostly the wealthy, industrialized countries, including the United States, Canada, Brazil, Western and Eastern Europe, Turkey, parts of Southeast Asia, Japan, Russia and China. Collectively, the size of their labor forces have stopped growing. All countries face the same challenges: Will they be able to invest in economic growth and development (innovation and structural change), deal with environmental costs and climate change effects, and support aging populations?  

    There are falling birthrates for most of the rest of the world’s population, coming down from very high levels. Mexico is at replacement and India is close to the replacement birthrate. But total population continues to grow, partly because of lower infant and child mortality rates, public health programs, better medicine, and subsequently longer lives in most of the world.  

    We are now in a period of a slowdown in total population growth rates. Global population is growing at about one percent per year and the rate continues to fall. But the increase in the number of people is large. In the most recent United Nations projection, the increase in global population from 2020 to 2050 is about 2 billion people, from 7.8 billion to 9.7 billion. The projected population increase over the following 50 years is lower, abour 1.2 billion. 

    Changes in total population may be points on an exponential decay curve. The UN projects that zero population growth will be achieved sometime shortly before 2100. The rate of decline could change with changes in the availability and cost of birth control, education of women, anti-aging medical technologies and more available health care for an aging population. (Estimates of future population are from June 17, 2019 UN projections. UN projections are revised about every two years.)

    The biggest unknown is future medical technology that will prolong life expectancies. Regardless of projection, the fastest growing age cohort is 65 years and over; within that cohort, the fastest growing age group is 80 years and older.

    Countries with birthrates well below replacement and aging populations may experience accelerating decreases in population. Family planning, combined with urbanization and more education of females, could lead to birth rates declining faster than projected in high birth-rate countries. In Africa, Ethiopia, Malawi and Rwanda promoted family planning and have seen large decreases in their birth rates. Kenya, after investing in family planning clinics and information, has seen its fertility rate fall from 6.5 in the late 1980s to 2.4, marginally above replacement and half the rate of most African countries.

    POOR COUNTRIES AND RICH COUNTRIES

    Wealthy countries have below replacement birth rates, no growth or declining populations and labor forces, low real economic growth, and aging populations and labor forces. Population will continue to concentrate in cities; the population of a small number of cities will be responsible for technological innovation and economic development. Rural areas will continue to lose population.

    Poor countries today have high but declining birth rates, young and increasing populations, and populations that want to emigrate (see case study below).

    Most of the largest and fastest growing urban areas in the world are in poor countries, China and India. Over half of the world’s population live in cities and the percent is rising. Almost all of the increased population in poor countries will live in or move to cities, which are already ecological disasters – traffic gridlock, poor air quality, lack of infrasturcture, sinking, raw sewage, and power outages. Many are coastal cities that are already experiencing periodic flooding and storm surges; rising sea levels and the increased number and severity of hurricanes will intensify urban problems. 

    Starting sometime in the 2050s, the world’s population outside of sub-Saharan Africa will stop growing and then slowly decline. All of the world’s net population growth will then be in Africa. How soon the world reaches zero population growth will depend critically on how fast birthrates decline in Africa.

    By 2100, Africa could have about as many people as Asia, about 4-5 billion. Together, Africa and Asia in 2100 could have about 80% of the world’s population.

    Throughout large parts of the Middle East, Africa and Latin America, governments have not been able to provide effective management of economic development for their young, growing population, which have high rates of unemployment and underemployment. Many of the governments are corrupt and/or repressive without free elections or civil liberties. Political activism, partly caused by stagnant or declining standards of living and lack of economic opportunity for young workers, commonly takes the form of mass protests and street demonstrations, aided by Internet social media. Governments typically react with riot police and the military, arrests, torture and prisons, rather than economic and political reform.

    THE DEMOGRAPHICS OF SPECIFIC REGIONS AND COUNTRIES

    A recent survey concludes that 46 countries have declining population or will have declining population in the near future. Declining population is already true in Japan (see below) and Russia and is about to be true in central and eastern Europe. South Korea, also with an extremely low birth rate, is looking at a demographic future similar to Japan’s (see below). South Korea’s current population of 51 million is expected to decline to about 30 million in 2100.

    Russia’s population is declining. Male life expectancies in Russia have been going down for decades but might have recently stabilized. While birthrates are below replacement, the decline of the national population has been offset in recent years by immigration. But lower rates of immigration in 2018 and 2019 have led to large decreases in population. The UN projection is that Russia’s current population of around 146 million will fall to about 85 million by the end of the century. 

    Because of very low birthrates and out-migration, central and eastern Europe is looking at population declines in this generation.  Some UN projections show that most countries in central and eastern Europe might have even larger total percent declines than Japan by the end of the century (over 50%).

    Western Europe is further along the population aging curve but because of immigration of younger people, the decline will not be as precipitous. And western Europe, like Japan, currently starts with more resources to support an aging population.  But high structural unemployment rates, low economic growth, restrictive labor laws and generous early retirement benefits will strain western Europe’s ability to grow and maintain current social welfare levels. A few European countries realize that current levels of social welfare are not sustainable and have begun reviews of retirement and health care programs. This problem is exacerbated by the currently high unemployment and underemployment rates among younger employees.

    China, which has enforced a “one-child” program since the 1970s until 2016, has a very low birthrate of about 1.6. Although this program has been relaxed in recent years, the national birthrate remains far below replacement. China currently has a young average-age population but the average age is rising very rapidly. 

    China’s working-age population began shrinking in 2012.  By around 2050, the decrease will be about the size of the current U.S. total labor force. Next year, the median (half above, half below) age in China will pass that of the United States. By around 2045, the percent of China’s population over the age of 65 will be about equal that of the United States. 

    A mature, experienced workforce should help maintain high but falling economic growth rates for another generation. After about 2050, demographics will begin working against Chinese economic growth. 

    China will grow old before it becomes rich (high per capita income). Even after decades of spectacular growth, per capita income is still about one-third to one-fourth that of South Korea and Japan. Even worse off are the economies of Southeast Asia, with per capita incomes below China, similar birthrates and rapidly aging populations.  

    Given current political strains and a large Chinese population outside of China, it is possible that China will have larger net outmigration in the future.

    DEMOGRAPHICS AND ECONOMIC GROWTH

    The following accounting identity shows the sources of economic growth. An accounting identity says nothing about causality, assumptions or feedbacks. But it introduces some general issues.

    The economic growth rate of a country roughly equals the growth rate of the labor force plus the increase in productivity (output per member of the labor force).

    If the labor force numbers are stable, all of the increase in output depends on the increase in productivity. The pressure on productivity is even greater if the labor force numbers are decreasing. So, for example, if a labor force is increasing at about 1% per year and productivity is increasing at about 1% per year, output will increase about 2% per year. If the workforce stops growing, productivity would have to double to 2% to yield the same economic growth. If the workforce were to decrease at 1% year, as it is in a number of countries already, productivity would have to increase 3% a year to achieve 2% economic growth. This is a high productivity growth rate for a developed economy.

    There is a small amount of research that suggests that an aging labor force is one cause of slowing productivity growth.

    Low rates of productivity growth with accelerating rates of labor force and population decline could lead to less output (negative growth rates) and declining standards of living.

    A member of the industrial/information workforce today is better educated, with new skills, compared to a member of the labor force a generation or two ago. The difference should show up in an increase in labor productivity. Increase in total factor productivity will be due to innovation in capital equipment – including information technology, robotics and artificial intelligence algorithms – and demand for employees with new skills and knowledge. Other factors are public investment and organizational innovation. But these changes have not shown up in productivity measurements. Productivity growth rates are low, although I suspect that the methodology used to compute these figures underestimates the gains.

    Demographics are heavily influencing the areas of investment in wealthy countries; these sectors will drive future economic growth. The three most active areas of research and net investment are robots and AI (reaction to declining workforce), driverless vehicles (same), and biotechnology (health care for an aging population).

    Demographics also influence the demand side of economies. The changing age structure of the economy influences the “market basket” of consumer spending. Certainly the large increase in the number of senior citizens (and their income) is having a major impact on health care spending. To say nothing about the increase in demand for tourism, gambling and south Florida real estate. (I once predicted that marijuana would be legalized when a large number of baby boomers became 65 and older.)

    An aging population is not necessarily bad for economic growth. A healthy population beyond retirement age is leading in the United States to an increasing percent of senior citizens remaining in the work force. With a rising percent of the population over 65 and living longer, health care is a growing percent of output. The health care sector is very innovative, which is a source of economic development and thus economic growth. 

    Companies use demographic information when planning marketing and advertising strategies. Changing demographics are analyzed when developing new products, changing product mix, and segmenting markets. The explosion of detailed demographic information about smaller and smaller segments, including individuals, combined with online marketing technology, is revolutionizing marketing and advertising.

    Areas of the world like Africa face the opposite problem. Working-age population will increase rapidly for a generation or two. But unemployment rates may be high and marginal productivity may be close to zero, or negative in rural areas. With high growth rates of population, economic growth rates will have to be high – over 6% per year – for a sustained period to raise real per capita income (standard of living) and reduce unemployment.  

    IMPLICATIONS FOR ECONOMIC POLICY

    The standard economic models demonstrate that the demographic changes we are seeing are a function of economic growth and development. Industrializing, better educated, urbanizing populations have declining birth rates. But the experience of the poorer regions of the world tends to indicate that these demographic changes are occurring even without economic growth and development.

    Although wealthier countries concentrate on the costs of their rapidly growing retired population, for most of the world the critical question over the next two generations will be how to accelerate economic growth to provide jobs and opportunity for the growing working age population.  The related challenge is how to improve education, training, and economic opportunity to raise standards of living now to provide the resources for the aging population in the future. 

    For the entire world, these objectives are complicated by how to pay for the social costs of past industrialization and environmental degradation, and the future costs of climate change.

    Increasing population and rising real income in emerging economies, especially in Asia, are increasing the demand for energy. China, which had no privately owned cars in 1979, is now the world’s largest automobile market. A dramatic increase in the number of cars is the main reason for the continuing increase in the global demand for oil.  Increased demand for electricity is being met largely with new power plants burning fossil fuels. For at least another generation, these trends will make it difficult to meet global goals to drastically slow down or stop global warming.

    Demographics is interacting with climate change in another important area – food production. Many scientists believe the most serious effect of climate change will be its impact on food production. Global warming and more extreme weather events will make it more difficult to expand food production using current technology. As in other areas, trend projections can be changed by the development of new techology.

    In the long run, the positive side of declining global population will probably be less demand for resources. Combined with substitute technology, global warming might slow down or stop. Climate change might not have quite the devastating effects trend projections indicate.

    The advanced and industrialized countries with stable or declining populations and workforces will have to consider the following:

    Economic growth will have to come from large increases in productivity (output per member of the workforce). To achieve this, and also meet social welfare costs, most countries and regions such as the European Union will have to make radical changes in economic policies. Particularly disruptive and contentious will be the adoption of automated factories and offices. On the positive side they will increase labor and total productivity; on the negative side they will probably eliminate or “deskill” a large number of existing and future jobs.

    Large increases in retirement age populations is leading to serious underfunding of public and private pension funds. Taxes to fund public pension funds are rising rapidly, both in amount and as percent of government budgets. Despite this, unfunded liabilities – promised future benefits not covered by projected future revenue from taxes – are also rising rapidly.

    Multinational corporations will develop and adopt the new technology. Countries that do not have quality education, encourage innovation and change economic incentives will not be able to attract investment and compete in the global economy. And their best educated and most motivated people may go somewhere else, as is happening in eastern Europe and many developing countries.

    On the other hand, poor countries with decent transportation, energy and communication infrastructure will probably attract foreign investment. Real wages of at least part of the labor force will rise.

    Attitudes towards immigration might change from the current restrictive policies of some countries. Attracting “human capital” will be just as important as attracting investment capital. Trans-border movement of people will increase. New national, regional and international agreements will have to be negotiated.  Remittances back to the home country will be a more important part of the economy of many countries and global capital flows. 

    Attitudes about work, labor laws, retirement and retirement ages will change. The benchmark age of 65 was arbitrarily set by Bismarck almost 150 years ago when less than one percent of the German population lived that long. When the United States adopted Social Security, life expectancy was 56 years. The life expectancy of America’s younger workers is already over 80 years.

    DEMOGRAPHICS AND PUBLIC ECONOMIC POLICIES

    If the labor force is not growing or actually shrinking, as it is in most industrialized economies, and the non-working population is growing, one consequence is likely to be growing government budget deficits. Growing government deficits as a percent of GDP may be a function of no economic growth or slow economic growth, not the other way around as suggested by economic research.

    It is how a government spends its income, more than the size of the deficit, that matters. Public investment substitutes for stagnant private consumption spending. Investment, both public and private, substitutes demand for innovation for demand for existing goods. This could increase productivity and result in new products and services. Economic growth then will depend on high levels of new technology and increased productivity (output per employee).

    JAPAN AS A POSSIBLE MODEL (OR WARNING) FOR INDUSTRIAL COUNTRIES

    Figures are from The Economist, “Japan’s economic troubles offer a glimpse of a sobering future,” December 5, 2019.

    Japan is a possible model for the future of other wealthy countries. Japan has a shrinking population and workforce. This will continue. It is not surprising Japan leads the world in developing and installing robots. Robots and AI are also alternatives to immigrants. Japanese companies export capital and technology. Facing falling population, Japan is slowly increasing the number of foreigners allowed into Japan on temporary work permits. But the number remains small, below 1%.

    Japan’s real GDP has been basically stagnant (about one percent per year) over the last 30 years. Without immigration and structural changes to Japan’s political and economic system, Japan’s real GDP in the future will grow slowly at best and eventually decline along with its population. In the long run, Japan will continue on its path to demographic and economic self-destruction.

    CONCLUSIONS

    Demographic trends have important consequences for economic growth and public policies. They cannot be seen in isolation. Neither can any of the other major trends. They are interrelated. 

    ·      Rising global population but at lower rates, mostly in poor countries, for the remainder of the century. After the 2050s, all of the world’s net population increase will occur in Africa. Global population may stop growing by the end of the century. 

    ·      Rising population in poor countries makes high rates of economic growth both pressing and difficult. Emigration pressure from poor regions of the world will probably increase unless there are high rates of economic growth.

    ·      Most of the world’s population increase will take place in cities and surrounding metropolitan areas, creating even larger massive urban areas. Large urban areas are increasing rapidly in poorer countries. 

    ·      Static, falling and aging populations in the wealthier, industrialized countries. Static or declining labor forces mean all economic growth will depend on increases in productivity. To counter demographic trends, technological innovation (robotics and software) leading to high rates of productivity growth will be necessary to increase standards of living (real income per person).

    ·      Problems with unemployment and underemployment, stagnant and declining real incomes and income inequality will probably get worse as artificial intelligence and robotics accelerates the substitution of capital for labor.

    Economic development and growth since the beginning of the Industrial Revolution has been aided by large increases in populations and especially the working age population. But in the future, economic development and growth in most of the world will have to occur with stagnant or declining labor forces and aging populations.

    =====================================================

  • “Pax Americana”:  The World That America Made

    “Pax Americana”: The World That America Made


    There are two kinds of empires: the kind that rules through ruthless exploitation, and the kind that seeks to induce allies into defending themselves through economic incentives. (George Friedman)


    INTRODUCTION


    America’s power and influence in the world rests on three broad, interrelated bases:


    1) Overwhelming military power that can be projected anywhere in the world,
     supplemented by security arrangements with allies and supporters.


    2) A large, innovative, dynamic domestic economy as the basis for global economic and technological leadership. The economy provides the resources and technology to support the military and a global foreign policy.


    3) Claims to moral and ideological leadership and influence, particularly the promotion of liberal democratic societies and supporting political institutions.

    This post will discuss the economic aspects and related security objectives of American foreign policy. It will focus on the structure of the global economy that America created after World War II, America’s trade treaties and policies, and the interaction of America’s foreign economic and political policies. It will analyze the current state of America’s projection of global power and influence through military power, security arrangements, and ideological and moral leadership and influence.


    The United States has been the primary force creating post-WWII economic institutions, global trade rules, and strategic alliances.

    Trade and strategic interests are intertwined.


    The coming decline of American leadership and influence in the world is due to the “critical state” of domestic and foreign trends. They have been building for a long time, at least since the collapse of the Soviet Union in 1991. They are converging to reduce American global power, credibility and influence. The post-World War II international structures that the United States created need reform. If unsuccessful,  internal pressures plus opposition from new groups of geopolitical and ideological rivals may bring the structures to an end.


    American voters decided in the presidential election of 2016 to elect a president who is disdainful of the global and regional institutions and treaties created by the United States after World War II. Mr. Trump signaled his beliefs by supporting the Brexit (or Leave) campaign in the United Kingdom and nationalist parties in Europe that want their countries to leave the European Union. These parties and leaders enjoy the support and encouragement of both President Trump and President Putin.


    President Trump has threatened and insulted the governments and policies of almost every American ally.  He has unilaterally threatened or invoked tariffs on allies’ exports to the U.S. President Trump questions whether America should be committed to NATO. He has questioned or denounced virtually every existing or pending trade treaty. He has mused about possibly leaving the World Trade Organization (WTO), the organization that oversees the rules of global trade. He has undermined America’s moral leadership by supporting authoritarian and anti-democratic political leaders, refusing to invoke American ideals as part of America’s foreign policy, and denouncing climate change and international attempts to combat it. 


    American foreign policy is retreating to protectionism and isolationism, a reduction in foreign commitments. This reflects a change in the psychology of a majority of the American people, who no longer believe that America benefits from being, or has an obligation to be, the world’s global power. 

    Many of President Trump’s threats are not credible or sustainable; they may not be carried out or reversed later. They are based on a simplistic world view that has long disappeared. But President Trump has the power – the economic and military might of the U.S. – to do damage. As a consequence, other countries are reviewing their national interests and adjusting to an international order where American power and credibility are diminished or uncertain.


    AMERICAN FOREIGN POLICY AFTER WORLD WAR II


    Since the end of the Second World War, the United States has led the global promotion of democracy, capitalism, and international economic cooperation. The projection of American force and influence was based on a desire not to repeat the perceived isolationist mistakes made after the First World War. 

    New military and economic alliances were formed within these frameworks to oppose Russian and Chinese Communism. Stated American ideals were often compromised in combating the spread of Communist influence. With the collapse of the Soviet Union and the economic opening of China to foriegn investment, many foreign policy-makers in the American government believed that America could return to the original post-WWII ideals.


    Right after WWII, the United States built a set of supranational institutions, starting with the United Nations. The economic institutions included the World Bank, the International Monetary Fund (IMF), global (GATT, later the World Trade Organization) and bilateral free trade agreements. Later, the United States would support the creation of the European Union and the North America version, NAFTA. The result of these policies were spectacular – extremely low tariff rates, fewer non-barriers to trade, global trade expanding twice as fast as global GDP, global mobility of capital, technology and labor. American allies adopted export-driven growth strategies, made possible by global markets and access to the large U.S. market.


    American military commitments were formalized in NATO, regional and bilateral military alliances (many on China’s periphery), military aid and foreign bases. Vast sums were spent on long-range projection of nuclear and conventional forces. Vital sea lanes were patrolled and controlled by the United States Navy. No foreign power could challenge the growth of international trade or the flow of raw materials to the industrialized and modernizing economies. Most foreign wars were fought on the periphery of the Eurasian continent in regions accessible by sea-based logistics and air power.


    The economic integration of the non-Communist world increased, the complement of the global military and foreign policy commitments of the United States and allies. Economic aid, trade treaties, access to the American market, and mutual security treaties were often intertwined.


    1989-1991 AND THE LACK OF REEVALUATION


    The overriding political objective was the containment and eventual collapse of Soviet Communism. To almost everyone’s surprise, it happened. After the breakup of the Soviet Union in 1991, global trade and economic treaties, the World Trade Organization (WTO), and regional trade groups like the European Union extended their economic objectives into new areas as many countries, including China, India, and former Communist countries in Central Europe, opened up their countries to foreign investment, joined the global economy, and promised to play by the free trade rules of the WTO and the European Union.  

    The global economy was created. It was increasingly dominated by huge global multinational corporations. made possible by the free trade economic framework created by the United States and Europe, and the encouragement of foreign corporate investment in China and other emerging countries. A massive amount of mergers and acquisition occurred, about $3 trillion a year, with little legal (anti-trust and anti-competitive rules) or political interference.

    These changes suggested that the regional and global economic institutions had a new economic roles to play in addition to reducing tariffs and non-tariff barriers to trade – establishing global standards for workers’ rights, pollution reduction, and protecting intellectual property; setting new and expanded rules for global competition among multinational corporations (MNCs); and mediating disputes between nation-states and multinational corporations. MNCs created new or sharper cross-border problems that needed new rules and regulations. Regional and global economic institutions were slow in recognizing the problems or attempting to deal with them, as was the United States. 


    Huge global multinational corporations were created, made possible by the free trade economic framework created by the United States and Europe, and the encouragement of foreign corporate investment in China and other emerging countries. As a result, multinational corporations (MNCs) now control most of the world’s economic resources, including advanced technology, and account for almost all of economic and technological innovation.


    POST-COLD WAR EUROPE AND NEW PROBLEMS 


    In Europe after 1991, American and European strategists saw the extension of post-war institutions to former Soviet satellites in Central Europe as the primary objective. Central European countries had to become democratic and capitalist to join the European Union and receive large infusions of aid and foreign investment. Besides economic growth, most of the new EU countries also joined NATO for protection against potential Russian expansionist policies and actions. As Putin consolidated power, he began to assert traditional Russian national interests in Central Europe. NATO, the European Union, and the United States found themselves once again opposing Russia but in a more complicated and fluid situation than during the Cold War/Iron Curtain period. 


    The long-range political strategy was the further economic and political integration of Western Europe, with the possible ultimate objective of a “United States of Europe.” A single currency and a European central bank were created. Some EU countries agreed to make labor mobility easier. But EU planners lost sight of the fundamental objective of promoting economic growth, now an end in itself and not a strategy of Cold War conflict or political integration.


    Economic growth in Europe was easier when Europe was recovering from the devastation of war and reconstruction was underwritten by American aid. Now, 60 years later since the beginning of European economic integration, recovery was complete in Western Europe and the economic challenges were more complicated. Europe, like Japan, now had to go beyond reconstruction and technological “catch-up.” To compete, Europe and its corporations had to compete on the technological frontiers to generate economic growth and employment.

    The large European “Common Market,” rather than fostering more cross-border competition, led to massive mergers and acquisitions to create European and global corporations. What was lacking were European startups and big company competitive innovation in the new industries that were driving economic growth. What was needed were radical reforms of traditional national and regional rules and behavior to promote economic growth and innovation. It did not happen. 


    Since 1991, Europe has experienced low economic growth, high structural unemployment, rising social welfare costs of an aging population, public debt rising faster than nominal GDP, and a relative lack of innovation. European output has substantially declined as a percent of global output. The dual nature of sovereign states and regional institutions is combining the worse of both – dysfunctional national governments along with a large EU bureaucracy that does not seem interested in promoting economic change. EU rules, the use of the euro and the power of the European Central Bank (ECB) led to rigid national monetary and fiscal policies that made internal adjustments more difficult. The promise of high rates of economic growth as a result of the free movement of products, services, capital, and labor was not fulfilled. 


    CONTINUING IDEOLOGICAL CONFLICT


    The collapse of Communism as an alternative did not mean the disappearance of opposition to liberal democracy, individual rights and private capitalism. Critical authoritarian regimes replaced Communist regimes in Russia and China. Traditional appeals to national interests and objectives replaced the universal ideology of Commmunism. Similar attacks of liberal democracy are occurring in Europe and in the United States. Democratic governments are widely perceived as incapable of dealing with the problems and challenges of a rapidly changing and uncertain world. Out of anger and frustration, voters are rejecting established parties and candidates. They are increasingly turning to candidates and parties that are critical of existing policies and the underlying political liberal democratic institutions and ideals that support them.


    Defending private capitalism in the greatly expanded global economy dominated by huge multinational corporations means defending the global economic order. But it also calls for continuing to reform the global economic rules as technology changes, as new transportation and communications technologies emerge, and as new “negative externalities” threatened the system. Regional and global trade treaties have to address not only barriers to trade such as tariffs and quotas, but also topics such as pollution, access to information, human rights, intellectual property, technology transfer, climate change, immigration and working conditions. If not, nationalist politicians will blame their domestic economic problems on the institutions and rules of the global economy. Continued economic integration and even global economic growth could be at risk.


    Support for democracy and human rights has been part of America’s influence around the world. But the American use of torture, widespread surveillance and wiretapping of American citizens, combined with President Trump’s threats to jail political opponents, support of torture, intimidation of the judiciary and the press, and demonizing ethnic groups, opponents and critics have all undermined American moral leadership. Even more damaging, President Trump has expressed admiration for authoritarian leaders who have challenged democracy at home and American ideals abroad.


    Political support for private capitalism has always been difficult. Private capitalism claim to legitimacy rests on its continuing success in raising people’s standard of living, not on a set of moral arguments. The private capitalist form of industrialization has been incredibly successful over the last 200 years but, at any given time, is open to criticism and attack. Those who do not benefit often seek political solutions, or scapegoats.


    THE UNITED STATES, EUROPE AND RUSSIA


    This is a review of the rapidly changing politics of Europe, and American responses.


    Europe in 2017 is very different than the Europe of 60 years ago, at the beginning of what became the European Union. The Europe of 1957 was still recovering from the devastation of World War II. The Europe of 2017 has a total GDP equal to that of the United States. The Europe of 1957 had living standards far below that of the United States. The Europe of 2017 contains many countries with living standards equal or above those of the United States.


    An increasing number of Europeans see the European Union (EU) and related institutions as the source of their problems. Besides low economic growth and high structural unemployment, Europeans blame the EU for allowing unwanted immigration (and terror); being a huge, unresponsive, undemocratic bureaucracy; the cause of a loss of national sovereignty and national identity; and contributing to, not solving, the social costs of economic change. They see the economic benefits of the European Union accruing mostly to large multinational corporations, their owners, managers, and well-educated employees. The Brexit vote – England leaving the EU – was partly a revolt against England’s political and economic elite.


    Right-wing governments friendly to Russia have been elected in Hungary and other Central European countries. Democracy is under attack in Poland and Turkey. Political parties that are openly hostile to the EU have formed the new government in Italy.


    Far-right parties, some with neo-Nazi roots, have been increasing their share of votes in almost every European country. Even if far-right parties do not win this round of elections, they will have increased support, a larger voice in national legislatures, and will put continuing pressure on center-right parties and national coalitions. New events such as terrorist attacks or a deep recession could increase anti-EU rhetoric, and the appeal of their messages.

    It is difficult to understand how EU leaders thought that bringing recently independent, former Communist countries with dependence on Russia for natural gas and oil would strengthen the European Union.


    Great Britain (1)


    While opposition to the EU has been building in Europe, it has been given a boost by the vote in Great Britain to leave the EU.


    Great Britain’s vote in 2016 to leave the EU encourages and accelerates the breakup of the European Union and possibly related organizations.  Mr. Trump supported the “Leave” position; President Obama supported the “Remain” position.


    The consequences could be serious, including the breakup of the United Kingdom. Scotland voted 62% to 38% to stay in the EU. The Prime Minister of Scotland has called for a referendum on Scottish independence from the United Kingdom. If Scotland leaves the UK, it takes the North Sea oil with it. Northern Ireland also voted to stay in the EU; this might give Catholics a non-ideological argument to reunite with Ireland.


    England’s remaining power and influence will be diminished. The English economy will suffer, with the greatest threat to the global financial sector in London. There will be no countervailing “special relationship” with a protectionist and isolationist U.S. president. 


    With England outside the EU and without an economic agreement with the EU, England’s preeminent position as the financial capital of Europe is at risk. 


    Germany


    During the presidential campaign, Mr. Trump called Hillary Clinton “America’s Angela Merkel” and Germany’s humane refugee policy “insane.” He singled out German automobile companies as a future target for increased tariffs. At the first meeting of President Trump and Chancellor Merkel, President Trump pointedly refused to shake her hand. President Trump has unnecessarily antagonized America’s most important ally on the European continent.


    Germany could be returning to Bismarck’s nightmare – being a large, isolated power in the center of Europe surrounded by enemies and with weak allies. The EU and NATO were established partly to guarantee that this would not happen.

    Germany is the largest and strongest economy in Europe. It exports about half of its GDP, primarily to EU countries and the United States. Germany has economic incentives to keep the EU together.  


    Given current political trends in Central European countries and subject to the results of the German election, it is unlikely that Germany will form a separate security alliance with Poland and the Baltic states in the near future. Germany and Poland have strong economic ties but fundamental and increasing bitter political differences that are weakening the European Union. Without the support and encouragement from the United States and Germany, Central European governments might be forced to be more accommodating to Russian demands.


    Russia and Mr. Trump’s Vocal Support for Vladimir Putin


    Combined with questioning America’s commitment to NATO and the EU, Mr. Trump’s praise of Mr. Putin encourages Mr. Putin to increase pressure on Central European and other countries on Russia’s periphery. Ukraine is a potential flashpoint. As Mr. Trump’s naïve admiration of Mr. Putin seems to encourage and support President Putin, Mr. Putin appeals to Russian nationalism and the illusion that Russia is a great power. As part of this these, Mr. Putin emphasizes foreign conspiracies, nationalism and xenophobia as political themes to bolster domestic political support. The historic Russian-German rivalry over the “borderlands” of Central Europe is again a possibility, with the United States currently playing an uncertain and often confusing role.


    As President Trump talks about American isolationism and “Fortress America,” Russian President Putin uses the old rhetoric of “spheres of influence.”


    NATO


    There has been no strategic reappraisal in the mission of NATO since the collapse of the Soviet Union in 1991. Believing Russia did not pose a military or political threat, European countries reduced military spending. Military preparedness, especially in Germany, deteriorated.  


    NATO never became an integrated regional or global military force. There was little European support for American wars in Afghanistan and Iraq. European forces (and their governments) were unwilling or incapable of even intervening in the conflicts that erupted from the breakup of Yugoslavia.


    A basic problem with NATO, as with all European institutions, is that sovereign nation-states have veto power over collective decisions. But unlike the other pan-European institutions, the United States dominated NATO, providing some cohesion to NATO’s strategy.


    The rise of nationalism, greater social welfare costs, and the weak fiscal condition of some European governments could make financing collective security less likely.


    European countries are much wealthier in 2017 than right after World War II but continue to rely on American nuclear and logistical support rather than building a European core in NATO. European defense spending as a percent of total GDP has been falling since 1991. This may be changing. Poland, the Baltic States and Germany have increased defense spending in response to increased Russian pressure.  


    Candidate Trump criticized the cost and questioned the usefulness of NATO.  President Trump may become more supportive of NATO if he is briefed on the new military reality. Russia is modernizing its conventional and nuclear forces. A particular threat to Europe is a new generation of intermediate-range cruise missiles with nuclear warheads. It remains to be seen how Europe and the United States respond to renewed Russian political pressure and military threats. Specifically, what role NATO will play in the future.


    Anticipating American force reduction or withdrawal from NATO, Germany and France have set up a small joint-planning operation outside of NATO, with plans to expand it in the future. Central European militaries have held joint discussions and military games outside of NATO. The new president of France has called for a European military force, apparently without American leadership or participation.


    Total European military spending is quite substantial, over $200 billion a year. Europe could be moving towards an alternative – no American oversight of NATO, a nationalist government in Germany controlling the strongest military force west of Russia, facing an expansionist Russia. This is not a scenario any sane American or European would like to see occur. Again.


    Strategic questions remain:


    ·      Will the U.S. continue to provide a nuclear umbrella over Europe if NATO collapses? 

    ·      What will happen to Ukraine and Central European countries?

    ·      What types of new defense alliances will be created in Europe, without the United States? 

    ·      What type of bilateral military arrangements will the United States have with the 28 countries in NATO? What bilateral commitments is the United States willing to make to Central European governments, especially Ukraine?

    ·      How will the United States respond to a rapidly modernizing Russian conventional and nuclear military force? “Fortress America” or greater involvement in NATO? Or both?


    EUROPEAN POLITICS


    The anti-EU and anti-immigrant movements represent the latest phase in the decline and collapse of the traditional post-war parties in Europe. Recent elections and polls in France show a rightward drift of the traditional center-right and conservative parties. More dramatic is the reduced support, almost collapse, of the center-left and socialist parties.


    Recent votes may represent a continuing, fundamental change in the structure of the underlying economies and their workforce. Political parties and movements seem to reflect less and less the traditional class interests of industrialized societies. The industrial working class, the basis of socialist parties, is a declining percent of the workforce. As the middle class loses income and security because of automation, artificial intelligence software and machines, and “deskilling”, new political parties and leaders may use new political rhetoric to blame multinational corporations and the technological elite. Hints of the new rhetoric can be seen in President Trump’s denouncing of both foreign and domestic multinationals for America’s economic problems.  

    Single-issue parties such as “green parties”; regional parties in Scotland, Wales, Catalonia and northern Italy; anti-EU parties; and anti-immigration parties are on the rise and threatening the established parties. It is hard to put these parties on a political spectrum. But collectively they seem to reflect increasing frustration and anger with the staus quo, partly caused by the inability to adjust to globalization. The immediate target is the European Union, its policies, and related pan-European institutions.


    The tension between national politics and economic growth can be seen in Poland. The Polish government is attempting to weaken internal checks and balances to its power, has challenged many of the policies of the EU, and has deteriorating and increasingly bitter relations with Germany. But German corporations are the largest foreign investors in Poland.


    EUROPE


    The extension of the euro beyond the economic core of EU has weakened the EU. The adoption of the euro and the European Central Bank eliminated many of the macroeconomic adjustment tools of national governments – exchange rate, fiscal policy, monetary policy, relative interest rates. Whether European economies could have grown any faster without these new institutions is unlikely. But pan-European institutions are conveniently blamed for low economic growth and periodic crises.


    Even if the post-war institutions survive, there is a question of how valuable European countries will be as American allies. Many of the countries are facing a stagnant workforce, stable or declining populations, rising social costs of aging populations, and probably unsustainable fiscal policies. Budget deficits creating rapidly rising public debt have papered over the necessity of making hard economic and political choices. No government would voluntarily go through what Greece has been forced to do over the last eight years.

    With low economic growth, competition for funds for social welfare costs and national defense approaches a zero-sum game. It is difficult to imagine electorates voting to support tax increases to pay for large increases in defense spending. Domestic problems plus increasing anti-EU sentiment implies less support for European institutions and cross-border defense commitments.


    ASIA:  The United States, China and Japan


    The United States and Japan


    Japan is a politically stagnant, rigid, rentier society with a declining population and the oldest population of any country. Since the collapse of asset values in the early 1990s, Japan has had very low economic growth, a stagnant and now declining workforce, no reform to a rigid political and social structure, and massive government deficits to support the status quo in place of economic and political reform. Japan has the highest public debt/GDP ratio of any industrialized country. The Japanese people vote for a conservative program of preserving their high standard of living and stable social structure for as long as possible. 


    Japanese multinationals have exported large amounts of capital and technology, especially to China. China has replaced the United States as Japan’s largest trading partner. Japanese multinationals have a huge investment in China.


    Japan has the resources, but apparently not the collective will, to project economic and military power in East Asia. This may change if Japan feels threatened by China or North Korea and does not believe it can rely on American military protection. Early indications of possible changes has been the government quietly ignoring the constitutional limit of 1% of GDP for military spending (imposed by the American occupation after WWII) and joint military and naval exercises with other Asian countries.


    The United States and China


    We are seeing the end of forty years of détente, partly aimed at Russia. Mr. Trump’s call to the president of Taiwan, and subsequent comments, early undermined the basis for American-Chinese détente. For forty years, American presidents have supported a “One China” policy. Chinese and American leaders have tacitly agreed not to discuss Taiwan. Mr. Trump’s phone call to the president of Taiwan, the leader of the Taiwanese independence party, reversed this agreement.


    This is the third rail issue in China. The phone call angered China. It came after the pro-Russian sentiments of President Trump and Trump’s threat of a trade war with China. Candidate and then President Trump has gone out of his way to antagonize China.


    Both countries believed in the past that Russia was the primary geopolitical threat, the basis for detente. The current American government believes China is the more serious threat. Combined with Mr. Trump blaming American job loss on Chinese exports and economic retaliation like high tariffs, and his praise of Russia’s president, China will accelerate its efforts to eliminate American influence in Asia and elsewhere. China may also conclude it is in their long-run interests to form stronger ties with Russia, although history and conflicting national strategic interests may work against it happening.


    Under Presidents Bush and Obama, the Trans-Pacific Partnership (TPP) was America’s main effort to counter rising Chinese influence in Asia. President Trump has walked away from the completed treaty. The other signatories to the treaty are proceeding without the United States. Countries in Asia and on the Eurasian continent, including American allies such as Japan and Australia, are signing up with the alternative, a multinational, Chinese-dominated investment bank. The Chinese government is also financing its massive “Belt and Road” initiatives, which have potentially serious geopolitical and military consequences for the United States.


    Unlike the provisions in TPP, trading with China and borrowing from China does not entail commitments to allow free trade unions, employee protection, environmental protection, observing intellectual property rights, or free access to information and the Internet. The United States will not be setting the future trade rules in Asia.


    If the Trump administration imposes greater trade restrictions and higher tariffs on Chinese exports, how could China retaliate?


    ·      Increased tariffs and trade restrictions on American exports to China

    ·      Devalue currency to offset higher cost of exports (already being done)

    ·      Pressure companies like Boeing to manufacture in China

    ·      Restrictions on American multinational corporations in China

    ·      Stop buying or start selling U.S. government debt, which will increase U.S. government interest expense and budget deficits

    ·      Step up political campaigns to oust American influence in East Asia and throughout the world


    China no longer needs increased exports to the United States to drive economic growth. Total Chinese exports (and imports) are a declining percent of the Chinese economy as the economy continues to grow through domestic consumption foreign investment, and government investment. 


    Most of the growth in Chinese exports over the last decade has come from exports to Asian countries. For most Asian countries, including Japan, China is now their largest trading partner and overseas market. Asian countries are more inclined to accommodate Chinese political interests.


    “Silk Road” projects and investments in Central Asia and other parts of Eurasia could lead to Chinese economic dominance over much of Eurasia. If China follows through with its ambitious plans to build high-speed railroads, roads, pipelines, and port networks across Eurasia, either through or around Russia, this will weaken the American potential threat to cut off imports to China through international shipping lanes and chokepoints like the Persian Gulf and the Strait of Malacca.


    The United States seems to be ignoring a strategic response to rising Chinese influence in Asia – closer ties with India. This would be part of a global strategy that recognizes the geopolitical reality of the increased importance of potential regional hegemons. The United States should reexamine its relationship with such countries as India, Turkey, Poland, and Iran. This would be part of adapting to the “post-American world.” (The title of a book by Fareed Zakaria)


    GEOPOLITICS AND THE GLOBAL ECONOMY


    The return of geopolitics – the primacy of national interests – is not surprising after colonial independence plus the breakup of the Soviet empire and Yugoslavia created over 100 new or newly independent nation-states. Historical greivances and ethnic antagonisms resurfaced. What is different is the huge growth in the global economy, increasingly dominated by multinational corporations.

    Surprisingly, most of the economic growth in the last 30 years has occurred outside of the established industrialized countries. Europe and Japan have exhibited low rates of economic growth. As workforce growth rates slow down (Europe) or stop (Japan), economic growth fueled by high levels of capital investment and a better-educated workforce should lead to high rates of labor productivity growth, about equal increases in real wages, and lower unemployment. But real wage growth is kept down by substituting labor-saving capital for labor (automation) and moving labor-intensive jobs to lower-wage countries. Instead, low rates of productivity growth combined with low rates of growth in the labor force have led to low rates of national economic growth. Two partial solutions to this problem – labor mobility in Europe and increased H1-B visa immigration in the United States – are under severe political attack. As a sign of the divergence of corporate and national political objective, large multinational corporations support both programs.

    The United States experiences better productivity growh and higher rates of economic growth. Some proposed reasons are a growing workforce, more efficient use of capital, more technological innovation, and more support and less opposition (until recently) to disruptive technological development. But real wages have been stagnant for much of the labor force. A major reason is that large American corporations have become multinationals, transferring much of their increased capital and technology to other countries as part of a corporate strategy to reduce costs and to obtain most of their growth in sales and profits overseas.

    So low rates of domestic (home country) economic growth do not limit the growth of multinational corporations, as they continue to expand geographically and grow faster than the economies and markets in developed and developing countries. Investors and managers of these corporations, along with supporting technological, financial and organizational experts, are experiencing rising real incomes. The remaining home market workforce is experiencing stagnant real incomes. The widening income inequality and insecurity fuel domestic political anger and reduces support and tax resources for domestic and multilateral economic adjustment programs. This also makes it more difficult to pay the social costs of an aging population and technological change without large budget deficits. Domestic support in the United States for traditional foreign policies and institutions is declining.


    Returning economic oversight power to nation-states and weakening supranational institutions will make it more difficult to deal with global problems such as global warming, pollution, drug trafficking, cyberwarfare, and terrorism. There were be less cross-border control over the behavior of multinational corporations. The bargaining power of multinational corporations will be strengthened when negotiating with individual nation-states. The conflicts between concentrated economic power in multinational corporations and democratic governments could become worse.


    CONCLUSION


    With nationalist feelings running high in Europe and America rejecting or criticizing the global economic institutions and security structures it created, America is on the verge of a loss of power and influence in the world.


    America’s allies in Europe and Japan have stagnant or declining populations, low rates of economic growth and development (innovation), high structural unemployment and deteriorating fiscal conditions. These economic problems, fueling political conflicts and social stress, are lessening the value of these countries as allies. It is unlikely they will substantially increase defense expenditures for collective security unless they feel threatened and can no longer count on American protection and support.


    With the American president criticizing allies and questioning support for supranational institutions created by the United States after World War II, allies are looking to their national interests without relying on the United States. There will be political realignments in Asia and Europe. South Korea is pursuing a policy towards North Korea at odds with America’s policies. Asian countries are increasing military and economic contacts among themselves.  China will become more aggressive in pursuing national interests in Asia and Eurasia. Russia may step up pressure on Central European countries.


    According to polls, a majority of Americans no longer supports free trade and the cost of America’s global commitments. It is uncertain, or even desirable, that countries like Germany or Japan want to or are able to fill the widening void.


    Threatening to increase tariffs on imports from China, Japan, Mexico, Canada, and Germany reverses 70 years of American foreign economic policy. Opposing trade treaties with Pacific Rim countries (TPP) means that China will now set regional trade policy in East Asia. Opposing a trade agreement with the European Union (TTIP) – not creating the world’s largest free trade zone – will weaken the strongest argument for the continued existence of the European Union.


    Even if the European Union ceases to have influence as a political institution, maybe the original “customs union” aspects of the EU would survive (no tariffs, quotas or other barriers to trade). This seems to be the basis of the Brexit negotiations. Other countries may consider a similar relationship with the European Union.


    Countries in Central Europe might not be able to look to the United States and NATO for security. For some time in the future, these countries will be dependent on Russia for natural gas. Unless Germany fills the political void (unlikely), security for these countries will be negotiated with Moscow.


    Some countries saw the “New World Order” as a vision of American global dominance, the triumph of one nationalism and its ideals. Movement towards a “United States of Europe” was stymied by national political and institutional rigidity and the nationalism of newly freed states. As time went by, the social costs of globalization and rapid economic change became political issues. Multinational corporations and supranational organizations like the EU and NAFTA were blamed for domestic problems. Rising nationalist political parties and their leaders call for increased national power and control.


    The democratic revolution and battle for individual rights begun over 200 years ago will continue but with less America’s moral, verbal and financial support. America’s “soft power,” which includes support for liberal democracy and human rights, will diminish every time President Trump praises Vladimir Putin or some other authoritarian politician.


    Less support for supranational organizations and rules and a return to nationalism will make it harder to deal with regional, continental and global problems until a new set of institutions are created.


    Multinational corporations have reached the inflection point where they will be truly global. They will be able to create dynamic comparative advantage anywhere because of the fluid international division of labor, based on the free movement of capital, information, and technology.  Corporate policies to increase sales and profits will come into increasing conflict with nation-states, their national economic policies, and their political agendas. How these conflicts play out will determine the next “New World Order.”


    America’s allies – Western European democracies and Japan – are increasing opposition to immigration. They resist political and social change that threatens a desire to preserve their existing societies and high standards of living.


    So far, the supranational institutions and treaties that were the foundations of the post-war world, the Pax Americana, could not deal with a new set of challenges or the resulting the anti-global nationalism of nation-states. The collapse of Soviet Communism in 1991 took away the main argument for support. American management of the global order has not been flexible enough or imaginative enough to create a compelling substitute. The consequence, a return to nationalism and nation-state rivalry, is occurring. Nations and political leaders will talk more about the country’s national interests and appeal to the ethnic and historical basis of the country’s special version of nationalism. This will probably continue until a series of crises, such as global warming or the loss of any control over their national economy, forces national political leaders to create new supranational organizations or new forms of cooperation.

    The United States has confronted a number of foreign threats to American security since the end of the Cold War – al-Qaeda, ISIS, Iran, Putin’s Russia, Xi’s China, and supposedly Hussein’s Iraq. Yet the most serious threat to America’s national security are current American policies, supported by a substantial percent of the American people. Alienating allies and supporters and attacking rather than reforming global economic institutions undermine the global order America created after World War II. Most Americans do not recognize that a global economy based on free trade and the free movement of economic resources is the new basis of America’s economic prosperity. Attacking the institutional structure of liberal democracy at home and refusing to promote American ideals abroad weakens America’s claims to moral and ideological leadership. In the end, only the foreign policies of the American government and the changing political beliefs of the American people can bring the Pax Americana to an end. 


    ==========================================================


    (1) For my immediate reaction to Great Britain leaving the EU, see“Breaking Away:  Britain and the European Union,”June 27, 2016. 


    =====================================================================


    See the related post:  “The Beginning of the End of “Pax Americana”:  America


    If you like history and speculative historical analogies, you might like the following two essays:

    The Roman Republic and America

    The Roman Republic Commits Suicide:  A Cautionary Tale for America

    For a list of all posts and economic tutorials in Pages, see Guide to Posts and Pages. The economic tutorials are equivalent to a course in economics.


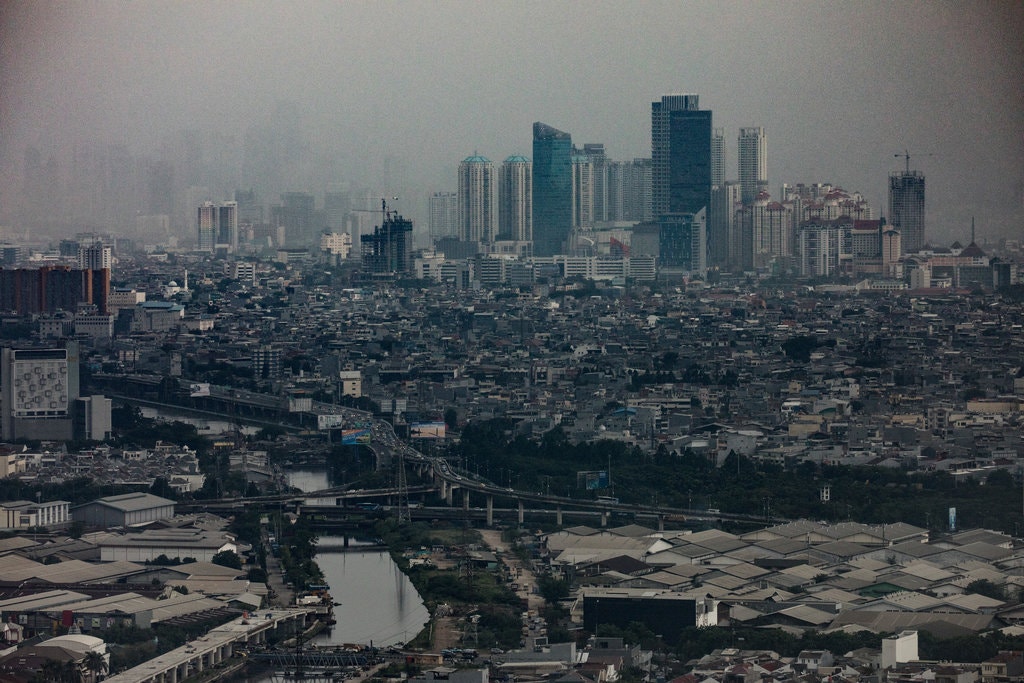
  • The World Turned Upside Down:  The Uselessness of Conventional Economic Wisdom

    The World Turned Upside Down: The Uselessness of Conventional Economic Wisdom

    There is a story, possibly true,
    that when the British surrendered to American and French forces at Yorktown,
    effectively ending British rule of America, someone in the British army sang or
    played an old English folk song, “The World Turned Upside Down.”   (See
    https://en.wikipedia.org/wiki/The_World_Turned_Upside_Down)

    I think I know how the British felt.  Many of the assumptions economists have made about
    economic reality and economic policies now seem out-of-date or even reversed.

    UNITED STATES

    The Fed fought inflation; now it
    sets inflation targets when there is no inflation.

    The Fed worries about deflation even
    though the major source is a fall in energy and commodity prices. Another source is the fall in the prices of technology products.

    There is a large increase in the money supply, large government deficits, a large trade deficit, and a large decrease in the unemployment rate. Economic theory and past experience says that there should be an increasing inflation rate. There isn’t.

    America is experiencing a long
    period of real economic growth without inflation.  Unemployment is as low as realistically
    possible.  Rather than rejoicing,
    economic, business and political commentators seem to believe there is
    something fundamentally wrong with this.

    Since the end of World War II, a key
    part of American foreign policy has been the expansion of free trade.  Now presidential candidates of both parties,
    and over half the American people, want to reverse free trade.  Economic nationalism is rising at the same
    time as large American corporations are about to receive over half their sales
    and profits from overseas operations.

    America worried about importing too
    much oil; now America is worried about producing too much oil.

    Interest rates are important because
    they are the price of capital, which determines how capital is allocated.  Now interest rates are a policy tool of the
    Fed.  They are artificially low with no
    thought about how they are affecting capital allocation.

    The stock market was a place where
    companies went to raise new capital. 
    Now, through massive share buybacks, it is a place where companies
    reduce equity capital.

    It has been government policy that
    annual budget deficits are manageable as long as the national debt-to-nominal
    GDP ratio was low.  That is, as long as
    the national debt rose at a lower rate than nominal GDP.  But since 2008, the national debt has risen
    much faster than nominal GDP.  We are
    experiencing historically high and rising peacetime national debt-to-GDP ratios.  So far, there has been little consequence
    because of historically low interest rates. 
    If nominal interest rates rise, there will be larger budget deficits. 

    Seven years into a recovery interest
    rates and inflation rates should be rising. 
    No one could conceive that central banks in the U.S., Europe, Japan and
    other countries would set zero short-term interest rates this far into the
    recovery.


    Negative interest rates, both real
    and nominal, were considered possible but not realistic.  Most industrialized countries have had some
    negative interest rates.

    The Fed stopped looking at the
    increase in the money supply as a policy tool about 30 years ago.  Now a huge increase in the money supply is
    being used to finance a huge increase in the national debt.

    Tax cuts and a larger deficit are traditional tools to fight a recession. They are being advocated as sound fiscal policy at the top of a business cycle.

    An economy can be in recession if
    private spending is too low (inadequate private aggregate demand).  This implies private saving is too high.  The solution is that government spending
    should be increased and/or taxes lowered. 
    The result is a larger government deficit, which is financed by private
    saving.  But with structural deficits at the
    national and state levels, private saving now has to be high to finance
    government deficits. Also, the United States has to continue to take in a high percent of cross-border financial flows.

    CHINA

    By some measures, using purchasing
    price parity (PPP) measurement, the Chinese economy is as big or possibly
    larger than the American economy. 
    (Although many analysts believe the past growth rates and the real
    economy of China are overstated.)

    China has over half of the world’s
    high-speed railroad trackage and intends to increase it by two-thirds over the
    next 10 years.  By 2025, China intends to
    have every city in China with a population of at least a half a million to be
    connected to the high-speed rail network. 
    The point?  China spends substantially
    more on infrastructure than the United States does, and China uses more
    advanced technology. 

    The U.S. high-speed rail
    mileage?  Zero.  Japan has offered to give the U.S. its
    high-speed rail technology.  I think
    that’s called foreign aid.

    China is planning a high-speed
    railroad that will take passengers and freight from Beijing to Moscow in 33
    hours and London in 48 hours.  Some
    sections of the railroad have already been built.  The geopolitical idea is to bypass American
    control of the world’s shipping lanes.

    China has four times as many
    skyscrapers as the United States.

    China has most of the long and high bridges in the world.

    China has more cars than the United
    States. China has more smartphones.

    China produces most of the world’s solar panels. On the other hand, China emits more carbon into the atmosphere than any other country.

    GLOBAL

    Recessions were caused by rising
    global commodity prices.  Now there is a
    fear that a global recession could be caused by falling commodity prices and
    their longer-term consequences.

    In the post-WWII period, there had
    never been a global recession.  Until
    2007-2009.

    At Japan’s current rate of economic growth, their economy will double in size in 100 years. But by then there will be very few, if any, Japanese.

    Almost all countries are experiencing rapidly rising national debt-to-nominal GDP ratios.  Economic history indicates bad things start to happen if the ratio goes over 90%. Many countries, including the U.S., are over 100%.  Japan has the highest ratio at 230%, a ratio no one thought could be possible without catastrophic economic consequences.   But this high and rising ratio is made possible because Japanese families are apparently willing to lend their government unlimited funds at zero interest.

    For decades we have been told that
    we are running out of oil.  Now we are
    told there is too much oil.  Proven reserves
    have been greatly increased and because of improving drilling technology oil
    can be extracted at lower and lower marginal and average cost.

    For four decades, Americans have
    been told that nuclear energy is bad and dangerous.  Now the world is planning on building
    hundreds of nuclear power plants using new technology. This is a major strategy to reduce global
    warming. But not in the United States.

    Electric engines in cars will reduce carbon emissions and slow global warming. Unless the electricity is generated by burning coal or other fossil fuels.

    The world faced a Malthusian future
    of exponential population growth caused by high birth rates, not enough food, and
    the depletion of energy and natural resources. 
    Since then, most of the world has birth rates below replacement and the
    rest of the world has falling birth rates. Industrial countries worry about
    future declining populations and labor forces. 
    Food production has undergone a series of technological revolutions that
    has greatly increased the quantity, if not the quality, of food.  Energy resources are almost unlimited with
    even more technological revolutions on the horizon.

    Since the 1950s, Americans have been
    hearing how other forms of political economy would overcome the U.S.  First 
    Russia, then Germany, then Japan, then
    the Four Dragons of Asia.
        Behind all these predictions was the description
    of the advantages of socialism or state capitalism over our relatively autonomous
    capitalism.
     Commentators suggested we
    adopt some of the government planning policies of these countries.
      We didn’t.  These countries and their economic systems
    turned out not to be a threat to us but they are a warning to China.

    MORE CONVENTIONAL WISDOM

    Red wine, dark chocolate, and beer
    were bad for your health.  Now they are
    health foods.  This is my idea of
    progress!