Tag: Management

  • Corporate Strategies: Basic Concepts and Management

    You need to know three things about management:

    80/20 Rule

    Opportunity Cost

    Compound Growth

    80/20 Rule (Also called Pareto’s Law)

    This idea says that a relatively small percent of actions account for a relatively large percent of outcomes. Find and concentrate your efforts on the important influences on your business.

    Some hypothetical examples.

    20% of your customers account for 80% of your sales.

    20% of your product line accounts for 80% of your sales and profits.

    Often, companies with a large product line with many variations find that 50% of their products account for over 90% of sales. An even smaller percent usually accounts for most of the profits.

    20% of your SKUs account for 80% of your stockouts (and lost sales).

    20% of your programmers account for 80% of the bugs in new programs.

    The percentages aren’t always 80/20. Some examples:

    McDonald’s accidentally learned that 10% of its customers accounted for 60% of its daytime sales. And it was an identifiable group that they had never aimed its massive advertising at.

    A landmark study by Arizona State University found that over the past century, just 4% of stocks have accounted for the entire net gain of the US stock market The other 96% were either flat, down, or so volatile they gave back everything they made.

    The possibilities are almost endless.

    The 80/20 rule implies:

    “Less is more” … reminds us that much of what we do, when closely analyzed, has negative value. Many activities, customers, products and suppliers actually subtract value, which helps to explain why their very positive counterparts produce such a high proportion of net value.

    Richard Koch, The Natural Laws of Business, 182-3.

    Eliminate losing products, customers, and functions. This might be happening because a competitor is more innovative or new companies have entered your markets.

    Look at divisions, regions or product lines that consistently have low sales growth rates and make below the minimum cost of capital. Reduce or eliminate these businesses. This frees up capital and resources to find and fund growth opportunities. Loser operations have a potentially high opportunity cost (see below).

    Look at positions or functions in the corporate structure that don’t add value to the company. Eliminate or outsource to the global economy supply network. This is a major strategy many companies are pursuing, which is why a high percent of job losses over the last three decades occurred because the position or function was eliminated internally.

    Better yet, avoid complexity in the first place. Concentrate on what you’re good at. Pound away at it. No complacency. Continuously innovate. And, with Andy Grove, be paranoid; your actual or potential competitors want to eat your company. His successors at Intel obviously didn’t read his book. They became complacent. A beast named Nvidia is devouring them.    

    Growth through mergers and acquisitions is a high-risk strategy with a high failure rate (loss or discounted return below the cost of the acquisition). The seller knows where they bad stuff is hidden; you don’t. (If you missed this in B-school, it’s called “asymmetric information.”) See the essay Corporate Strategies:  Mergers and Acquisitions.

    If you get into a bidding war with another company, walk away. The odds of “buyer’s remorse” are high. 

    Opportunity Cost

    After you’ve identified the critical opportunities and problems, opportunity cost is a good guide to deciding what to do about them. It reminds you that time and assets are limited and valuable. Time and assets you spend on one problem or function might be more profitably spent managing something else. For example, if you have a small customer who takes up a lot of your time, either raise prices, reduce service or stop supplying her. The opportunity cost is too high.

    Opportunity cost is a guide for better decision-making. Good managers think in terms of possible alternatives, not simple yes or no decisions on isolated proposals.

    What are the realistic options and alternatives (not a list from a management textbook)? Is there a less expensive (more profitable) way to do something? Lease or rent rather than own? Outsource some of your production?

    What is the net benefit (profit) over time of each alternative?

    Include risk as part of cost. If your company depends on inputs from China, it might be time to diversify your sources to other countries. Or seriously consider how you produce, assemble and distribute your output.

    In the extreme, some corporations have learned they are in the wrong business. They could have used their time and assets more profitably doing something else. A few retailers realized they were in the wrong business. They owned retail properties with a high opportunity cost. They became property developers. In cities across the country, manufacturing, office, and retail space is being turned into residential space. This has been a long-term trend in New York City.

    A word about accounting systems. Accounting systems are not set up to tell you which products or services are profitable. They are also poor indicators of return on capital or assets. Asset values should be adjusted from depreciated historical cost to present opportunity cost (often market value if sold or leased). The classic example is that Coca-Cola for decades carried the value of their brand name at $1 on their balance sheet. Really? See Corporate Strategies: Financial Management.

    Compound Growth

    (also known as exponential growth). 

    After you’ve freed up people and resources by applying the ideas of the 80/20 rule and opportunity cost, start looking for growth opportunities. By this time you will have a good idea what are the critical factors for your company’s success, the knowledge and resources that give you a competitive advantage. Develop opportunities that have a good chance for sustained high growth rates. Know the difference between unit sales growth rates (real growth) and dollar amount of sales growth (nominal growth). 

    In the beginning, new ventures often have low sales compared to the size of the company but high compound growth rates. If there continues to be high growth rates, these ventures can become large contributors to sales and profits in the future. Other good things can happen such as continuing reductions in unit costs (learning curves).

    These three tools work together.

    These ideas applied to starting a new business:

    Opportunity cost is a part of start-up costs.

    Loss of income from the job you quit.

    Loss of income from the saved money you invest.

    What are the critical factors for success?

    Look for sources of exponential growth and exponential reductions in unit costs as volume grows. This is especially true for new technology. A common term to describe this is “learning curve.”

    ALMOST EVERYTHING YOU NEED TO KNOW ON HOW TO MANAGE AN ORGANIZATION

    BEST BOOK ON HOW LARGE ORGANIZATIONS REALLY FUNCTION

    Joseph Heller, Catch 22.

    BEST BUSINESS MANAGEMENT BOOK

    Andy Grove, Only the Paranoid Survive. Andy Grove grew up in communist Hungary, escaped during the Hungarian Revolution, got his Ph.D. in solid-state physics at 22, and was CEO of Intel during its critical period developing and mass producing the integrated circuit (aka the microchip).

    BEST ADVICE ON STRATEGIC MANAGEMENT FOR A SMALL, DISRUPTIVE COMPANY

    “Hit ‘em where they ain’t.”

    “Wee Willie” Keeler

    One of the greatest hitters in baseball. Only one of 22 men ever to hit over .400 in a season. Also one of the smallest ever to play in the major leagues. Innovative. See biography in Wikipedia.

    “Get there the firstest with the mostest.”

    Nathan Bedford Forrest

    Surprisingly successful Confederate general in the Civil War. Consistently defeated larger Union armies. Not size but speed, surprise, and force at the point of attack led to victory. Same strategy used by Stonewall Jackson and Erwin Rommel against larger forces. One reason for the success of guerilla warfare.

    Good general advice but especially relevant if you are going up against a larger competitor with more resources. Hit them hard where they are weak. Toyota almost destroyed the huge and powerful General Motors by first attacking GM at its weakest point (compact cars).

    SOME MANAGEMENT ADVICE

    As a manager, be consistent.

    Subordinates will then know how to act and what to expect.

    If you are consistently nasty, expect to change jobs every two or three years.

    Business educators, consultants and commentators love sports analogies. But be careful. My favorite,

    Football (American) analogy. Be a pulling guard. You’re a pulling guard, not the quarterback (COO) or coach (CEO). Run interference for your people and protect them so they can concentrate on high value-added work.

    Hire good people (independent, flexible, adaptable, cooperative) and have confidence in them. Trust them. Don’t let HR or an AI algorithm filter resumes. 

    Never hire a graduate of Harvard Business School or anyone who has only been a consultant. They think they are qualified to run the business. Before they understand it.

    If your company’s management is hiring a lot of management consultants to tell everyone how to run their operations, you should probably update your resume and think about working for a better company. One that has confidence in you and its other employees.

    MANAGING UNDER UNCERTAINTY

    “Nell,” the Constable continued, “the difference between ignorant and educated people is that the latter know more facts. But that has nothing to do with whether they are stupid or intelligent. The difference between stupid and intelligent people – and this is true whether or not they are well-educated – is that intelligent people can handle subtlety. They are not baffled by ambiguous or even contradictory situations – in fact, they expect them and are apt to become suspicious when things seem overly straightforward.

    Neal Stephenson, The Diamond Age, 256.

    This is a key to success in the information age. Your phone can contain more facts than you can learn in a lifetime. AI can analyze more data in seconds than you can in a year. But algorithms hate ambiguity. Well, so far.

    Good managers are not afraid to make decisions in uncertain environments. I’ve worked for corporate and divisional managers who talked a good game but were scared to make decisions quickly because they were afraid they would be blamed or fired for a bad outcome. Afraid of the annual review. Stressed by the tyranny of the quarterly report. This is management by fear or blame. This is how Jack Welch and his picked successor ran General Electric into the ground. (BTW, read Greek tragedies. It’s a good way to spot arrogant people who will be destroyed by their own hubris. And destroy good companies.)

    Some decisions fail – lose money, not meet corporate cost of capital, not achieve a tactical or strategic goal. But good managers cut losses and change strategies quickly as they realize their assumptions were wrong or the actual outcome turned out to be different than expected. This takes courage. And humility. 

    A company’s managers don’t have to be right all the time – just more often than the competition. And adapt quicker to changing circumstances.

    George Washington lost every major battle he fought before 1781. But because of his failures, he changed his assumptions about the war and changed his strategy. A large Virginia planter accustomed to giving orders to slaves, he learned how to inspire his officers and men under terrible conditions. He persevered; he refused to accept defeat. His reward – he won his last battle (Yorktown) and won the war.

    These strategies will be applied in subsequent essays on different aspects of Corporate Strategies.

    Other essays in the Corporate Strategies series.

    Corporate Strategies:   Mergers and Acquisitions

    Corporate Strategies:  Marketing and Price Discrimination

    Corporate Strategies:  Organizational Change in the Future

  • The 10 Minute MBA – Almost Everything You Need to Know to Manage Organizations, People, and Yourself

    The 10 Minute MBA – Almost Everything You Need to Know to Manage Organizations, People, and Yourself


    Positive Externality


    You need to know three things about management and corporate finance:


    80/20 Rule

    Opportunity Cost

    Compound Growth


    80/20 Rule (Also called Pareto’s Law)


    This idea says that a relatively small percent of actions account for a relatively large percent of outcomes. Find and concentrate your efforts on the important influences on your business (and life).


    20% of your customers account for 80% of your sales.


    20% of your product line accounts for 80% of your sales and profits.


    Often, companies with a large product line with many variations find that 50% of their products account for over 90% of sales. An even smaller percent usually account for most of the profits.


    20% of your SKUs account for 80% of your stockouts (and lost sales).


    20% of your programmers account for 80% of the bugs in new programs.


    The percentages aren’t always 80/20. Some examples:


    McDonald’s accidentally learned that 10% of its customers accounted for 60% of its daytime sales. And it was an identifiable group that they had never aimed its massive advertising at.


    A landmark study by Arizona State University found that over the past century, just 4% of stocks have accounted for the entire net gain of the US stock market The other 96% were either flat, down, or so volatile they gave back everything they made.


    The possibilities are almost endless.


    The 80/20 rule implies:


    “Less is more” … reminds us that much of what we do, when closely analyzed, has negative value. Many activities, customers, products and suppliers actually subtract value, which helps to explain why their very positive counterparts produce such a high proportion of net value.


    Richard Koch, The Natural Laws of Business(182-3)


    Eliminate losing products, customers and functions. This is probably happening because a competitor is more innovative or new companies have entered your markets.


    Look at divisions, regions or product lines that consistently have low sales growth rates and make below the minimum cost of capital. Reduce or eliminate these businesses. This frees up capital and resources to find and fund growth opportunities. Loser operations have a potentially high opportunity cost (see below).


    Look at positions or functions in the corporate structure that don’t add value to the company. Eliminate or outsource. This is a major strategy many companies are now pursuing, which is why a high percent of job losses over the last three decades occurred because the position or function was eliminated.


    Better yet, avoid complexity in the first place. Concentrate on what you’re good at. Pound away at it. No complacency. Continuously innovate. And, with Andy Grove, be paranoid; your actual or potential competitors want to eat your company. (His successors at Intel obviously didn’t read his book. They became complacent. A beast named Nvidia is devouring them.)    


    Growth through mergers and acquisitions is a high-risk strategy with a high failure rate (loss or discounted return below the cost of the acquisition). The seller knows where they bad stuff is hidden; you don’t. (If you missed this in B-school, it’s called “asymmetric information.”) 


    If you get into a bidding war with another company, walk away. The odds of “buyer’s remorse” is high. 


    Opportunity Cost


    After you’ve identified the critical opportunities and problems, opportunity cost is a good guide to deciding what to do about them. It reminds you that time and assets are limited and valuable. Time and assets you spend on one problem or function might be more profitably spent managing something else. For example, if you have a small customer who takes up a lot of your time, either raise prices, reduce service or stop supplying her. The opportunity cost is too high.


    Opportunity cost is a guide for better decision-making. Good managers think in terms of possible alternatives, not simple yes or no decisions on isolated proposals.


    What are the realistic options and alternatives (not a list from a management textbook)? Is there a less expensive (more profitable) way to do something? Lease or rent rather than own? Outsource some of your production?


    What is the net benefit (profit) over time of each alternative?

    Include risk as part of cost. If your company depended on inputs from China, as soon as President Obama (and successors) focused on China as America’s number one geopolitical threat, it was time to diversify your sources to other countries.


    In the extreme, some corporations have learned they are in the wrong business. They could have used their time and assets more profitably doing something else.


    A word about accounting systems. Accounting systems are not set up to tell you which products or services are profitable. They are also poor indicators of return on capital or assets. Asset values should be adjusted from depreciated historical cost to present opportunity cost (often market value if sold or leased). The classic example is that Coca-Cola for decades carried the value of their brand name at $1 on their balance sheet. Really?


    Compound Growth (also known as exponential growth). 


    After you’ve freed up people and resources by applying the ideas of the 80/20 rule and opportunity cost, start looking for growth opportunities. By this time you will have a good idea what are the critical factors for your company’s success, the knowledge and resources that give you a competitive advantage. Develop opportunities that have a good chance for  sustained  high growth rates. Know the difference between unit sales growth rates and dollar amount of sales growth. 


    In the beginning, new ventures often have low sales compared to the size of the company but high compound growth rates. If there are high growth rates, these ventures can become large contributors to sales and profits in the future. Other good things can happen such as continuing reductions in unit costs.


    One application is personal investment. Compound growth rates are the first thing you need to know about finance, particularly personal investing. Earn income. Start saving early, save steadily over a long period of time, invest in high-quality bonds and dividend-paying stocks, and reinvest interest and dividends. Let compound interest (interest on principal and past interest) do its thing. Same advice for investing in stocks generally – start early, invest in index funds. Starting early is important because there will be periods when stock prices go down or stagnate. Spend all the time you save not analyzing or worrying about investments doing more pleasant and productive things (see opportunity cost).


    These three tools work together.


    These ideas applied to starting a new business:


    Opportunity cost is a part of start-up costs.

    Loss of income from the job you quit.

    Loss of income from the saved money you invest.

    What are the critical factors for success?

    Look for sources of exponential growth and exponential reductions in unit costs as volume grows.


    These ideas applied to personal life:


    Eliminate activities and people with high opportunity cost.

    Avoid high-maintenance (high opportunity cost) people (selfish, self-centered, demanding, whiny, long-winded). Life is too short.

    Concentrate on a small number of important people and activities who add meaning to your life.

    Remember the learning curve when starting something new.

    Persevere; learning something new is slow going at first but accelerates. (Again, concentrate on what’s important; 30% of the assigned reading in a textbook will account for 80% of the questions on the tests.)


    ALMOST EVERYTHING YOU NEED TO KNOW ON HOW TO MANAGE AN ORGANIZATION


    BEST BOOK ON HOW LARGE ORGANIZATIONS REALLY FUNCTION


    Joseph Heller, Catch 22.


    BEST BUSINESS MANAGEMENT BOOK


    Andy Grove, Only the Paranoid Survive. Andy Grove grew up in communist Hungary, escaped during the Hungarian Revolution, got his Ph.D. in solid-state physics at 22, and was CEO of Intel during its critical period developing and mass producing the integrated circuit (aka the microchip).


    BEST ADVICE ON STRATEGIC MANAGEMENT FOR A SMALL, DISRUPTIVE COMPANY


    “Hit ‘em where they ain’t.”

    “Wee Willie” Keeler


    One of the greatest hitters in baseball. Only one of 22 men ever to hit over .400 in a season. Also one of the smallest ever to play in the major leagues. Innovative. See biography in Wikipedia.


    “Get there the firstest with the mostest.”

    Nathan Bedford Forrest


    Surprisingly successful Confederate general in the Civil War. Consistently defeated larger Union armies. Not size but speed, surprise and force at the point of attack leads to victory. Same strategy used by Stonewall Jackson and Erwin Rommel against larger forces. Reason for success of guerilla warfare.


    Good general advice but especially relevant if you are going up against a larger competitor with more resources. Hit them hard where they are weak. Toyota almost destroyed the huge and powerful General Motors by first attacking GM at its weakest point (compact cars).


    ALMOST EVERYTHING YOU NEED TO KNOW ON HOW TO MANAGE PEOPLE


    Be consistent.

    Subordinates will then know how to act and what to expect.

    If you are consistently nasty, expect to change jobs every two or three years.


    Business educators, consultants and commentators love sports analogies. But be careful. My favorite.


    Football (American) analogy. Be a pulling guard. You’re a pulling guard, not the quarterback (COO) or coach (CEO). Run interference for your people so they can concentrate on high value-added work.

    Hire good people (independent, flexible, adaptable, cooperative) and have confidence in them. Trust them.


    Never hire a graduate of Harvard Business School or anyone who has only been a consultant. They think they are qualified to run the business. Before they understand it.


    If your company’s management is hiring a lot of management consultants to tell everyone how to run their operations, you should probably update your resume and think about working for a better company. One that has confidence in its employees.


    MANAGING UNDER UNCERTAINTY


    “Nell,” the Constable continued, “the difference between ignorant and educated people is that the latter know more facts. But that has nothing to do with whether they are stupid or intelligent. The difference between stupid and intelligent people – and this is true whether or not they are well-educated – is that intelligent people can handle subtlety. They are not baffled by ambiguous or even contradictory situations – in fact, they expect them and are apt to become suspicious when things seem overly straightforward.


    Neal Stephenson, The Diamond Age, 256.


    This is a key to success in the information age. Your phone can contain more facts than you can learn in a lifetime. It can analyze more data in seconds than you can in a year. But algorithms hate ambiguity. Well, so far.


    Good managers are not afraid to make decisions in uncertain environments. I’ve worked for corporate and divisional managers who talked a good game but were scared to make decisions quickly because they were afraid they would be blamed or fired for a bad outcome. Afraid of the annual review. Stressed by the tyranny of the quarterly report. This is management by fear or blame. This is how Jack Welch and his picked successor ran General Electric into the ground. (BTW, read Greek tragedies. It’s a good way to spot arrogant people who will be destroyed by their own hubris.)


    When the CEO is like this, the company is doomed to mediocrity. Or worse. Update your resume.


    Some decisions fail – lose money, not meet corporate cost of capital, not achieve a tactical or strategic goal. But good managers cut losses and change strategies quickly as they realize their assumptions were wrong or the actual outcome turned out to be different than expected. This takes courage. And humility. 


    A company’s managers don’t have to be right all the time – just more often than the competition. And adapt quicker to changing circumstances.


    George Washington lost every major battle he fought before 1781. But because of his failures, he changed his assumptions about the war and changed his strategy. He inspired his officers and men under terrible conditions. He persevered; he refused to accept defeat. His reward – he won his last battle (Yorktown) and won the war.


    LEADERS AND MANAGERS – KNOW THYSELF


    Are you a leader or a manager? 


    A leader has strategic vision.

    A manager has functional expertise.


    A leader looks outward.

    A manager looks inward.


    A leader thinks abstractly.

    A manager thinks concretely.


    A leader anticipates.

    A manager reacts.


    A leader is able to make decisions in an uncertain environment.

    A manager attempts to reduce uncertainty to routines.


    A leader thinks and worries about the future.

    A manager thinks and worries about the present.


    A leader indicates a general direction for the company.

    A manager wants specific instructions to carry out a function.


    A leader is paranoid and insecure.

    A manager seeks security and certainty.


    A leader thinks in terms of trade-offs and possible scenarios.

    A manager wants to find the one best way to optimize performance.


    A leader is not guided by financial data and short-term financial objectives.

    A manager is directed by her budget.


    A leader thinks strategically in a hostile, competitive environment.

    A manager is concerned with operational efficiency.


    A leader can make decisions in an environment of accelerating change and
          discontinuities.

    A manager can’t.


    A leader sees potential opportunities in an age of radical change.

    A manager sees problems to be dealt with.


    A leader persuades.

    A manager commands.


    A leader adapts, improvises, overcomes obstacles.  (From Heartbreak Ridge)

    A manager waits for explicit instructions.


    A leader looks for talent.

    A manager looks for skills and experience.


    A leader trusts other people.

    A manager controls other people.


    A leader discovers, nurtures and promotes potential leaders inside the company.

    A manager doesn’t.


    A leader reads books and articles about history, the global economy, other cultures and values, new ideas like complexity theory and tipping points, biotech, and science fiction.

    A manager reads books and articles about management and her functional
           specialty.


    A leader reads The Economist.

    A manager reads The Harvard Business Review.


    If you see yourself as a manager, join a large organization. But be warned; you are in danger of having your position eliminated by AI.

    If you see yourself as a leader, think seriously about starting your own company.

    Published 1/23/2019.

    Last updated 8/17/2025.

    There are posts on American History, American Economic History, demographics, and much more. Some essays on information, innovation, and how markets work. Even some essays on business, finance and economics.

  • Alan Turing, Computers, and Strategic Management

    Alan Turing, Computers, and Strategic Management

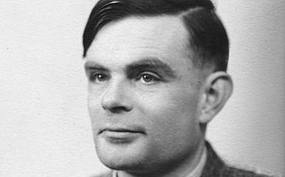
    Alan Turing


    Alan Turing developed many of the basic concepts for digital computers in the 1930s. His ideas were promoted by John von Neumann.
     In 1943, he came to the United States to exchange ideas and experiences with scientists and engineers at Bell Labs. He spent a great deal of time talking with Claude Shannon, the father of modern information theory, about their mutual interest in digital computers. 

    One day while having lunch in an AT&T executive dining room, Turing was describing his ideas about what a “thinking machine” could do.

    “His high-pitched voice already stood out above the general murmur of the well-behaved junior executives grooming themselves for promotion within the Bell corporation. Then he was suddenly heard to say: ‘No, I’m not interested in developing a powerful brain. All I’m after is just a mediocre brain, something like the President of the American Telephone and Telegraph Company.’”

    Andrew Hodges, Alan Turing: An Enigma, 251.

    Given the abysmal record of AT&T top management since the divestiture in 1984, even a mediocre brain, human or computer, would have been an improvement.

    I don’t believe that large corporations in a global, rapidly-changing competitive environment can be managed in any meaningful way by humans. Failure rates are high, mediocre financial performance common. Integrated planning systems like those from SAP and Oracle are an intermediate step towards computer-based strategic management. This is an area of application for artificial intelligence (AI).

    Strategic management might be based on computer simulations of different sets of short-run and long-run strategies. In an uncertain, often discontinuous external environment and with strategies interrelated in complicated ways, operational and financial outcomes are often highly uncertain. Computer simulations that could capture some of this complexity would be an improvement over current planning methods.

    At a minimum, companies will be able to react faster to unexpected change and have a better idea of the financial consequences of changing different sets of strategies. This would be a source of competitive advantage.

    Computer simulations compared to human top management strategists have the advantage of continuity. Managers come and go, often with large gaps in specific knowledge and implementing disruptive changes in strategy based on personal past experience. In contrast, computer simulations of an organization embody continuous knowledge and experience. As assumptions and forecasts are replaced by actual data, strategies can be revised in intervals closer to real time.

    Simulations can also learn over long periods of time, even suggesting new strategies and probably chances of success.  A few companies are already using algorithms based on concepts from chaos and complexity theory to forecast and plan. Neural net models hold out the possibility that computer programs will be able to choose among competing strategies.

    The drawback will be that simulations will, to some extent, be “black boxes” to human managers, producing unexpected results in unknowable ways. This will change the training and mentality of managers.

    ==================================================================

    For an essay on John von Neumann, see


    John von Neumann Sees the Future

    For all the posts (with links) on this blog, see

    List of Posts by Topics

    There are posts on: 

    American History and American Economic History.

    Information, innovation, and how markets work. 

    Business, finance and economics. 

    Also a series of essays on demographics, population projections, and speculations on how decreasing and aging populations will interact with the economies of individual countries and the global economy. 

    Essays on a variety of historical topics, including the Industrial Revolution, India and the English East India Company, Rome, and Europe in the World War I period.


  • Corporate Strategies:  Organizational Change in the Future

    Corporate Strategies: Organizational Change in the Future


    William Gibson: Neuromancer


    (I wrote this in 2008 as a memo in response to an adult
    student’s question about what I thought of the book Fifth Discipline.  While
    still somewhat unrealistic – organizations are still run by managers who lack
    the self-confidence to ask others for advice and ideas – I think the current
    trends of quicker reaction to change, recognition of “high value-added
    employees,” and more sophisticated IT software are moving organizations in
    this direction. At least the good ones.)


    I’m glad you read Fifth
    Discipline
    , even though it’s rather dense. 
    Many of the ideas in the book are now the starting points for a lot of
    writing on management. 


    I believe that the best way for organizations to achieve
    superior performance and survive in the long run is to be adaptive, to be a
    “learning organization.”  This
    means that everyone in the organization is encouraged (and rewarded) to come up
    with new ideas and methods.  These new
    ideas are then implemented and propagated throughout the company, the key goal
    of organizational design.  Discussion
    often leads to other new ideas, leading to “tipping points” of
    fundamental change.  One method to change
    mentalities and transmission channels in a large organization is your
    experience – a specific project that brings together people from different departments
    or functional specialties.  Another is
    new software to share new ideas and knowledge throughout the company.


    You recognized that your experiences were very different
    than your day-to-day experience and opened up new possibilities.  What you implied was that you and the other
    members of the group were using their intelligence and skills collectively to
    solve complicated and important tasks, far beyond what was required in your
    daily jobs.  To me, good companies have
    institutionalized this idea – that everyone in the company can contribute to
    improving the competitive position of the company today and help the company
    adapt to rapid change (or create the change).


    I suspect that in successful companies in the future
    everyone in the company will be a “manager.”  You already have more education and general
    knowledge than the average manager of two generations ago.  Organizational hierarchies won’t mean very
    much; they won’t reflect where new ideas come from or how they are
    implemented.  Possibly, this is why so
    many management positions are being eliminated; the old control, command and
    coordinate systems just don’t work any more. 
    Many of the repetitive supervisory functions of management will be done
    by software.


    Ideally, top management’s role is the strategic interface
    between the external environment and the company.  They ask, “What is it we are doing”
    and “What should we be doing?” 
    This is sometime called “vision.”  They convey a general sense of direction and,
    when necessary, change of direction.  But
    they should leave it to the other employees to figure out how to get there.  Surprisingly, the U.S. Marines are
    incorporating this kind of thinking in their training of junior officers and
    tactical combat units.


    Paradoxically, I think that fairly continuous structure and
    general direction are important as a framework within which to execute change.  Successful organizations will find the right
    mix of continuity and change.  This might
    mean there should not be rapid turnover in top managers who rely on their experience
    in other organizations or industries.  Clear
    objectives; general, flexible strategies; and very flexible tactics relying on
    well-informed, empowered, cooperative and innovative employees.


    One speculative comment. 
    I was thinking about hospitals. 
    My guess is that the revolution in the delivery of new medical services
    will radically change what hospitals do. 
    In fact, I don’t believe that hospitals in their current form or
    function will exist in 30 years.  Already
    most testing such as MRIs and endoscopies are now done outside of
    hospitals.  There will be far less
    surgery, which will be viewed as a barbaric relic. Non-invasive genetic surgery
    will be done in specialized clinics on an out-patient basis, like eye
    laser-surgery is done now.  Drug-based
    cures will be delivered in a very decentralized industry, possibly even more in
    the home with remote monitoring.  All of
    this will be far less expensive than the incredibly inefficient and expensive
    current health care “system.” 
    Forget about the “health care crisis” of the future. 


    OK, another speculative comment. Even more revolutionary
    will be the delivery of “education.” 
    Schools are based on assumptions about how we learn and ancient
    “technology” that will be obsolete in a few decades.  It’s amazing what scientists, even using such
    “primitive” tools as MRIs, are learning about how the brain
    functions.  Most “learning”
    might be some form of direct absorption of visual images.  How this will be done might seem a little
    scary now but will probably occur because of the economics of it – cheaper,
    quicker, more efficient.  Students will
    proceed at different speeds.  Software
    will include more effective feedback mechanisms.  Testing will be continuous and used to
    accelerate learning, not determine grades. 
    Teachers will tutor, suggest additional work and supervise progress.   And I
    will probably be unemployed, which has always been my goal.

  • Limits to Strategic Planning


    Strategic and Tactical Planning


    For thirteen years, I was a corporate economist and a
    corporate planner manager for three Fortune 500 companies.  I discovered that I could do my job as a
    corporate economist while ignoring all but the simplest of economic
    concepts. As a corporate planner, I
    learned that the planning processes of large corporations were, at best, mostly
    a waste of time and resources, and at worst, contributed to the relative demise
    of the companies. Of the three companies
    I worked for, one has been sold three times, one has gone through a bankruptcy,
    and the other merged with (actually sold to) A Brazilian company.  This is becoming typical; the failure rate of
    large corporations is accelerating.


    Other disciplines in business are no better.  Marketing is still based on ideas, usually
    summarized by the four P’s, that are a formula for stagnation at best and
    decline at worst.  Mass-media
    advertising, born at the beginning of a rapid growth in consumer affluence and network
    TV as a novel medium to mass-market branded products, doesn’t work any
    more.  There are vastly more products,
    markets are fragmented and we hit the mute button when the ads come on.  Cable and the Internet are the new advertising
    and marketing tools. Advertising on the Internet is dominated by the social media and search companies Google and Meta. Think of one TV ad
    campaign that actually convinced you to change products.


    What about financial planning?  Financial control was a brilliant innovation
    80-90 years ago, with its full potential realized by General Motors in the
    1920s.  It made possible the huge,
    multi-division corporations of today. 
    Although operations were “decentralized” into division, corporate
    control was strengthened through the financial controls of budgeting and
    allocation of investment funds.


    Financial planning and control often has a negative effect
    on corporate performance as the budgeting and planning numbers have taken on a
    life of their own.  “Hitting the numbers”
    has had a chilling effect on innovation and risk-taking.  Executive bonuses and the value of their
    stock options are tied to short-term profit increases. The system invites
    acquisitions and cost cutting (massive lay-offs, less investment and
    outsourcing) as major strategies. Manipulating the accounting system has become an important business
    skill.  At worse, it gives us Enron and
    massive fraud in the entire financial system.


    Almost all studies show that drastic cost cutting by firing
    large numbers of employees does not increase profits (rates of return) after
    two years.  


    Acquisitions, despite
    reducing duplication and head counts, seldom make a minimum rate of return. For two reasons – asymmetric information (sellers know more than buyers) and buyers remorse (bidding competition of very 
    competitive corporate executives). The result is optimistic assumptions about future growth in sales and profits or ignoring discounted rates of return analysis when bidding. Buyers pay too much to make an acceptable return on investment.


    Think of all the business fads of the last few decades.  Total quality management.  Reengineering.  Matrix or decentralized decision-making
    organizational structures.  Benchmarking.  Six Sigma. 
    Many of them are still in management and organizational development
    textbooks.


    As a manager, how can you make good decisions if you do not
    understand the economic environment, consumer motivation, how to reach and
    influence consumers, distrust the numbers but work under the tyranny of the
    budget, are worried about the next “down-sizing,” and have to adapt to the
    consultants’ “fad of the month?”


    But what about new ways to manage?  What about Mission Statements and strategic
    visions? What about Project Management and cross-functional teams,
    “intrapreneurs,” process change, Black Belt Swat teams that swoop in and
    quickly solve problems? 
    What about the belief that software like SAP will solve your company’s problems? What about the
    most advanced advice from consulting firms? If corporate managers feel they must call in management consulting firms like McKinsey to tell them how to manage, then the board of directors should fire the managers.  


    The Reality


    With all these ideas on how to improve corporate
    performance, why are so many big corporations in deep trouble?  Leave aside the dotcoms.  Leave aside the criminal conspiracies
    disguised as corporations, their accountants, their lawyers and their
    investment bankers.  Think about the
    cutting-edge companies of 30 years ago, the ones that were praised in books
    like In Search of Excellence. 
    What happened to IBM, Xerox, Polaroid, K-Mart, Digital Equipment and the
    other companies that have since disappeared? 
    Even many of the pharmaceuticals no longer make a superior rate of
    return and continuing to merge.  To some
    extent, they have become the venture capital and marketing arms of small
    biotechnology companies.


    In the 1980s and the early 1990s, everyone studied Japanese
    management to try to figure out how to emulate the success of Japanese
    companies.  Actually, it turned out, only
    a very small number of Japanese companies were successful or world-class.  The rest of the economy was very inefficient,
    the political system corrupt and bureaucratic, and small, innovative companies
    could not get financing or even be allowed to compete against entrenched large
    companies.  The result – starting in 1991, 30 years of economic stagnation.  Even
    the great consumer electronics companies are firing employees and merging
    operations, two strategies that would have been unthinkable 10 years ago.  When was the last time anyone pointed to Toshiba or Sony
    as a corporate model?


    How can a company have Project Management teams,
    decentralized decision-making and encourage risk taking when their main
    strategy is firing employees, particularly middle managers, and outsourcing?  If there is no loyalty or trust on either
    side, no strategy will work.  The
    corporation, more than the economy, becomes a Darwinian jungle, not a means to
    coordinate activity towards a common goal. 


    What is extraordinary about the capitalist system is how
    vulnerable huge, market-dominant companies are and how fast they are wounded or
    killed by new, small, innovative companies. 
    Innovating new technology and developing new industries are usually done
    by new companies, with a disproportionate percent of them founded by
    immigrants, members of minority groups, and social outsiders. 


    But that’s not the whole story.  Pickles are at least three thousand years old
    (the Egyptians made them).  How could
    Heinz, who dominated the pickle market for decades, get clobbered within 10
    years by a new company called Vlasic, headed by a family that never made a pickle
    until they started the company?  There
    are no secrets to making ice cream (the Romans made it); yet a couple of
    ex-hippies in Vermont made the largest dairy products and ice cream company in
    America look sluggish and stupid?  In a
    declining market dominated by two huge companies – coffee – a Seattle company
    called Starbucks reinvented the basis for competition and turned coffee into a
    growth industry.  No industry was more
    moribund or boring that the sneaker industry but Nike turned it into both a
    growth industry and a fashion industry.  When Fred Smith wrote a paper at Yale Management School outlining the future FedEx, his business prof gave him a C and advised him to forget the idea. Every college business department in America looked to Harvard or
    Wharton as the model but an entirely different approach by a for-profit company
    called University of Phoenix has revolutionized professional education at the
    college level.


    Strategic Planning – Good and Bad


    So what is good about
    strategic planning?  I see the following
    benefits:


    Corporate and divisional management must make their
    assumptions about the competitive environment explicit. It is then possible to change strategies if
    something important in the competitive environment changes.


    It lengthens the planning horizons of operational managers,
    unless quarterly financial goals become the main focus. It introduces long-run trends into
    operational planning.


    It encourages corporate management to develop a strategic
    vision, which includes what the corporation is comparatively good at doing and
    what it is not.


    This helps define what businesses
    or markets the company should be in and which ones it shouldn’t be in.


    It makes explicit the division of capital resources between
    operational efficiency and strategic investments in new products and new
    markets.


    It introduces and attempts to analyze potential sources of
    risk to the business and suggests how to adapt to unexpected change.


    What is bad about strategic
    planning?


    It often degenerates into financial objectives, encouraging
    behavior that increases the risks of long-run failure of the company.


    It concentrates on operational efficiency and marginal improvements
    in the current business as the expense of thinking and funding strategic
    investments.


    Goals are set and resources allocated mostly based on the
    relative power of top managers.


    Yearly planning schedules are too rigid and too slow to react to
    major changes in the competitive environment. Large amounts of real-time or almost real-time data and analysis are now available to make operational decision.


    I believe that a company should not establish long-run
    financial objectives.  The long-run
    financial performance should be the result of business decisions, not financial
    pressure.  The time saved from setting
    long-run financial goals could be spent analyzing the competitive environment
    and devising “what-if” strategies for different possible scenarios.


    I believe that radically new analytical tools and models that study nonlinear dynamic systems will be more useful than planning systems based on current economic and financial models. 


    Your Future and Strategic Planning


    You will probably end up working for a mediocre
    company.  Most companies, especially large
    ones, grow along with the economy.  Most
    of what the company does, and most of what you do, will be fairly routine.   Even small changes will meet resistance and
    be difficult to make, unless there is a crisis. 
    The company will make small changes to its products and product lines,
    increase its advertising on TV and in magazines or switch some advertising to Google, try to cut costs by moving
    production, assembly and software programming to lower-wage countries, and put
    increasing pressure on its managers and employees to produce results faster
    with fewer resources. You will be
    insecure and stressed. Top management
    will make speeches about the need for radical change but will have golden
    parachutes if they mess up. They will avoid major risks.  Middle managers will oppose almost all
    attempts at change, fearing loss of power and possibly employment. Acquisitions will be made for financial
    reasons, often followed by massive lay-offs, power struggles and organizational
    chaos. Your main competitors will be
    multinational corporations but small innovative companies below your company’s competitive
    surveillance radar screen will do the most damage. Welcome to the future.


    You have four choices – start your own company (highly
    risky), go to work for a start-up that could be the next big thing (risky),
    join a nunnery or monastery (the best choice), or become a better employee and
    manager with new transferable skills. Update your resume and join LinkedIn. 
    Cultivate your network. Look for
    opportunities in new industries and innovative companies. Your company may not really have a strategic
    or long-range plan but you should.

    ====================================================================

    Also see Alan Turing and Strategic Management