Tag: Putin

  • Note on the Current Global Oil Market

    Note on the Current Global Oil Market

    Saudi Arabia Oil Minister


    U.S. Oil Production


    Energy prices could go up
    at the same time that energy production could continue to decrease, although
    not as much as simple supply/demand forecasts would expect (see prior post).  Crude oil prices would have to rise from
    current $35/barrel level to at least $50/barrel to stabilize production and
    over $60/barrel to start increasing production. 
    Similar percent increases would be needed for natural gas.

    For most shale oil and
    natural gas producers, virtually all operating revenue is now going to debt
    payments.  After hedges come off, the
    number of bankruptcies and “distressed debt” will accelerate in second quarter
    of 2016.  The companies can continue
    production but bondholders, lenders and stockholders will suffer even larger
    losses.  This trend has already started
    in the junk bond market and the fall of public oil companies’ stock prices.


    Why Saudi Arabia Misjudged U.S. Oil Production


    While OPEC countries produce 40% of the world’s oil, there
    is no consensus on policy.  Just the
    opposite.  There are deep rifts between
    countries, as discussed in earlier posts. 


    Saudi Arabia and its allies believed that all-out production
    would quickly create a global glut, falling prices and a sharp cutback in U.S.
    and Canadian production.  Unlike most
    countries, American oil is produced by private companies that have to worry
    about profits and meeting debt obligations. 
    But over the last year, U.S. oil production has stayed high and is only
    now beginning to decline.  This has
    occurred even though the number of drilling rigs has decreased.  What the Saudis misjudged was that American
    drillers adapted to lower prices by shutting down low-producing wells, using new
    technology to increase output per well, reducing drilling costs by drilling
    deeper faster, and forcing suppliers to reduce their prices to producers.  Breakeven prices came down.  However, at $35/barrel, virtually all drillers
    are losing money.  More and more are
    having trouble meeting debt payments from operating income.  In the last two weeks, three junk bond funds
    have folded, mostly because of losses on energy junk bonds.  Total oil production is starting to decrease.


    One reason that American oil production stayed at higher
    levels than the Saudis expected is that when oil prices began to go down in
    late 2014, many drillers hedged part their production.  This means that they locked in prices higher
    than the declining market (spot) prices. 
    Revenue was higher than forecasted just from looking at market prices. 


    If I Were the Oil Minister of Saudi Arabia


    There is still too much global oil production as inventories
    continue to build up.  There is an
    estimated 30 billion barrels of oil in inventory, about 33 days of
    consumption.  The only growth sector of
    the oil industry is the building of storage facilities.  Some oil is being stored on tankers at sea. 


    Price increases will lag any production declines as
    inventory is worked down.  Global
    production will probably have to decrease by at least 2 million barrels per day
    for some time before supply comes back into balance with demand and prices rise,
    even if global demand is stagnant.


    As Saudi oil minister, I would continue all-out
    production.   Most of the American hedges
    expire in the fourth quarter of 2015 and the first quarter of 2016.  By the end of the second quarter of 2016, the
    financial condition of American drillers should be critical.  More drillers will declare bankruptcy.  But again, the decrease in production will be
    less than forecasted.  By declaring Chapter
    11 bankruptcy, drilling companies can continue in operation without the major cost
    of debt expense.  Companies will merge
    and assets will be sold.  Even given
    this, the Saudis can probably expect total U.S. and Canadian production will
    decline by about one million barrels a day.


    Besides Saudi Arabia and its allies, a number of other
    countries both within OPEC and outside OPEC would also like to decrease
    production.  Prices would rise but only
    if other countries did not raise production to take away market share. 


    With inelastic demand, the percent reduction in total output
    would be less than the percent increase in price.  Total export revenue would increase.


    If I Were Vladimir Putin


    While a number of countries might be willing to make a small
    percent reduction in production, the two wildcards are Russia and Iran.  Russia and Iran, as supporters of the
    government of Syria, are geopolitical rivals of Saudi Arabia.  But another year of low oil prices would put
    serious strains on the domestic economy and the government finances of
    Russia.  President Putin might calculate
    that the political risks of continued low oil (and related natural gas) prices
    are too high.


    Russia, one of the three largest oil producers, might keep
    production high for domestic political reasons and “free-ride” on a global
    price increase.  Iran, recently released
    from economic sanctions, has announced planned increases in production.  Russia might work out a long-term deal with
    Iran that would have economic and geopolitical benefits.  Russia would slightly cut back production
    (about 2 1/2% to start) and buy Iran’s increased output as a substitute and
    resell it to Europe.  Over time, Russia’s
    older fields would have declining production and Russia would abandon plans for
    very expensive (and unprofitable) Arctic exploration projects, which relies on
    Western technology.  Instead, Russia
    would buy increasing amounts of Iranian oil. 
    In exchange, Russia would build more nuclear power plants in Iran and
    supply Iran with uranium (and arms).  Russia
    and Iran have already agreed to the first steps of a nuclear power plant deal;
    it could be expanded as Iran sells more oil to Russia.  Both Russia and Iran would benefit from higher
    global oil prices without an explicit deal with Saudi Arabia.


    Conclusion


    Global oil production has to fall by about 2 million
    barrels/day from its current level of around 92 million barrels/day to work
    down inventories and increase prices.  By
    the middle of next year, half of the decrease will come from the U.S. and
    Canada.  So the rest of the world only
    has to decrease production by 1%-2% for prices to eventually rise.  A price increase to the $50-$60 range –
    40-70% from the current benchmark prices – would greatly increase the hard
    currency export earnings of all oil exporters and probably not lead to
    production increases in the U.S. and Canada.


    This seems like a no-brainer.  But will it happen?  A game theorist familiar with the Prisoner’s
    Dilemma would be somewhat doubtful.  These
    are not the purely rational players of game theory.  Despotic political leaders and their
    political elite more concerned about staying in power and other domestic
    concerns head many of these countries.  Some are also geopolitical rivals, often with
    an overlay of intense religious or historical animosity.  And virtually every OPEC member has a history
    of cheating on production quotas.

    ==================================================================

    A number of prior posts discuss these themes in more detail.  See the recent post on Saudi Arabia.
  • Ukraine and Russia

    Ukraine and Russia

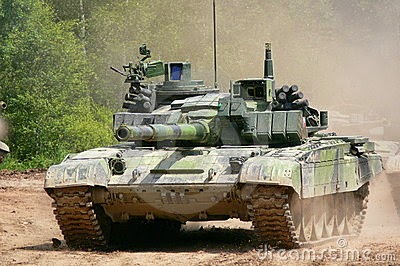
    Russian T-72 Tank Seen in Ukraine


    HISTORICAL BACKGROUND

    Most of what is now Ukraine
    came under Russian control in the 1700s, due to the expansionist policies of
    Catherine the Great.  Part of western
    Ukraine (Galicia) was a province of the Austro-Hungarian Empire. 

    With the collapse of the
    Romanov regime in 1917 and Austria-Hungary in 1918, Ukrainians attempted to
    establish an independent republic. 
    During the Russian Civil War, Ukrainian nationalist groups fought on the
    side of the Communist Red Army because they knew that if the monarchy were
    reestablished, Ukraine would be forced back into the Russian Empire.  Their hopes for independence were crushed as
    the triumphant Communist regime absorbed Ukraine into the Soviet Union.

    Ukrainians suffered under the
    Stalinist regime.  Because the Ukraine
    was the “bread basket” of the Soviet Union, grain and other crops were
    systematically confiscated by the Communist government to feed industrial
    workers at subsidized cost and exported to earn foreign currency.  Bad weather plus confiscations in 1932-33 led
    to millions of Ukrainians starving to death.

    During World War II, some
    Ukrainians fought with the Nazis, hoping to be free of Russian rule.  After the war, Ukraine was treated harshly as
    punishment.  All Tatars in the Crimea were
    deported to the interior of Russia; over half died.

    RECENT CONFLICT BETWEEN UKRAINE AND RUSSIA

    From 1991 until 2004, Ukraine
    was ruled by former Communist bosses and their protégés.  Little changed politically or economically.  Some state assets were privatized, creating a
    small group of oligarchs with ties to government officials.  Corruption was rampant.  Old industries were not modernized.  Production and exports were still mostly
    oriented to supplying Russia with food, industrial materials like pipe and
    weapons. There was little economic growth or development.

    Fed up with the lack of
    progress, corruption, and economic stagnation, Ukrainians took to the streets in
    2004 to protest the regime of President Viktor Yanukovych.  The “Orange Revolution” was one of a number
    of popular protest movements against authoritarian regimes on the Russian
    periphery.  President Yanukovych was
    replaced by a democratic government. 
    Unfortunately, the President and the Prime Minister became bitter
    enemies.  The pro-Russian party of former
    President Yanukovych had a strong position in parliament.  The government appeared paralyzed and didn’t
    institute the reforms demanded by the “Orange Revolution” protesters.  Aided by Putin’s campaign managers and Russian money, Viktor Yanukovych was elected President again
    in 2010. 

    Unlike the peaceful “Orange
    Revolution” of 2004, the 2013-2014 demonstrations protesting the pro-Russian
    policies of President Yanukovych led to the use of violence against the
    demonstrators.  This time the removal of
    Yanukovych led to an armed rebellion against the new government by Russian separatists in the eastern
    provinces (Yanuokovych’s political base), a Russian takeover of the Crimea and
    a shooting war with Russia over control of Ukraine’s eastern provinces. 

    NATURAL GAS AS A GEOPOLITICAL WEAPON:  UKRAINIAN DEMAND FOR RUSSIAN NATURAL GAS

    Before the conflicts began,
    Ukraine depended on Russia for about two-thirds of its natural gas, about 30
    billion cubic meters a year.  The cost
    was around $10 billion minus transit fees, a major cost for a small economy of around $200-$250 billion.  Demand has
    decreased because of the loss of territory and a severe recession, down to probably
    around 20-25 billion cubic meters.  But
    Russia has increased the price and threatened to continue the current shut-off
    of gas through the winter.  Ukraine  agreed to pay arrears for past purchases and pay COD for future purchases.  Russia agreed to supply gas for six
    months. 

    The money for these purchases
    and other debts will come from a $17 billion loan from the IMF.  In addition to paying for Russian gas and
    oil, a $3 billion Russian loan will come due in 2015.

    Ukraine is trying a number of
    strategies to reduce its dependence on Russian natural gas.  One is conservation.  Ukraine, despite being poor, has one of the
    highest natural gas per capita usage rate in the world.  A major reason is that the cost to consumers
    and industry is heavily subsidized; the retail cost is about 25% of the
    wholesale cost Ukraine pays to Russia. 
    Raising the internal price under current conditions will be politically
    unpopular and maybe impossible.

    Ukraine has tried to receive
    natural gas from neighboring countries by “reverse flow” of Russian gas
    delivered through Ukrainian pipelines. 
    Russia has successfully pressured at least two of the four countries
    (Slovakia and Hungary) not to do this.

    In the future, Ukraine may be
    able to develop large shale gas fields which may be an extension of shale gas fields in adjoining eastern Poland. 
    Ukraine also intends to build a short pipeline to Poland.  Gas will come from an LNG plant Poland is
    building and other non-Russian sources through interconnect pipelines.

    RUSSIAN GAS PIPELINES THROUGH UKRAINE

    Worried that Ukraine could
    shut off deliveries to Europe, Russia’s strategy has been to bypass the Ukraine
    pipeline network.  The Nord Stream
    pipeline in the North Sea reduced the percent of Russian natural gas exported
    to Europe through Ukraine from 80 percent to 50 percent.  It brings gas directly to Germany, its
    largest EU customer. 

    The proposed South Stream
    pipeline through the Black Sea to Bulgaria would have enough capacity to
    eliminate Ukraine as a transit point for Russian gas.  As a political reaction to Russia’s military
    actions, the European Union pressured Bulgaria to suspend participation in
    building the pipeline and terminal.  The
    South Stream pipeline currently is on hold. 
    The interim Bulgarian government before the recent elections signed an
    agreement to be part of a competing pipeline consortium that brings Azerbaijan
    natural gas overland through Turkey and Greece to Bulgaria.  A European Union committee is discussing building interconnect pipelines through Central Europe (heavily dependent on Russian gas coming through Ukraine) to Austria.

    UKRAINE’S ECONOMY

    Even before the conflict with
    Russia, the Ukrainian economy had not progressed.  In 1991, the economies of Poland and Ukraine
    were about the same size.  Since then,
    Poland’s economy has tripled in size while Ukraine’s economy before the current
    conflict was about the same size as in 1991. 
    The differences may be somewhat smaller since much of the Ukraine
    economy, maybe as much as 40%, is underground.

    The continuing war in the
    east and the loss of the Crimea has devastated Ukraine’s already weak
    economy.  The eastern provinces contain
    the bulk of the Ukraine’s manufacturing capacity and coal mines.  Russian has imposed sanctions on some
    Ukrainian exports.  Ukraine’s economy is
    expected to shrink by 8% this year and again next year.  If fighting continues, this is probably too low an estimated.

    Ukraine’s foreign-exchange
    reserves are falling rapidly.  International
    loans from the IMF and aid from the European Union have only bought time for
    Ukraine.  It seems impossible that
    Ukraine can meet its debt obligations without new loans and aid.  Two months ago, the IMF said that Ukraine
    will need an additional $19 billion if the fighting continues.  Even with new loans, it is likely that
    Ukraine will have to default or renegotiate its external debt.  Part of its external debt is owned by Russia.

    POLITICAL CONSEQUENCES TO UKRAINE AND RUSSIA

    Ukraine
    is the most important application of the Russian foreign policy doctrine of
    recovering lost territories and forming the old Soviet Union (actually, the old
    Russian Empire since Communism is no longer the official ideology).  Putin’s power and domestic support crucially depends
    on this strategy succeeding.  After a massive and emotional propaganda campaign, there is no
    way the current Russian government of Vladimir Putin can allow Ukraine to
    retake its lost eastern territory or the Crimea.  When it appeared that the Ukrainian army
    might defeat the separatist rebels, Russia sent in Russian special forces and
    heavy weapons.

    What has
    Russia gained and lost by seizing Crimea, supporting the eastern rebels and
    sending Russian military forces and weapons into Ukraine?  Russia has
    gained direct Influence or control over 15-20% of Ukraine’s population, which
    was Russian or pro-Russian before the invasions.  There is little economic advantage; the
    eastern provinces the separatists control are a depressed area with old
    industries and uncompetitive coal mines.  Many of the companies have shut down because of the fighting or management fleeing the area.

    Both Ukrainian and Russian
    refugees will continue to leave the area controlled by the separatists.  As of the end of October, the United Nations estimates that about one million people have left, out of a pre-war population of 4.5 million.  Other estimates are higher.  About half have gone to Russia and half to other parts of Ukraine.  Refugees tend to be the young and better educated.  Russia will need to heavily
    subsidize the region just to restore devastation and basic services.  Already eight large convoys from Russia have carried food (and probably military goods) to the separatist-controlled areas of Ukraine.  

    This will
    leave a Ukraine of about 35 million people that just voted 92% to be
    anti-Russian and pro-Europe.  Russia has given Ukraine nationalists a
    permanent issue.  It also eliminates part of the economic and political
    power base of the pro-Russian oligarchs. 
    Most of the oligarchs, including the President, are now firmly
    pro-Europe. 

    In the
    long run, Russian intervention may eliminate a 300 mile buffer zone from NATO
    forces and puts a large anti-Russian country right on its borders.  But without internal reforms and with Russian
    troops on its eastern and southern (Black Sea) territory, Ukraine will continue
    to be weak economically and militarily.


    In retaliation to economic sanctions, Russia has banned about $9 billion of imports, mostly food.  Foreign food products are disappearing from Russian stores.  Russian substitutes either don’t exist or are of poorer quality.  This is the first sign that the Russian people, at least the urban middle class, are beginning to pay a price for Russia’s intervention in Ukraine.  Greater economic pain will follow.  

    ====================================================================

    For background, see an earlier blog:

    https://politicaleconomicsprof.com/2014/06/ukraine-background-to-current-crisis.html

    For earlier analysis, see:

    https://politicaleconomicsprof.com/2014/03/the-crimea-russia-and-us-options.html

  • The Crimea, Russia, and U.S. Options

    The Crimea, Russia, and U.S. Options

    Ukraine President

    Russia’s
    illegal invasion and annexation of the Crimea will set off a chain of events
    that could strengthen U.S. power and influence, especially in Eastern Europe.  Putin is gambling that President Obama and
    conservative Republican leaders lack the will to energetically react to Russian
    expansion.  First U.S. reactions have
    been weak.  Unless there is a change,
    Putin might be encouraged to annex other Russian-dominated areas outside
    current Russian borders.

    Ukraine
    has tried to balance Western and Russian pressure.  The popular revolt against the pro-Russian
    Ukrainian Prime Minister upset the balance and precipitated the crisis.

    Putin may have decided to upset the unstable status quo in Eastern Europe, starting with Ukraine and Moldova.  Russia’s next step could be to annex the eastern third of Ukraine.  This area includes the Donetz Basin, which
    contains a Russian majority and industrial resources.  If successful, Russia could then move along the
    north shore of the Black Sea to Odessa and maybe to the Rumanian border.  Russia
    already controls the eastern third of Moldova, presenting Ukraine, especially
    the Kiev region, with the possibility of being threatened or attacked from both
    the east and the southwest.

    The
    Russians are very concerned about their long-term demographic trends.  Russia’s population is declining.
     Russia’s population is now about 1/2 that of the U.S. and the gap is
    widening.  And, in the foreseeable future, European Russians will be
    outnumbered by Asians (east of the Urals) and Muslims within Russia.  Adding millions of European Russians may have
    played a part in the decision to annex the Crimea.

    All of
    this has domestic advantages for Putin.  His moves are popular in Russia.
     Future leaders will probably also have to be nationalistic and probably
    expansionist, putting pressure on Russia’s periphery.  It was naive of the U.S. to 
    think that Russian nationalism suddenly disappeared with the Soviet Union.

    An
    expansionist Russian foreign policy entails huge risks.

    About 40%
    of the population in the Crimea is Ukrainian and Tartar.  Both groups in the region have centuries-old
    historical grudges against the Russians.  By making a de facto control de jure, the Russians are making sure that 40% of the Crimean population will now feel
    like a conquered minority and will look to Ukraine for support.  

    The takeover might also finally unite the pro-West political leaders in the Ukraine. Ukraine
    has already signed the economic cooperation treaty with the EU that started the
    crisis.
      Ukraine needs immediate
    financial support.
      With loss of
    territory and increased Russian pressure, Ukraine will probably ask to join
    NATO if it can be guaranteed U.S. military support in weapons systems and
    training.
      If this happens, Russia will
    be faced with another enemy, along its crucial southern European border.
      Putin is gambling this won’t happen.

    It is also likely that Putin’s land grabs will reinvigorate NATO and focus  U.S. attention on European security issues.  

    All this will affect Poland. Poland
    does not have a border with Russia, except for a short strip to
    the north with the Russian enclave of Kaliningrad.
      Poland has long borders with Ukraine and
    Belarus.  Belarus – the old Russian province of Byelorussia or White
    Russia – is between Poland and Russia.  But Belarus is for all intents and
    purposes still a province of Russia.  Poland, and NATO, still has to plan
    that Russia could put troops on the Polish border and attack across the
    northern Polish plain.  Poland will probably 
    have to step up military spending and ask for more NATO support.

    The U.S.
    is putting an advanced air defense system in Eastern Europe, mostly in Poland.
     One consequence will probably be to extend the system to southern Balkan
    countries and step up other types of military aid to Eastern European countries
    that are members of NATO or the EU.

    The
    Crimean takeover should drive Eastern European countries even closer to NATO
    and the EU.  But the U.S. has to provide substantial military support in
    training and weapons.  Given the sequester’s effects on the military
    budget, there is some doubt this will happen.

    Beside
    military support to NATO, especially Eastern Europe, the U.S. has a number
    of good responses, including a rapid increase in oil and especially natural gas
    exports to Europe.  I’m not sure Obama has the political will to overcome
    opposition within the Democratic Party to the pipelines and LNG
    plants to quickly approve them, although Putin has handed him a
    potent new argument.   Combined with developing huge untapped reserves of
    natural gas in shale around the world, the Europeans would be assured that they
    would not be dependent on Russian gas in a few years.  

    Russian
    sales of oil and natural gas account for about 70% of their export
    income.  Combined with economic
    sanctions, a fall in foreign investment, capital flight and a loss of tourism,
    the Russian economy could be severely damaged.

    Maybe
    Western European countries will wake up and realize that Russia is still a
    political and military threat.  If the
    U.S. does not act energetically and decisively, European countries, especially
    Eastern European countries, may decide they have to accommodate Russian
    aggression.  The danger is greatest for
    the next few years when Europe will still be dependent on Russian natural gas.

    Turkey, a
    long-time member of NATO, should finally be admitted into the European Union.

    Another
    possible consequence of Russian expansion could be America’s relationship with
    China.  If China sees Russia as more aggressive, this could improve
    relations between China and the U.S.  An extreme but interesting gambit
    would be for the U.S. to support Chinese claims to resource-rich eastern
    Siberia.

    ===================================================================

    See related post, President Obama Learns Some Game Theory.