Category: Uncategorized

  • The Stock Market is Up and the Economy is Down:  What’s Going On?

    The Stock Market is Up and the Economy is Down: What’s Going On?

    It is a puzzlement why the stock market can go up while the economy is in a virus-caused depression. Much of the economy is in lockdown or closed because of decreased consumer demand. As many of one-third of workers and many small businesses are on federal life-support programs. Profits have disappeared. Large numbers of bankruptcies loom. Given the uncertainty, including recent record numbers of new virus cases, the usual stock evaluation metrics are worthless.

    With the economy tanking, how come the stock market has gone up dramatically?

    And continues to go up.

    THE STOCK MARKET

    Let’s decompose the stock market. When people talk about the stock market going up or down, they usually refer to an index such as the S&P 500 as the measurement. The S&P 500 is a market-value (cap, short for capitalization) weighted index. The ten most valuable companies account for over 20% of the total value of the index.

    There are over 3,000 actively traded stocks. But the 500 companies account for over 80% of the total value of all stocks. They also account for a minuscule percent of the 10-20 million companies in the United States.

    Public companies account for about one-fifth of U.S. employment. Small companies account for about half of private sector employment. Government accounts for about 10% of total employment.

    So, the dominant public companies are not representative of the economy. They are not even a representative sample. They are publicly owned. Even the smallest is much larger than almost all other U.S. companies. They are usually multinationals. And the largest, most dominant companies in market value are technology companies. The six companies with the highest market value are Facebook, Apple, Amazon, and Alphabet (the parent company of Google. Counted twice. Don’t ask.), collectively known as the FANG companies, joined by Microsoft.

    Technology companies account for over 30% of the total value of the S&P 500. Digital or online companies are 13 of the 20 most valuable corporations in America. Nine of them did not exist or were small companies 25 years ago.

    THE VIRUS ECONOMY

    The economy has gone into a depression, the worse since the Great Depression of the 1930s. Damage has been limited because of massive federal income maintenance programs for workers and small business owners.

    The severe downturn, caused by the virus and attempts to control the spread of the virus, has made visible that the economy is divided into two parts. (Yes, I know this is a huge simplification but not as simple-minded as most economic theory.) There is the service sector, the largest employer. Most of the companies are small. Many of the employees are low wage. They work in buildings and meet customers. Services and their employees have been very hard hit by the virus and the depression. At the other end are the technology companies that dominate the digital economy. As a group, they have done well during the depression as consumers and business have used their digital platforms and services as substitutes for physical interaction (aka store shopping, visiting doctors’ offices, online entertainment and commuting to work).

    This split is reflected in the stock market and the indexes. Of the 500 largest companies, 44, mostly tech companies, are up 20 percent or more since the market low of March 23. The big six are up over 60% since the bottom of the market, accounting for more than 40% of the increase in the value of the S&P 500. Tech companies like Nvidia and biotech companies account for much of the rest of the increase.

    Less known is that approximately 160 companies of the 500 are down more than 20%. Although the market average is almost the same as at the beginning of the year, the stock prices of about 350 of the 500 companies are down. They are large and important parts of the older economy.

    TIMING

    The timing of the market moves is surprising. The market hit its high on February 19, a month before the president admitted there might be a problem and weeks before the more aggressive governors announced lockdown rules. While the president was telling the country there wasn’t a problem, investors began unloading stocks.

    In the last week of March, as the president began hinting there might be a problem, the stock market hit bottom. As the number of new virus cases and deaths rapidly increased, and lockdown and quarantine rules were extended, the economy tanked. But the stock market began a rapid recovery, one of the strongest and quickest in history. Even as the virus situation worsened in most of the country, the stock market continued to go up.

    During the strong advance no one, not even corporate management, had any firm idea what corporate sales and profits would be in the future. No one could do the usual financial analysis. Every wealth fund manager, financial analyst and investor I’ve talked to said the market was crazy, irrational, unpredictable (usually preceding by a colorful adjective).

    But the main reason is obvious. The dominant companies in the stock market were part of the digital sector of the economy. Besides the monster tech companies, they were into telemedicine, video conferencing for fun, family and business, video streaming and other online entertainment, e-commerce, cybersecurity, and many other online services. Behind them was a large increase in cloud computing services.  

    The accelerated shift to these companies’ services and products indicated accelerated increases in sales and profits. The macroeconomic averages and totals for the economy looked dismal. But not for these companies.

    The stock market looks ahead. Investors forecast. They anticipate. Today’s news and events have little influence, even short run influence, on stock price movements. Investors have placed bets on their best estimate (known among statisticians as SWAG – statistical wild-ass guesses) of what will happen to corporate sales and profits in the future. As my old econ prof used to say, “You puts down yer money and takes yer chances.” Transitory and political events, no matter how dramatic and urgent, usually have very short run or no influence on stock market prices.

    But not the virus. By mid-March, it was obvious it would have a large and lasting impact on the economy. It was the powerful “exogenous shock” of economics (also known as the “black-swan” or “fat-tail” or “big tsunami” event). 

    The unknown was how big and especially how long. Politicians, especially the president and some Republican governors, argued the virus’ effect would be short-lived and not too deadly or disruptive. They dismissed the proposed attempts to limit economic activity to slow down the spread of the virus. The famous “V-shaped” recovery. It seemed that many investors agreed. As the market rose rapidly, new investors flocked to the market. Average daily volume so far this year is up over 60% compared to average daily volume in 2019. Much of the internet chatter sounded awfully familiar to me – it was the same as in histories of the 1929 stock market crash.

    But the market hasn’t collapse (yet). The big difference is the massive income maintenance federal aid programs, along with the Fed’s massive money creation and its underwriting of virtually the entire debt market. Already about 40 million  American workers (25% of the labor force) have received some form of federal aid. The main program has been unemployment benefits. The maximum benefit has been raised by $600/per week and eligibility standards have been loosened. About two-thirds of the workers who have been on unemployment received benefits as high or higher than their pre-virus income.

    Investors are betting that worsening virus news will have little effect on the economic recovery, that federal income maintenance programs will go on as long as needed (or at least to the November elections), that the Fed will keep the Fed funds rate near zero and finance the massive government deficits, and that demand for online and digital services will continue to increase.

    Result? Sometime in late 2020 or early 2021, total earnings would be expected to return to 2019 levels. The S&P 500’s price/earnings ratio (P/E ratio) of this forecast has already returned to the high 2019 levels. 

    New medical protocols are reducing the death rate. Sometime in the near future an effective vaccine will be announced. All of the stock market will go up. Given how crazy this market has been, I suggest waiting a week and then start cashing in some of your winnings.

    THE STOCK MARKET IN 1933

    Something similar happened in 1933. At the depths of the Great Depression, with the entire banking system near total collapse, the stock market started to recover. The main reason seems to have been that investors were encouraged by the optimism and vigorous pursuit of new laws and policies by the incoming president, Franklin Roosevelt. In that year, the stock market went up an amazing 66.7%.

    SUMMARY

    Investors, as investors, are not directly concerned about Covid-19. They are concerned about the economic consequences of the virus, both short term and long term, especially to public companies. 

    The dominant dynamic is that most of the economy’s industries and companies are experiencing accelerated movement to the digital economy. Face-to-face transactions are expensive. Check-out personnel and cashiers are disappearing in supermarkets, Target and McDonald’s. Retail stores will function more like local distribution warehouses. Think about classrooms and doctors’ offices. And, in the future, a shrinking labor force will probably push up the low wage part of the labor market. Digital interaction will continue to be less expensive and more effective.

    The stock market – don’t look at the averages. Look at the winners and the losers. The stock market is up because it is dominated by digital and technology companies. Changes in relative stock prices indicate which economic sectors and companies will innovate and and grow their sales and profits faster than the overall economy.

    One way to think about the stock market (big public companies) is that it is made up of past winners (past innovators), current innovators, and potentially successful (profitable and growing) future innovators. The market mostly invests in future growth based on innovation. It punishes “legacy” companies, in old industries with growth determined by the growth in total income, that stop innovating.

    In short, investors are buying companies that are benefiting from the economic consequences of the virus and attempts to limit its spread. These same companies will continue to benefit after the virus is contained. Since these companies dominate the market and the averages, the market is going up. And, increasingly, these are the companies that will drive economic growth and will dominate the economy in the future.

    For a discussion of some of the economic and governmental budgetary changes caused by the virus, see my After the Virus.   

  • After the Virus: Economic Consequences

    There are a number of forecasts of what the world will be like after the virus. Let’s take a look at some of them.

    Many long-term trends have been accelerated by the virus. Probably the most cited example has been the accelerated move to digital-based transactions and behavior. This has occurred among both consumers and businesses.

    I think we have hit an inflection point. Before, there was a great deal of discussion about how one industry or market was becoming more dependent on digital platforms and automation based on artificial intelligence. The Internet of Things, online shopping and ordering, business conferencing, telemedicine. Or how a particular company was transforming an industry (Amazon, Uber). But now we see that the entire economy – all industries and markets – rely on digital. The technology and rapid adaptation are accelerating the shifts.

    Income inequality is bad and probably getting worse. The usual reasons given are outsourcing in the global economy and the effects of automation. The two reasons are related. Advances in telecommunications, including global digital networks, and management software have made the management of multinational companies possible. 

    There now appears to be another reason. We talk about the growth of the service economy. What this means specifically is that most of the new jobs created over the last few decades have been relatively low-paying service jobs. About 15% of the entire labor force (about 25 million people) works in restaurants and bars. Much of the service industry consists of services that relatively low-paid workers provide to relatively high-paid and wealthy customers. A recent study indicated that unemployment among service workers in the affluent parts of New York City was higher than in the rest of the city. On the other end of the income scale, the upper-middle class, dominated by the technological and professional elite, have seen their average incomes rise much faster than low-paid service workers. As digital replaces service workers, including office workers, income inequality and its political consequences will probably get worse.

    The move to the digital economy will also threaten many owner-managed small businesses. Because of economies of scale and scope, large digital-based corporations will lead the trend towards more concentrated industries and markets. 

    Another consequence of the accelerating use of digital platforms is the demand for technological workers will probably also accelerate. Salaries will go higher. Automation and AI software will “deskilled” (lower salaries) professions based on specific knowledge and eliminate many manufacturing and office positions. Online business collaboration will become more common. Video conferences may not be as effective as face-to-face conferences and interaction but they are a lot cheaper than leasing office space in Manhattan.

    We don’t have to worry about the huge increase in government debt. Well, maybe. Almost all of the government “stimulus” programs are income maintenance programs. They are paid for through government borrowing, a large part of which is directly or indirectly selling debt to the Fed. The Fed pays for the debt by creating money. All this does is transfer federal debt from one part of the government balance sheet to another part. 

    As long as the Fed keeps interest rates extremely low, the cost of debt service (federal interest expense) as a percent of nominal income will be low.

    A few comments. Large yearly deficits and the total national debt will continue to increase for years after the virus comes under control. None of this debt will disappear. Total debt service costs will rise, even at extremely low interest rates. If for some reason, such as inflation, interest rates rise, the cost of interest expense could rise dramatically. By fiscal 2022, a one percent increase in federal borrowing costs could add at least $250 billion to the yearly deficit. The federal government could avoid most of any potential future interest expense increases by financing the national debt at the current rate of 0.6% for 10 year bonds.

    The Fed might want to sell off some of the government debt they have accumulated. They basically have to sell it to someone else who wants to hold U.S. government debt. This increases the supply of U. S. government debt offered to be sold. It might raise interest rates on all of the national debt. 

    Even if tax revenue increases, which will happen if there is an increase in taxable nominal income without tax cuts, the continuing large deficits will put pressure to reduce outlays on “discretionary” spending. That is, all spending after Social Security, Medicare, defense, federal pensions and interest on the national debt. Unless taxes are raised substantially, it is likely that in a few years all “discretionary” spending will be funded by new debt.

    There will be little, if any, distinction between monetary and fiscal policy. The pretense that the Fed makes monetary policy independent of the rest of the government will not be credible.

    The amount of lost income should go down as the economy expands and employees go back to work. The fiscal stimulus programs basically replace the lost income of workers and small business owners. Lost income may be about $400 billion per month, including PPP subsidies of salaries. $3 trillion in income maintenance programs won’t last long. The programs are expected to end or be reduced between August and October. 

    To avoid a worse recession, income maintenance programs will probably be renewed. With the number of virus cases rising rapidly, the recovery of the service economy may be slower than forecasted. If the number of virus cases do not go down soon, service businesses either cannot open, are restricted, or customers will be afraid to patronize service establishments or entertainment venues. Many small businesses will go bankrupt. Income maintenance programs may have to be greater than assumed and continue for a longer time. Or both. We could see high unemployment levels, a surge in bankruptcies, and even higher future government debt levels.

    State and local finances are even worse. State and local governments cannot create money to cover deficits. Inadequately funded public pensions were already killing some state and local budgets before the virus hit as more public employees were retiring. These governments, which provide most of the public goods and services, will have to cut services. Already large numbers of employees, including health care workers, have been laid off. Public office workers will be laid off as more interaction with citizens will be done online. Possibly more public education will also be done online, especially at the college level. Many of these employees qualify for pensions. The federal government would have to borrow trillions of additional dollars to support state and local governments.

    Longer term. Health care is now the largest industry in the United States and growing faster than the rest of the economy. It is also a major and growing part of the federal budget. But there is no way health care benefits paid by Medicare programs are going to be cut. The number of senior citizens is expected to double in the next 20 years. Senior citizens make up a large percent of voters. Over 30% of the Florida voters in this year’s presidential election will be senior citizens. In a close election, the winner must take Florida. I doubt if a candidate campaigning on a platform of cutting health care services to slow down the growth in Medicare costs would do well in Florida and elsewhere.

    All of this indicates that government money to tackle societal problems – large increases in investment in infrastructure, funding the huge costs of climate change, programs to increase the low rates of economic growth and productivity, new income maintenance programs, and many others – will not be available in adequate amounts. What this means is that the costs of mitigating the damage from climate change will be higher than expected. 

    One partial answer to these problems is accelerated innovation in new technology, especially in health care. This is likely to happen. Senior citizens, technology companies, and their employees and stockholders will benefit. But unlike the past, the new technology may be highly disruptive by increasing long-term unemployment and income inequality. Whether or not new public programs and policies will be created is uncertain in the current political climate and the future reality of government budgets. If not, the types of social, economic and political conflicts we are currently experiencing could get worse.

    For background on understanding government finance, budget deficits, trade deficits, and how they are related, see my Government Finance 101. This post also discusses the fiscal effects of Covid-19.

    You might also be interested in my extended explanation of The Stock Market Crash of 1929 and the Beginning of the Great Depression. Some of the analysis and conclusions may surprise you.


  • Josiah Wedgwood, the Wedgwood Pottery Company, and the Beginning of the Industrial Revolution in England

    Josiah Wedgwood, the Wedgwood Pottery Company, and the Beginning of the Industrial Revolution in England


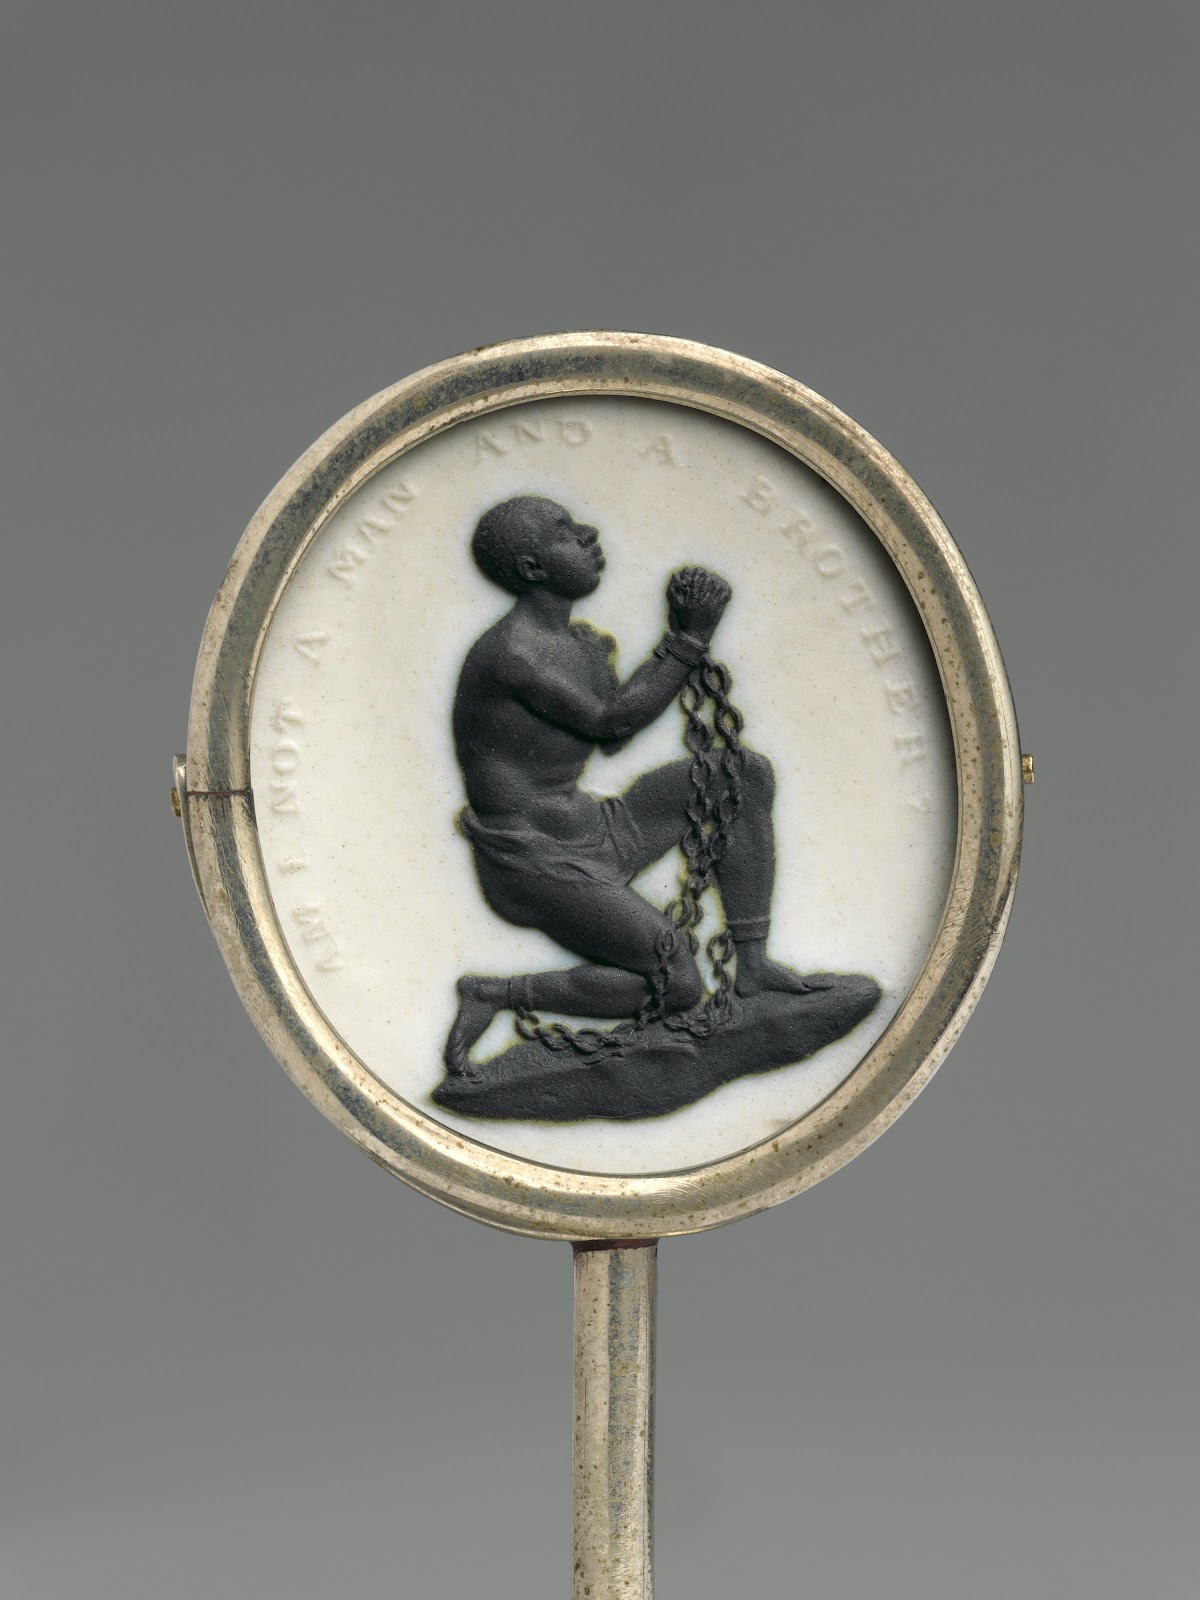
    Wedgwood Anti-Slavery Cameo

    A better introduction to the beginning of the Industrial Revolution than Adam Smith is the history of Josiah Wedgwood and the Wedgwood Pottery Company.


    This is how one company actually ushered in the Industrial Revolution.


    The revolutionary generation that first adopted steam engines saw the following trends and changes:


    Manufacturing was being modernized by a small group of entrepreneurs. Much of the new raw material processing and manufacturing was concentrated in a small area in the middle of England, away from London. These modernizing entrepreneurs formed a new economic, intellectual and social network.


    Modernizing entrepreneurs like Wedgwood tended to be members of Dissenting sects (like Quakers) or Nonconformist churches (not members of the Church of England), Whigs (liberals) in politics, and believers in “progress.” They were optimistic about the future, influenced by the ideas of Hume, Rousseau, Locke and Adam Smith. They believed their society could be reformed and they were active agents for improvement.


    In 1787, Wedgwood produced a ceramic medallion to support the abolition of slavery. It had a chained African pleading, “Am I not a man and a brother?” This was in the country that became rich by dominating the African slave trade and raising Caribbean sugar with slaves working under brutal conditions. 


    They believed in studying and understanding the material world through reason, data, experience, and experimentation. They had personal ties with scientists and intellectuals. 


    Like Wedgwood, many came from poor backgrounds. Because of their backgrounds and dissenting religious beliefs, they could not attend Oxford or Cambridge. They were cut off from the traditional avenues of social advancement – government official, army officer, and the Church of England. 


    The Industrial Revolution gave them opportunities for economic success denied them under the pre-industrial society. Entrepreneurs could develop these opportunities because of a long political struggle in England to establish the rule of law, individual rights, property rights, patents and limits on governmental power. It also helped that they were largely ignored by the king and the landowning aristocracy.


    The Industrial Revolution was a radical break in history. But in England, many of the preconditions were already in place, as can be seen by the history of the Wedgwood company.  


    Josiah Wedgwood came from a family of potters. He founded the famous Wedgwood pottery company in 1759. 


    Wedgwood and many of his business associates and acquaintances were modernizing entrepreneurs. Wedgwood and others built large factories recruited and industrial labor force, and understood the division of labor. They were constantly looking to improve their businesses – better machines, larger and more efficient production, new and improved products, new materials and marketing.


    A limiting factor was power to run the machinery. Waterwheels were inefficient, with not enough power to drive the larger, faster, heavier machinery. English rivers were flat, sluggish, and sometimes dry because of droughts. The solution – Watt’s steam engine, which was first manufactured in 1775.

    James Watt invented and patented a more efficient steam engine but it was Matthew Boulton, a friend and sometime business partner of Josiah Wedgwood, who partnered with Watt and built the factory that produced Watt’s steam engines. Boulton heard about Watt’s engine through a mutual acquaintance in his network of correspondents. Boulton, a successful manufacturer, established and ran a new company (Boulton and Watt) that dominate steam engine production and marketing for a generation. Watt concentrated on improving his steam engine and inventing related technology. Like many later industrial companies, Boulton and Watt was the combination of a businessman and an inventor/mechanic.


    Innovation at Wedgwood was based on science and experimentation. Josiah Wedgwood carried out thousands of experiments in his lifetime analyzing all aspects of pottery manufacturing and decoration, and record the results in detailed notebooks. He read chemistry books and knew and corresponded with the foremost chemists of his day. He tried to reduce the traditional hit or miss methods of producing pottery to more scientific measurement and control. (This tradition of careful observation and scientific understanding of the natural world was passed on to Josiah Wedgwood’s grandson, Charles Darwin.)


    Josiah Wedgwood used power-driven machinery and early assembly line techniques to mass-produce pottery. He was the first manufacturer to install a Watt steam engine.


    Wedgwood was always on the lookout for new styles, better machinery (lathes and kilns) and new production methods. He believed in retaining employees and training them to become increasingly productive. To keep employees, he provided housing and retirement benefits. Wedgwood cooperated with other manufacturers he knew to introduce new materials and new processes into the production of pottery.

    Wedgwood expanded sales and profits by selling in foreign markets. He provided a large amount of specially designed pottery to the English and Russian royal families. Wedgwood turned a luxury product for royalty and the very rich into a mass market product for the expanding upper middle class. In addition to European countries, Wedgwood made a special effort to sell to the American colonies. He designed different styles at different price points for different markets. Today we would call this market segmentation.  


    His experiments with new materials and production methods led to the creation of new styles of pottery, which he believed were necessary to increase sales. Wedgwood changed styles every few years, backed by innovations in marketing such as showrooms and branding that were to become standard in the selling of consumer goods.


    In summary, he exploited new production technology and combined it with scientific production control and management. His innovative design and selling strategies became standard for future consumer goods companies.


    ==============================================

    See the related post, Adam Smith’s Pin Factory.

    For the rise of England as a global economic and political power in the 1600s, see

    England in the 1600s:  The Beginning of England’s Rise to Global Power and Wealth

    These posts analyze the factors behind the start of the Industrial Revolution in England and America.  Pre-conditions were important. They illustrate some of the reasons why, in the long run, America was able to continue industrializing better than England, why England fell behind.


    The Beginning of the Industrial Revolution in England


    The Beginning of the Industrial Revolution in America


    Innovate or Fall Behind. A Cautionary Tale – England and the Industrial Revolution

    Some related posts:


  • Global Demographics and Economic Growth

    Global Demographics and Economic Growth

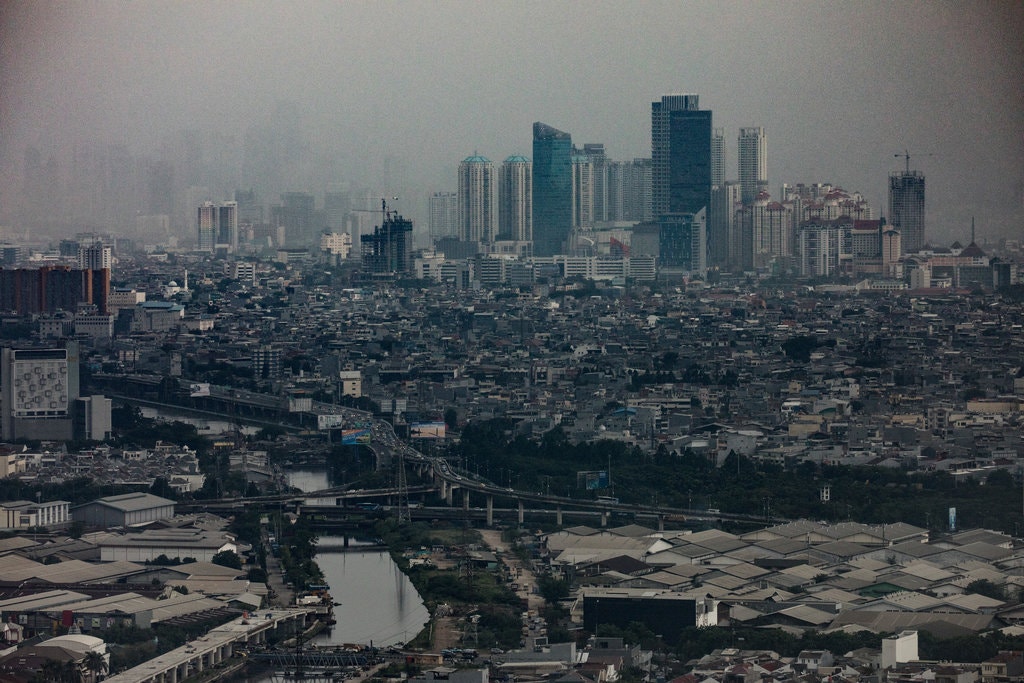
    1. Jakarta – 30 million people and sinking

    GLOBAL DEMOGRAPHICS

    Demographics, the study of the size and composition of population, will shape national and global economic growth and economic policy.  

    The period from 1950 to 2000 was highly unusual. The American “baby boom” started, temporarily reversing the long-term decline in birth rates.  Not just the United States but the global population experienced high birthrates and high population growth rates. In the middle of this period, partly due to more effective and more available birth control, birth rates began a rapid decline. The growth rate in world population began to fall. At the same time, much of the world’s population experienced rising standards of living. One consequence was longer life expectancies and rising average ages in industialized countries.  

    Countries with over a third of the world’s population and most of the world’s output now have birth rates below replacement. They are mostly the wealthy, industrialized countries, including the United States, Canada, Brazil, Western and Eastern Europe, Turkey, parts of Southeast Asia, Japan, Russia and China. Collectively, the size of their labor forces have stopped growing. All countries face the same challenges: Will they be able to invest in economic growth and development (innovation and structural change), deal with environmental costs and climate change effects, and support aging populations?  

    There are falling birthrates for most of the rest of the world’s population, coming down from very high levels. Mexico is at replacement and India is close to the replacement birthrate. But total population continues to grow, partly because of lower infant and child mortality rates, public health programs, better medicine, and subsequently longer lives in most of the world.  

    We are now in a period of a slowdown in total population growth rates. Global population is growing at about one percent per year and the rate continues to fall. But the increase in the number of people is large. In the most recent United Nations projection, the increase in global population from 2020 to 2050 is about 2 billion people, from 7.8 billion to 9.7 billion. The projected population increase over the following 50 years is lower, abour 1.2 billion. 

    Changes in total population may be points on an exponential decay curve. The UN projects that zero population growth will be achieved sometime shortly before 2100. The rate of decline could change with changes in the availability and cost of birth control, education of women, anti-aging medical technologies and more available health care for an aging population. (Estimates of future population are from June 17, 2019 UN projections. UN projections are revised about every two years.)

    The biggest unknown is future medical technology that will prolong life expectancies. Regardless of projection, the fastest growing age cohort is 65 years and over; within that cohort, the fastest growing age group is 80 years and older.

    Countries with birthrates well below replacement and aging populations may experience accelerating decreases in population. Family planning, combined with urbanization and more education of females, could lead to birth rates declining faster than projected in high birth-rate countries. In Africa, Ethiopia, Malawi and Rwanda promoted family planning and have seen large decreases in their birth rates. Kenya, after investing in family planning clinics and information, has seen its fertility rate fall from 6.5 in the late 1980s to 2.4, marginally above replacement and half the rate of most African countries.

    POOR COUNTRIES AND RICH COUNTRIES

    Wealthy countries have below replacement birth rates, no growth or declining populations and labor forces, low real economic growth, and aging populations and labor forces. Population will continue to concentrate in cities; the population of a small number of cities will be responsible for technological innovation and economic development. Rural areas will continue to lose population.

    Poor countries today have high but declining birth rates, young and increasing populations, and populations that want to emigrate (see case study below).

    Most of the largest and fastest growing urban areas in the world are in poor countries, China and India. Over half of the world’s population live in cities and the percent is rising. Almost all of the increased population in poor countries will live in or move to cities, which are already ecological disasters – traffic gridlock, poor air quality, lack of infrasturcture, sinking, raw sewage, and power outages. Many are coastal cities that are already experiencing periodic flooding and storm surges; rising sea levels and the increased number and severity of hurricanes will intensify urban problems. 

    Starting sometime in the 2050s, the world’s population outside of sub-Saharan Africa will stop growing and then slowly decline. All of the world’s net population growth will then be in Africa. How soon the world reaches zero population growth will depend critically on how fast birthrates decline in Africa.

    By 2100, Africa could have about as many people as Asia, about 4-5 billion. Together, Africa and Asia in 2100 could have about 80% of the world’s population.

    Throughout large parts of the Middle East, Africa and Latin America, governments have not been able to provide effective management of economic development for their young, growing population, which have high rates of unemployment and underemployment. Many of the governments are corrupt and/or repressive without free elections or civil liberties. Political activism, partly caused by stagnant or declining standards of living and lack of economic opportunity for young workers, commonly takes the form of mass protests and street demonstrations, aided by Internet social media. Governments typically react with riot police and the military, arrests, torture and prisons, rather than economic and political reform.

    THE DEMOGRAPHICS OF SPECIFIC REGIONS AND COUNTRIES

    A recent survey concludes that 46 countries have declining population or will have declining population in the near future. Declining population is already true in Japan (see below) and Russia and is about to be true in central and eastern Europe. South Korea, also with an extremely low birth rate, is looking at a demographic future similar to Japan’s (see below). South Korea’s current population of 51 million is expected to decline to about 30 million in 2100.

    Russia’s population is declining. Male life expectancies in Russia have been going down for decades but might have recently stabilized. While birthrates are below replacement, the decline of the national population has been offset in recent years by immigration. But lower rates of immigration in 2018 and 2019 have led to large decreases in population. The UN projection is that Russia’s current population of around 146 million will fall to about 85 million by the end of the century. 

    Because of very low birthrates and out-migration, central and eastern Europe is looking at population declines in this generation.  Some UN projections show that most countries in central and eastern Europe might have even larger total percent declines than Japan by the end of the century (over 50%).

    Western Europe is further along the population aging curve but because of immigration of younger people, the decline will not be as precipitous. And western Europe, like Japan, currently starts with more resources to support an aging population.  But high structural unemployment rates, low economic growth, restrictive labor laws and generous early retirement benefits will strain western Europe’s ability to grow and maintain current social welfare levels. A few European countries realize that current levels of social welfare are not sustainable and have begun reviews of retirement and health care programs. This problem is exacerbated by the currently high unemployment and underemployment rates among younger employees.

    China, which has enforced a “one-child” program since the 1970s until 2016, has a very low birthrate of about 1.6. Although this program has been relaxed in recent years, the national birthrate remains far below replacement. China currently has a young average-age population but the average age is rising very rapidly. 

    China’s working-age population began shrinking in 2012.  By around 2050, the decrease will be about the size of the current U.S. total labor force. Next year, the median (half above, half below) age in China will pass that of the United States. By around 2045, the percent of China’s population over the age of 65 will be about equal that of the United States. 

    A mature, experienced workforce should help maintain high but falling economic growth rates for another generation. After about 2050, demographics will begin working against Chinese economic growth. 

    China will grow old before it becomes rich (high per capita income). Even after decades of spectacular growth, per capita income is still about one-third to one-fourth that of South Korea and Japan. Even worse off are the economies of Southeast Asia, with per capita incomes below China, similar birthrates and rapidly aging populations.  

    Given current political strains and a large Chinese population outside of China, it is possible that China will have larger net outmigration in the future.

    DEMOGRAPHICS AND ECONOMIC GROWTH

    The following accounting identity shows the sources of economic growth. An accounting identity says nothing about causality, assumptions or feedbacks. But it introduces some general issues.

    The economic growth rate of a country roughly equals the growth rate of the labor force plus the increase in productivity (output per member of the labor force).

    If the labor force numbers are stable, all of the increase in output depends on the increase in productivity. The pressure on productivity is even greater if the labor force numbers are decreasing. So, for example, if a labor force is increasing at about 1% per year and productivity is increasing at about 1% per year, output will increase about 2% per year. If the workforce stops growing, productivity would have to double to 2% to yield the same economic growth. If the workforce were to decrease at 1% year, as it is in a number of countries already, productivity would have to increase 3% a year to achieve 2% economic growth. This is a high productivity growth rate for a developed economy.

    There is a small amount of research that suggests that an aging labor force is one cause of slowing productivity growth.

    Low rates of productivity growth with accelerating rates of labor force and population decline could lead to less output (negative growth rates) and declining standards of living.

    A member of the industrial/information workforce today is better educated, with new skills, compared to a member of the labor force a generation or two ago. The difference should show up in an increase in labor productivity. Increase in total factor productivity will be due to innovation in capital equipment – including information technology, robotics and artificial intelligence algorithms – and demand for employees with new skills and knowledge. Other factors are public investment and organizational innovation. But these changes have not shown up in productivity measurements. Productivity growth rates are low, although I suspect that the methodology used to compute these figures underestimates the gains.

    Demographics are heavily influencing the areas of investment in wealthy countries; these sectors will drive future economic growth. The three most active areas of research and net investment are robots and AI (reaction to declining workforce), driverless vehicles (same), and biotechnology (health care for an aging population).

    Demographics also influence the demand side of economies. The changing age structure of the economy influences the “market basket” of consumer spending. Certainly the large increase in the number of senior citizens (and their income) is having a major impact on health care spending. To say nothing about the increase in demand for tourism, gambling and south Florida real estate. (I once predicted that marijuana would be legalized when a large number of baby boomers became 65 and older.)

    An aging population is not necessarily bad for economic growth. A healthy population beyond retirement age is leading in the United States to an increasing percent of senior citizens remaining in the work force. With a rising percent of the population over 65 and living longer, health care is a growing percent of output. The health care sector is very innovative, which is a source of economic development and thus economic growth. 

    Companies use demographic information when planning marketing and advertising strategies. Changing demographics are analyzed when developing new products, changing product mix, and segmenting markets. The explosion of detailed demographic information about smaller and smaller segments, including individuals, combined with online marketing technology, is revolutionizing marketing and advertising.

    Areas of the world like Africa face the opposite problem. Working-age population will increase rapidly for a generation or two. But unemployment rates may be high and marginal productivity may be close to zero, or negative in rural areas. With high growth rates of population, economic growth rates will have to be high – over 6% per year – for a sustained period to raise real per capita income (standard of living) and reduce unemployment.  

    IMPLICATIONS FOR ECONOMIC POLICY

    The standard economic models demonstrate that the demographic changes we are seeing are a function of economic growth and development. Industrializing, better educated, urbanizing populations have declining birth rates. But the experience of the poorer regions of the world tends to indicate that these demographic changes are occurring even without economic growth and development.

    Although wealthier countries concentrate on the costs of their rapidly growing retired population, for most of the world the critical question over the next two generations will be how to accelerate economic growth to provide jobs and opportunity for the growing working age population.  The related challenge is how to improve education, training, and economic opportunity to raise standards of living now to provide the resources for the aging population in the future. 

    For the entire world, these objectives are complicated by how to pay for the social costs of past industrialization and environmental degradation, and the future costs of climate change.

    Increasing population and rising real income in emerging economies, especially in Asia, are increasing the demand for energy. China, which had no privately owned cars in 1979, is now the world’s largest automobile market. A dramatic increase in the number of cars is the main reason for the continuing increase in the global demand for oil.  Increased demand for electricity is being met largely with new power plants burning fossil fuels. For at least another generation, these trends will make it difficult to meet global goals to drastically slow down or stop global warming.

    Demographics is interacting with climate change in another important area – food production. Many scientists believe the most serious effect of climate change will be its impact on food production. Global warming and more extreme weather events will make it more difficult to expand food production using current technology. As in other areas, trend projections can be changed by the development of new techology.

    In the long run, the positive side of declining global population will probably be less demand for resources. Combined with substitute technology, global warming might slow down or stop. Climate change might not have quite the devastating effects trend projections indicate.

    The advanced and industrialized countries with stable or declining populations and workforces will have to consider the following:

    Economic growth will have to come from large increases in productivity (output per member of the workforce). To achieve this, and also meet social welfare costs, most countries and regions such as the European Union will have to make radical changes in economic policies. Particularly disruptive and contentious will be the adoption of automated factories and offices. On the positive side they will increase labor and total productivity; on the negative side they will probably eliminate or “deskill” a large number of existing and future jobs.

    Large increases in retirement age populations is leading to serious underfunding of public and private pension funds. Taxes to fund public pension funds are rising rapidly, both in amount and as percent of government budgets. Despite this, unfunded liabilities – promised future benefits not covered by projected future revenue from taxes – are also rising rapidly.

    Multinational corporations will develop and adopt the new technology. Countries that do not have quality education, encourage innovation and change economic incentives will not be able to attract investment and compete in the global economy. And their best educated and most motivated people may go somewhere else, as is happening in eastern Europe and many developing countries.

    On the other hand, poor countries with decent transportation, energy and communication infrastructure will probably attract foreign investment. Real wages of at least part of the labor force will rise.

    Attitudes towards immigration might change from the current restrictive policies of some countries. Attracting “human capital” will be just as important as attracting investment capital. Trans-border movement of people will increase. New national, regional and international agreements will have to be negotiated.  Remittances back to the home country will be a more important part of the economy of many countries and global capital flows. 

    Attitudes about work, labor laws, retirement and retirement ages will change. The benchmark age of 65 was arbitrarily set by Bismarck almost 150 years ago when less than one percent of the German population lived that long. When the United States adopted Social Security, life expectancy was 56 years. The life expectancy of America’s younger workers is already over 80 years.

    DEMOGRAPHICS AND PUBLIC ECONOMIC POLICIES

    If the labor force is not growing or actually shrinking, as it is in most industrialized economies, and the non-working population is growing, one consequence is likely to be growing government budget deficits. Growing government deficits as a percent of GDP may be a function of no economic growth or slow economic growth, not the other way around as suggested by economic research.

    It is how a government spends its income, more than the size of the deficit, that matters. Public investment substitutes for stagnant private consumption spending. Investment, both public and private, substitutes demand for innovation for demand for existing goods. This could increase productivity and result in new products and services. Economic growth then will depend on high levels of new technology and increased productivity (output per employee).

    JAPAN AS A POSSIBLE MODEL (OR WARNING) FOR INDUSTRIAL COUNTRIES

    Figures are from The Economist, “Japan’s economic troubles offer a glimpse of a sobering future,” December 5, 2019.

    Japan is a possible model for the future of other wealthy countries. Japan has a shrinking population and workforce. This will continue. It is not surprising Japan leads the world in developing and installing robots. Robots and AI are also alternatives to immigrants. Japanese companies export capital and technology. Facing falling population, Japan is slowly increasing the number of foreigners allowed into Japan on temporary work permits. But the number remains small, below 1%.

    Japan’s real GDP has been basically stagnant (about one percent per year) over the last 30 years. Without immigration and structural changes to Japan’s political and economic system, Japan’s real GDP in the future will grow slowly at best and eventually decline along with its population. In the long run, Japan will continue on its path to demographic and economic self-destruction.

    CONCLUSIONS

    Demographic trends have important consequences for economic growth and public policies. They cannot be seen in isolation. Neither can any of the other major trends. They are interrelated. 

    ·      Rising global population but at lower rates, mostly in poor countries, for the remainder of the century. After the 2050s, all of the world’s net population increase will occur in Africa. Global population may stop growing by the end of the century. 

    ·      Rising population in poor countries makes high rates of economic growth both pressing and difficult. Emigration pressure from poor regions of the world will probably increase unless there are high rates of economic growth.

    ·      Most of the world’s population increase will take place in cities and surrounding metropolitan areas, creating even larger massive urban areas. Large urban areas are increasing rapidly in poorer countries. 

    ·      Static, falling and aging populations in the wealthier, industrialized countries. Static or declining labor forces mean all economic growth will depend on increases in productivity. To counter demographic trends, technological innovation (robotics and software) leading to high rates of productivity growth will be necessary to increase standards of living (real income per person).

    ·      Problems with unemployment and underemployment, stagnant and declining real incomes and income inequality will probably get worse as artificial intelligence and robotics accelerates the substitution of capital for labor.

    Economic development and growth since the beginning of the Industrial Revolution has been aided by large increases in populations and especially the working age population. But in the future, economic development and growth in most of the world will have to occur with stagnant or declining labor forces and aging populations.

    =====================================================
  • Stock Market Investment Primer

    Stock Market Investment Primer

    This primer is aimed at the long-term investor. But this does not mean that you should necessarily hold all of the stocks and funds in your portfolio for a long time.

    WHY STOCK PRICES GO UP

    The movement of a stock index such as the S&P 500 or an individual stock depends on two things:

    Earning per share (EPS) and changes in EPS.

    Stock price/earnings per share ratio (PE ratio) and changes in the PE ratio.

    If the PE ratio stays the same, an increase in EPS often leads to an increase in the stock price. The same is true of a stock index. Rising EPS combined with a rising PE ratio is often the reason why a stock goes up more than the average stock.

    Since 2009, the beginning of the stock market recovery from the last recession, most of the increase in stock prices has been due to the increase in earnings per share (EPS).

    Well, that was easy. Well, not really.

    The stock market is “forward-looking,” that is, it tries to anticipate change, especially change in EPS and the PE ratio. There is a great amount of forecasting. But since the forecasted changes are in the future, they are inherently uncertain. The forecasts of some companies’ EPS are more uncertain than others. Some are very uncertain. For example, the future sales and earnings of a small biotech company may depend on the success of a clinial trial and FDA approval. If one or both fail, the company could go bankrupt. 

    The EPS of a stock can go up for a number of reasons:

    The economy is expanding. This has been the usual situation in the United States and also for the global economy for decades. So there is an upward trend in the economy leading to an upward trend in income and spending. Most companies can usually expect expanding sales and profits (earnings). This is the main reason why you can expect to make money in the long run; it is also one of the reasons why you should buy a stock index fund, either as a mutual fund or an ETF.

    Corporate earnings and EPS are more volatile (bigger percent changes) than the economy’s GDP changes or a company’s changes in sales. Part of the reason is that for most companies, their EPS is leveraged by debt (see below). So, for example, a 5% increase in nominal GDP might lead to a 10% increase in a company’s sales and a 20% rise in earnings per share. The same relationship works in reverse when an economy goes into recession.

    A company’s stock price does not entirely depend on economic expansion or other influences external to the company. Some factors are internal. It may have a successful new technology, successful new products or become more efficient. 

    If you find yourself buying new products or services, you might want to look at the company as a potential investment. The first time you or your tax accountant used Turbo Tax, when you had your teeth fixed with Invisalign, when you bought your first iPhone, when you started looking for “organic” foods, when you go on your first space flight, you might investigate the company behind these new products or services as potential investments.

    A company’s PE ratio depends on the market’s consensus on the rate of increase in the company’s EPS. A company with a higher than average expected EPS growth rate will generally have a higher than average PE ratio. Both the market’s PE ratio and a stock’s PE ratio can change if there is a change in expectations of the future growth rate. A company’s PE ratio and stock price may go down even if its EPS grows but at a slower rate than expected. This is one reason why higher potential reward (percent gain) comes with higher risk.

    Generally, PE ratios rise over a business cycle. Earnings have been growing for a long time and investors expect earnings to continue growing at least as fast as over the cycle. But a large and sudden increase in the market’s PE ratio may indicate that the market has developed a speculative bubble. This increaes the chances of large downturn.   

    OTHER REASONS STOCK PRICES GO UP

    If you are a long-term investor, you might consider investments based on a long-term

    demographic or social change. The aging of the national and global population presents opportunities for certain categories of companies, the most obvious being health care. Some leisure activities, such as cruise lines, should do well. Another trend is that most of the increases in income and wealth is going to high-income households. Companies that sell luxury products to this income group have done well.


    Whether or not a company pays a dividend and changes in the dividend influence the price of a stock. Not all companies pay dividends. On the other hand, some companies have a history of increasing dividends over time. A good strategy if you own such a company is to reinvest the dividend. The company will then pay rising compound interest, which over time can be an important part of the total return of owning the stock. Check to see if the company has rising earnings to cover the rising dividend. There are also ETFs and funds that only contain these types of companies.

    Another way you can make money in the long run is corporate acquisitions. The acquiring company has to pay a premium over the acquired company’s stock price to obtain all the shares. Premiums are usually between 30% and 50%. Certain types of companies tend to get bought out – specialty food producers, local and regional banks, small biotechs with a FDA approved drug or good clinical results. Small tech companies tend to get bought out while still private.

    Companies can influence their stock price through financial planning. One strategy, noted above, is to increase the dividend. A company can also buy back some of its outstanding stock, raising EPS by reducing the number of shares outstanding. Or a company can fund its expansion through taking on more debt. The two can be combined; much of the cost of share buybacks over the last 10 years has been financed by new debt.

    Earning per share is leveraged by debt. Interest rate expense on the debt is fixed. Imagine two companies both making $1,000,000 a year from operations and do not pay income taxes. One has 1,000,000 shares, so its EPS is $1.00/share. The other company has more debt and only 500,000 shares. Its EPS is $2.00/share. Well, not quite. It has to pay interest on the debt, which is subtracted from the $1 million in operating earnings. But typically its EPS is still higher than $1.00/share. And its share price is probably higher. Also, its EPS growth rate will be higher for a given amount of increase in earnings.

    In a period of low interest rates, corporations will tend to take on more debt and buy back shares. This increases EPS. If done over time, this combination of financial strategies might increase the growth rate of EPS and the PE ratio.

    Your long-term rate of return on buying a stock or an index will depend on when you buy the stock or the index. It you bought the stock at the end of a business cycle or bull market and then the stock’s price went down, your rate of return for years might be low or even zero. At the extreme, if you bought a group of stocks like the Dow Jones Industry 30 in 1929 you would have waited until 1953 to get even. On the other hand, if you buy stock at or near the bottom of a market downturn, it is likely that your rate of return for the next 3-7 years will be substantially higher than the long-run average rate of return.

    A word about market downturns. There are two general types – with and without recession. A market downturn not caused by a recession tends to reverse quickly. A market downturn caused by a recession tends to be deeper and takes longer to recover. 

    WHAT SHOULD YOU BUY? AND WHY.

    Should you buy an index fund or ETF, a managed fund or ETF, or individual stocks? The three are not mutually exclusive. You might start with an index fund or ETF; the most popular is an index fund that mirrors the S&P 500 (the 500 stocks with the largest market value). Then you might like a particular industry or a set of similar stocks. It may be difficult for an outside investor to pick potential winners and avoid hyped probable losers. Choose a managed fund. You are paying for their research and their keeping up with changes. But be careful; many managed funds are very similar to index funds. Also, do not chase funds with outstanding recent results. Research indicates that the funds with the best results over three years are likely to exhibit below average returns over the next three years. 

    Index funds and managed funds are good for ignorant investors. Index funds beat most managed funds over the long run, mostly because their costs are lower. If you buy a lot of individual stocks or a lot of specialized funds, you may have a disguised index fund. At a higher cost.

    A few words about index funds. An index fund contains many stocks but they are not equal. The greater the total market value of a stock – “market cap” (capitalization) – the greater the weight of the stock in the index. So right now monster tech companies are the five largest companies in the S&P 500; the ten largest companies account for about 23% of the total market value of the index. To some extent, these and other really big corporations have become very large and very profitable because of innovation and high growth in the past. You are betting they will have higher than average growth in the future. This is a poor bet. If you look at the tech companies that dominated the indexes 20 years ago (or 10 years ago, or 30 years ago), they have been poor investments since then, although a few tech companies have made a recent comeback by getting into new businesses. 

    The indexes contain companies that are losing money and many companies whose sales and earnings growth depend mostly on overall economic growth. If you believe that the U.S. economy is in for a period of low growth, then the rate of return on an index fund will probably be below the historic rate of return. In addition, many of the companies in a market index will be hurt or destroyed by technological change and innovation from new companies.

    The index fund becomes “the market.” You would not buy a managed fund or an individual stock unless you expected your total return (capital gains plus dividends) was going to be greater than the total return of the index fund. This tends to rule out older, mature companies whose sales and earnings depend mostly on the total income growth of the entire economy; the change in their stock prices tend to closely followed the change in the market index.

    Which gets us to the idea of risk. Research indicates that on average 60-70% of a stock price’s movement is correlated with the movement of the market. When you buy an individual stock, you are buying the other 30-40%. The question is:  Why do you think this stock will have higher EPS growth than the market? Or in the words of Dirty Harry, “Do you feel lucky?”

    What kinds of stocks have a chance to outperform the market? One group is sometimes called “disruptor” companies. These are innovative companies that are creating new demand or disrupting existing industries or markets. For example, my beloved local electric utility, whose main service seems to be service interruptions and blackouts, is installing “smart” meters. Who makes the meters? My dentist raves about this new digital imaging system that replaced X-rays and gummy impressions. Who makes the digital imaging system? Again, avoid the stock of companies that are getting hurt (losing sales and market share) by new competitors with new technology or new products and services.

    If you are thinking of buying individual stocks, the warning here is that a good company – a company that you admire – may not be a good stock. I once worked for a very well-run company. But it produces a commodity in a competitive, price-sensitive market. Its earnings vary widely and are unpredictable. Its stock has underperformed the market for decades. It is financial performance that counts.

    =======================================================================

    But first, you have to learn how to make enough income to start saving and investing. See my The 10 Minute MBA – Almost Everything You Need to Know to Manage Organizations, People and Yourself.

    A good place to learn the basics and mechanics of investing in the stock market and other financial markets is the Investopedia website.

    For an analysis of the stock market crash of 1929 and the start of the Great Depression, see my The Stock Market Crash of 1929 and the Beginning of the Great Depression. This essay questions the conventional wisdom that the stock market crash of 1929 “caused” or “triggered” the Great Depression.

    Go back to the Guide for Pages and Posts.

  • Who Do You Fear More, Big Business or Big Government?

    OK, who do you fear more, big government or big business?  

    Historically, Americans saw a relatively small government with regulatory powers as a check on monopoly and big business.  But the rise of big government because of the Great Depression, World War II, the Cold War, and the Great Society changed that.  Americans had a choice.  There was a general consensus that we had to spend a lot of money for national and international security during the Cold War.  But the expansion of the social welfare state and environmental regulations changed attitudes towards the federal government.  The two largest programs of the social welfare state, Social Security and Medicare, have been financed by very large tax increases. These tax increases are somewhat offset by federal income tax cuts.  

    Since the 1980s, there has been a well-financed campaign to roll back the regulation of big business, especially the finance sector. This campaign has been successful.  Most populist outrage, despite the financial system causing a recession, structural unemployment and large federal budget deficits, is now directed at government, as opposed to big business in the past. Attention is focused on the effects, not the underlying causes, which are still there. 

    Limiting government social welfare programs has somehow been tied to even less regulation and oversight of big business.  How did this happen?  

    One reason is that much of the financing of the Tea Party movement and organizations like ALEC come from big businesses and the very wealthy owners and managers who control them. Many of them share the Tea Party and Christian right outrage over lack of government regulation and prohibition of personal behavior they find morally reprehensible.  Somehow, a generalized anger and rage over government protection and even support of this behavior has been channeled to limiting government regulation of business, including rollback of environmental legislation and regulation.

    The logical Republican candidate for president, representing this generalized fear directed as loathing of government, is Donald Trump.

    The American political nightmare in the past has been that big business and big government become partners rather than adversaries. There are exceptions. We accepted it in the areas of defense technology and infrastructure spending. We denounced it if it led to regulatory capture or was a barrier to technological progress. We were angry if we believed that the rich were using government to transfer income from the middle class to themselves.  We seem to have lost this outrage.

    In addition, this cooperation has been raised to new levels with the need for huge sums of money to get elected and virtually no limits or accountability because of the recent Supreme Court decision allowing super PACs. They channel large sums of money to support candidates who tap into widespread fear and anger about American society and government.  These elected officials are also pro-business (reduce taxes on the rich and corporations, less environmental regulation, no anti-trust, no oversight of financial companies) or at least anti-government, which amounts to the same economic policies.

    It really isn’t a question of “getting government out of people’s lives.”  Social conservatives want more government interference in individuals’ lives. It seems to be a question of big business not paying the social costs of a capitalist economic system. It’s a question of getting government out of big businesses’ lives. Regulatory capture has become total government capture.

    The stagnation of middle class incomes and rising income inequality, the threat of widespread unemployment because of automation and AI, and the huge rise in temps and “consultants” without any benefits don’t seem to be major political issues. Why? Who makes the decisions that result in all this? Who outsources jobs to China and threaten American workers with more outsourcing, keeping wages down? Who eliminates pensions and other fringe benefits? Who wiped out home equity for ten million homeowners? Who is buying record numbers of robots to replace workers? Large corporations, most of which are multinational companies. The result? Record profits and bonuses even in a period of slow economic growth. This is a major reason for the redistribution of income from the middle class to the rich. No wonder the rich are willing to spend a great deal of money to protect this trend from possible government interference.

    And deflect blame. President Trump reflects the belief that America’s economic and employment problems are due to illegal Mexican immigrants and “China.” “China” doesn’t export to the United States; multinational corporations and Chinese companies do. About 60% of imports from China come from American and foreign multinationals. Much of the exports of Chinese companies are part of the global supply chain of American companies.

    Perversely, the debate seems to be centered on conservative attacks on the increased cost of programs like unemployment benefits, disability benefits, Medicaid and Obamacare, nutrition aid for poor mothers and infants, and food stamps.  Programs for the poor, sick and unemployed.  Major reductions in social welfare and social safety net programs are at the heart of Republican budget proposals. These cuts are necessary to keep the Bush and Trump tax cuts for upper-income families and corporations without increasing the yearly deficits.   

    The only realistic way smaller deficits will happen, let alone a balanced budget, is a combination of strong economic growth – creating strong growth in tax revenue – and tax increases, mostly disguised as eliminating deductions and subsidies.

    The Republican rhetoric about smaller deficits is ideological cover for slashing social welfare and other programs that conservatives oppose. 

    For the first time in American history, populist anger is aimed at government, not big business.  The federal government is seen as supporting programs and groups that are anathema to conservatives. Big business has supported this attitude in return for support for pro-business policies. You could call this ideological capture.

    The situation is made worse by a zero-sum mentality. In a world of low growth and increased fear and insecurity, there is less room for compromise. There is widespread middle class perception that minority groups and the poor are getting unfair amounts of social welfare benefits that come out of middle class taxes. This is ironic since the two largest social welfare programs are Social Security and Medicare, which overwhelmingly benefit the middle class, and the lower half of the middle class do not pay any income tax. And, sadly, we seem to be losing any sense of shared community or compassion for others. 

    We are seeing government in a period of disruptivd social and economic change.  Over the last 50 years, we have become a more tolerant, open and inclusive society. One result of this is behavior and culture that many people, not just conservatives, find distasteful or immoral. Combining this moral outrage with economic insecurity and a fear of the loss of power and status, is a potent political combination. The irony is that conservatives want to use the coercive powers of government to limit or outlaw some of these consequences.