Author: Bennett Greenberg

  • Martin Luther King

    Martin Luther King


    Martin Luther King, Jr.

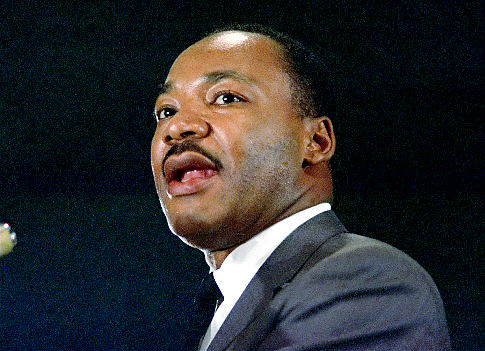
    Yesterday we celebrated the life and, unfortunately, the violent death of Martin Luther King, Jr.  What we seem to have forgotten is the vision he had of a better America.  Dr. King’s larger vision was an America free from the scourges of racism, violence and poverty.  He realized that the means to this end were just as important as the ends.  They were the opposites – nonviolence, solidarity, and an appeal to all Americans to believe in the political ideals and moral values on which this country was founded.


    Like another great American at a time of national crisis, Dr King appealed to “the better angels of our nature.”  And in some ways, this has happened.  We are a more tolerant society than we were in 1968.  But there has been an ongoing political backlash, fueled by a rhetoric of fear, anger and hate.  Reverend King would be appalled that a national political leader would overlay the crosshairs of a rifle scope on pictures of political opponents.


    Like his father, Martin Luther King, Jr. was a Baptist minister.  “We Shall Overcome” was adapted from a popular hymn.  At its roots, the civil rights movement was based on the teachings of another preacher who spoke out against the brutal and oppressive Roman regime in the province of Judea. He added to the cries of earlier prophets for justice and mercy a new message of love, hope and compassion for the poor.


    But I think Martin Luther King would be heartened by another development.  As in Tunisia recently, people have organized and taken to the streets to nonviolently protest their oppressive governments.  How could anyone in 1968 have predicted Nelson Mandela, Lech Walesa, Vaclav Havel, the Tiananmen Square protesters, Aung San Suu Kyi and millions of others who had the courage to defy their violent governments?  Not all succeeded.  But, unexpectedly, many did. 


    For those who stand up for a more peaceful and just world, even when they fail, they can take heart from the words “Deep in my heart, I do believe, We shall overcome someday.”

  • Implementing Foreign Policy:  Issues and Strategies

    Implementing Foreign Policy: Issues and Strategies

    THE BASIC PROBLEM

    The most important fact about international relations is that the United States is the only global power.  Unlike China, Iran or Russia, the United States has to deal with foreign affairs everywhere in the world.  At the same time.  Although possessing huge resources, these resources are not unlimited.  

    The American president has to make two sets of related “economic” decisions – how to allocate foreign policy resources among many possible combinations of objectives, and the mix of resources in pursuing each objective.  The temptation is to rely solely on America’s powerful military.  But even this simple strategy has limitations, as experienced by failure in Vietnam, Lebanon, Somalia, and Afghanistan. The military success in invading Iraq was followed by the bungling of the “morning after” occupation that resulted in Iran dominating Iraqi politics and many officers of the disbanded Iraqi army joining ISIS.

    The level and mix of resources – military, diplomatic, economic, political, ideological – brought to bear on one political problem affects the resources available for other problems.  Committing most of America’s front-line military resources to fight in Iraq reduced America’s ability to react to threats elsewhere, especially in Europe and Afghanistan. It probably delayed focusing on the looming threat of China.  Deploying a carrier group in the Persian Gulf meant it was not available to defend the Strait of Malacca or challenge China in the South China Sea.

    Each game, each competition, cannot be played in isolation. They are all connected, as the past and current geopolitical thinking in terms of all of Eurasia makes explicit. There are feedback effects from actions in one area of the world on other areas. There are constraints on strategy with future (uncertain) payoffs.

    There are overall resource and cost constraints.  Paul Kennedy wrote an influential book on the dire consequences when the cost of foreign commitments of powerful countries outruns their resources.  The United States cannot run large budget and trade deficits forever and expect the rest of the world, especially China, to loan us the money to pay for our expensive military and intelligence operations.

    PRESIDENT OBAMA LEARNS TO THINK LIKE AN ECONOMIST

    President Obama inherited foreign relations in shambles.  The war in Iraq had degraded
    America’s military capacity to respond elsewhere and promoted radicalism in the
    Middle East.  A review of our relations
    with Pakistan, Saudi Arabia and Iran was long overdue.  Europe and NATO were neglected, with no clear strategic objectives.  Potential regional hegemons such as Turkey
    and India were ignored.  We did not see
    how China’s economic resurgence would finance a return of traditional Chinese
    foreign policies in Asia.  President
    Bush’s response to the challenge of Vladimir Putin was naïve at best.   

    President Obama learned that he could not deal with every
    foreign policy challenge with the optimal set of resources. There were tradeoffs. Resources committed have to be proportional
    to the importance of the objective.

    THE LONG RUN GAME

    There is another consideration.  It is important for the American president to
    realize that the game never ends. 
    America, more than any other country, has to play a complicated, long
    run strategy.  A skillful set of foreign
    policies must consider how decisions made today affect the future.  Sports analogies are misleading.  There is always a “morning after” to any
    “Mission Accomplished.”  The game doesn’t
    end.  The collapse of the Soviet Union
    did not mean that traditional Russian geopolitical objectives disappeared. The U.S. will never defeat the Taliban as long as there are sanctuaries in Pakistan.

    When President Obama assumed office, he was fond of using
    sports metaphors to describe foreign policy. 
    In an article in The Economist, he used the metaphor of
    a relay race to describe foreign policy. 

    The United States, unlike other countries such as Russia and
    China, must find the right combination of Realpolitik
    and ideological objectives.  This was
    easier to do during the Cold War.  Now
    the United States should continue to promote democratic ideals without seeming
    to use its military and political power to impose its will on other
    countries.  The overseas perception of
    how well America’s democracy is functioning, how well it deals with economic
    and social change, is an important part of foreign policy. Again, the United States is playing a long
    game.

    Supporting democratic ideals and democratic groups around the world has become complicated in the post-Cold War world. Supporting groups like Solidarity was easy; supporting democratic opponents to repressive or autocratic regimes that are nominal political allies of the United States is more complicated. If democratic ideals, institutions and groups are destroyed by repressive, autocratic and right-wing populist regimes, can America survive as an influential global power?

    The United States has to recognize that there are limits to
    its influence.  Other groups and
    countries just see the Realpolitik or
    even a new form of imperialism.  Arrogant
    statements followed by military action or threats often lead to long run
    problems and lack of credibility. Bombing with drones is easy.  Using patient
    diplomacy, economic sanctions and other foreign policy tools that don’t have an
    immediate payoff is difficult to implement and often difficult to explain.

    DOMESTIC POLITICAL INFLUENCES AND CONSTRAINTS

    It is tough to conduct a patient, long run foreign policy in
    a democracy, especially when an increasing number of adults suffer from
    political A.D.D., also known as cable newsitis. 
    Sometimes the immediate policy alternatives are bad, worse, and
    disastrous.  Sometimes the best
    alternative is to do nothing.  Sometimes,
    wait to see how things develop and decide how to act later.  Political opponents will criticize the
    president for being weak or soft.

    In a democracy, there are domestic political constraints
    that can’t be ignored or silenced.  Many
    Americans have emotional ties with other countries and will protest and lobby for
    that country if they object to American policy. 
    Cuba and Israel come to mind; Americans of Polish descent may become a
    domestic pressure group if Russia threatens Poland. It remains to be seen how a large Latin American population will affect U.S. attitudes and policies towards Latin America.

    More Americans are blaming their personal economic difficulties on the global economy. New actors such as American multinational corporations and issue-oriented NGOs (non-governmental organizations) are also trying to influence American foreign policy.

    Domestic political and economic policies have international consequences. For example, energy mix and carbon emissions. If America reduces carbon emissions, then foreign policies and influence in this area will be credible. If not, America loses leadership in this critical global area. The same is true in related national policies to deal with other aspects of climate change.

    In the modern world, economic and political factors are
    intermixed.  Trade agreements have been
    as much about political objectives as foreign trade.  The Trans-Pacific Partnership is as much
    about containing Chinese influence in Southeast Asia and strengthening
    political ties in Latin America as it is in promoting world trade.  The proposed trade agreement with the
    European Union, and a similar agreement with Britain, is a key move to holding
    the European alliance together.

    THE FOREIGN POLICY DEBATE

    The question debated in the last presidential election was whether or not Americans are still willing “bear the burden,” pay the cost,
    of being democracy’s premier power. 
    There was isolationist rhetoric not heard since the 1930s.  Many Americans, maybe a majority, seem to
    believe the global engagement costs to the United States are greater than the
    benefits, however difficult to define and defend in the post-Cold War world. 

    If the United States becomes more isolationist and
    protectionist (economic nationalism, threatening virutally every major trading partner with tariffs and trade restriction), there will be political and economic consequences.  Trade, and American multinational
    corporations, are vulnerable to retaliation. 
    Ambitious leaders of other countries would love to fill the political
    and military vacuums America leaves behind.

    Increasingly dysfunctional domestic political and economic
    institutions affect the resources and long range focus necessary for foreign
    policy.  There are other countries
    throughout history that have turned from looking outward to looking inward, to
    disengage from the rest of the world. Huge Chinese fleets dominated Asian waters as far as the east coast of Africa in the early 1400s. Then China became isolationist. By the early 1500s, these waters were increasingly dominated by Europeans. Eventually the Europeans reached China, leading to and contributing to the colonial carving up of China, civil wars, widespread use of opium and the disastrous Communist regime. Over 100 years of violence and suffering. It is a logical contradiction for a regional or global power to be isolationist.

    ====================================================================


    For an earlier, related discussions, see


    President Obama is Still Trying to Save American Capitalism and Global Influence

    President Obama Learns Some Game Theory

    For a list of posts and economic tutorials in Pages, see Guide to Posts and Pages.


  • The World Turned Upside Down:  The Uselessness of Conventional Economic Wisdom

    The World Turned Upside Down: The Uselessness of Conventional Economic Wisdom

    There is a story, possibly true,
    that when the British surrendered to American and French forces at Yorktown,
    effectively ending British rule of America, someone in the British army sang or
    played an old English folk song, “The World Turned Upside Down.”   (See
    https://en.wikipedia.org/wiki/The_World_Turned_Upside_Down)

    I think I know how the British felt.  Many of the assumptions economists have made about
    economic reality and economic policies now seem out-of-date or even reversed.

    UNITED STATES

    The Fed fought inflation; now it
    sets inflation targets when there is no inflation.

    The Fed worries about deflation even
    though the major source is a fall in energy and commodity prices. Another source is the fall in the prices of technology products.

    There is a large increase in the money supply, large government deficits, a large trade deficit, and a large decrease in the unemployment rate. Economic theory and past experience says that there should be an increasing inflation rate. There isn’t.

    America is experiencing a long
    period of real economic growth without inflation.  Unemployment is as low as realistically
    possible.  Rather than rejoicing,
    economic, business and political commentators seem to believe there is
    something fundamentally wrong with this.

    Since the end of World War II, a key
    part of American foreign policy has been the expansion of free trade.  Now presidential candidates of both parties,
    and over half the American people, want to reverse free trade.  Economic nationalism is rising at the same
    time as large American corporations are about to receive over half their sales
    and profits from overseas operations.

    America worried about importing too
    much oil; now America is worried about producing too much oil.

    Interest rates are important because
    they are the price of capital, which determines how capital is allocated.  Now interest rates are a policy tool of the
    Fed.  They are artificially low with no
    thought about how they are affecting capital allocation.

    The stock market was a place where
    companies went to raise new capital. 
    Now, through massive share buybacks, it is a place where companies
    reduce equity capital.

    It has been government policy that
    annual budget deficits are manageable as long as the national debt-to-nominal
    GDP ratio was low.  That is, as long as
    the national debt rose at a lower rate than nominal GDP.  But since 2008, the national debt has risen
    much faster than nominal GDP.  We are
    experiencing historically high and rising peacetime national debt-to-GDP ratios.  So far, there has been little consequence
    because of historically low interest rates. 
    If nominal interest rates rise, there will be larger budget deficits. 

    Seven years into a recovery interest
    rates and inflation rates should be rising. 
    No one could conceive that central banks in the U.S., Europe, Japan and
    other countries would set zero short-term interest rates this far into the
    recovery.


    Negative interest rates, both real
    and nominal, were considered possible but not realistic.  Most industrialized countries have had some
    negative interest rates.

    The Fed stopped looking at the
    increase in the money supply as a policy tool about 30 years ago.  Now a huge increase in the money supply is
    being used to finance a huge increase in the national debt.

    Tax cuts and a larger deficit are traditional tools to fight a recession. They are being advocated as sound fiscal policy at the top of a business cycle.

    An economy can be in recession if
    private spending is too low (inadequate private aggregate demand).  This implies private saving is too high.  The solution is that government spending
    should be increased and/or taxes lowered. 
    The result is a larger government deficit, which is financed by private
    saving.  But with structural deficits at the
    national and state levels, private saving now has to be high to finance
    government deficits. Also, the United States has to continue to take in a high percent of cross-border financial flows.

    CHINA

    By some measures, using purchasing
    price parity (PPP) measurement, the Chinese economy is as big or possibly
    larger than the American economy. 
    (Although many analysts believe the past growth rates and the real
    economy of China are overstated.)

    China has over half of the world’s
    high-speed railroad trackage and intends to increase it by two-thirds over the
    next 10 years.  By 2025, China intends to
    have every city in China with a population of at least a half a million to be
    connected to the high-speed rail network. 
    The point?  China spends substantially
    more on infrastructure than the United States does, and China uses more
    advanced technology. 

    The U.S. high-speed rail
    mileage?  Zero.  Japan has offered to give the U.S. its
    high-speed rail technology.  I think
    that’s called foreign aid.

    China is planning a high-speed
    railroad that will take passengers and freight from Beijing to Moscow in 33
    hours and London in 48 hours.  Some
    sections of the railroad have already been built.  The geopolitical idea is to bypass American
    control of the world’s shipping lanes.

    China has four times as many
    skyscrapers as the United States.

    China has most of the long and high bridges in the world.

    China has more cars than the United
    States. China has more smartphones.

    China produces most of the world’s solar panels. On the other hand, China emits more carbon into the atmosphere than any other country.

    GLOBAL

    Recessions were caused by rising
    global commodity prices.  Now there is a
    fear that a global recession could be caused by falling commodity prices and
    their longer-term consequences.

    In the post-WWII period, there had
    never been a global recession.  Until
    2007-2009.

    At Japan’s current rate of economic growth, their economy will double in size in 100 years. But by then there will be very few, if any, Japanese.

    Almost all countries are experiencing rapidly rising national debt-to-nominal GDP ratios.  Economic history indicates bad things start to happen if the ratio goes over 90%. Many countries, including the U.S., are over 100%.  Japan has the highest ratio at 230%, a ratio no one thought could be possible without catastrophic economic consequences.   But this high and rising ratio is made possible because Japanese families are apparently willing to lend their government unlimited funds at zero interest.

    For decades we have been told that
    we are running out of oil.  Now we are
    told there is too much oil.  Proven reserves
    have been greatly increased and because of improving drilling technology oil
    can be extracted at lower and lower marginal and average cost.

    For four decades, Americans have
    been told that nuclear energy is bad and dangerous.  Now the world is planning on building
    hundreds of nuclear power plants using new technology. This is a major strategy to reduce global
    warming. But not in the United States.

    Electric engines in cars will reduce carbon emissions and slow global warming. Unless the electricity is generated by burning coal or other fossil fuels.

    The world faced a Malthusian future
    of exponential population growth caused by high birth rates, not enough food, and
    the depletion of energy and natural resources. 
    Since then, most of the world has birth rates below replacement and the
    rest of the world has falling birth rates. Industrial countries worry about
    future declining populations and labor forces. 
    Food production has undergone a series of technological revolutions that
    has greatly increased the quantity, if not the quality, of food.  Energy resources are almost unlimited with
    even more technological revolutions on the horizon.

    Since the 1950s, Americans have been
    hearing how other forms of political economy would overcome the U.S.  First 
    Russia, then Germany, then Japan, then
    the Four Dragons of Asia.
        Behind all these predictions was the description
    of the advantages of socialism or state capitalism over our relatively autonomous
    capitalism.
     Commentators suggested we
    adopt some of the government planning policies of these countries.
      We didn’t.  These countries and their economic systems
    turned out not to be a threat to us but they are a warning to China.

    MORE CONVENTIONAL WISDOM

    Red wine, dark chocolate, and beer
    were bad for your health.  Now they are
    health foods.  This is my idea of
    progress!

  • A Note on the Geopolitics of Oil

    A Note on the Geopolitics of Oil

    Saudi Oil Minister

    BACKGROUND INFORMATION

    Oil is measured in barrels.

    A barrel is 42 gallons.

    Total global daily production is around 96-97 million barrels/day.

    Saudi Arabia, Russia and the United States all produce around 10
    million barrels a day.  With their
    allies, these three countries account for close to 40% of global production.

    Because of the improved technology of shale oil
    production, U.S. output has gone up almost 5 million barrels/day since 2008.

    Currently, total global production is greater than total demand by
    somewhere between one and three million barrels/day.

    There are record amounts of oil in storage.

    A small percentage increase of supply over demand has led to a
    large decrease in price.

    In the fall of 2014, a barrel of oil cost about $100/barrel.  Last month the price fell to around
    $30/barrel.  Since then, it has rallied
    to around $40/barrel.

    THE ECONOMICS AND GEOPOLITICS OF OIL

    The economies of seventeen countries critically depend on oil
    production and the price of exported oil.  Many others, like Brazil and Mexico, partly depends on oil exports.

    It has been a year and a half since the price of oil began to
    fall.  Many countries are now in
    recession.  Government revenues, mostly
    dependent on oil sales, have fallen drastically and budgets are showing large
    deficits.  In some countries, including Venezuela and Nigeria, the situation is serious enough to threaten the stability of the
    country.

    Given global inelastic demand, a small percent decrease in global
    supply, around 3%, would lead to a large increase in price, probably around
    60-100%.  All countries, including Saudi
    Arabia, would be economically better off. 
    Many other oil producers, but not Iran, have called for lower
    production.  So why hasn’t it happened?

    Saudi Arabia and its Persian Gulf allies have had a number of objectives
    in pumping out a record level of oil and watching the drastic fall in price:

    •         Punish Iran, a Shia rival for power in the Persian Gulf and
      throughout the Arab world.  Saudi Arabia
      is Sunni.
    •         Punish Russia for supporting Iran and then Syria.
    •         Stop the growth of shale oil production in the United States.
    •         Drastically reduce the level of global capital investment in oil.
    •         Reduce production of high cost oil by making it unprofitable
      to continue production.

    Two geopolitical changes in the last 18 months have hardened Saudi
    Arabia’s determination to produce record amounts of oil:

                        Lifting of economic sanctions
    against Iran

    Saudi anger at the U.S. in
    supporting the end of sanctions.

              Russian military intervention
    supporting the Shia regime in Syria

    Both events strengthened Saudi Arabia’s intentions of punishing
    Russia, the United States, and Iran by keeping production at record levels and prices
    low.  If Saudi Arabia and their Gulf
    allies agreed to reduce production and prices rose, the U.S., Iran, and Russia
    would benefit.

    THE SAUDIS MISCALCULATE

    The Saudis have not succeeded in meeting their goals as much or as
    quickly as they expected.  The overall
    strategy was to force other countries to cut back production of unprofitable
    oil and the Saudis and their allies would benefit from their high output and
    higher prices.

    They miscalculated.  Like
    Saudi Arabia, most of the oil is pumped by government-owned or government-controlled
    companies.  They don’t care about
    profits, only revenue.  Government oil
    companies are a source of power, employment, patronage and corruption.  Except in the extreme where less revenue
    threatens the regime, these countries have no incentive to reduce output.  A substantial reduction will lead to higher
    market prices; other countries or companies will maintain or increase
    output.  Without widespread cooperation,
    the end result will be the same total output and the same low prices, except
    the countries that reduced output will lose market share and end up with even
    less revenue.

    The only hope is that major producers, both OPEC and non-OPEC, can
    get together and agree to a collective reduction in production.  A meeting is scheduled in Qatar on April 17.  Saudi Arabia and Russia say they will attend
    the meeting; U.S. oil companies probably won’t. 

    Iran won’t attend and says it will increase production regardless
    of what other producers do.  They have
    softened their position by recently saying that if they are allowed to increase
    production to some unspecified level, they will stop any further increase in
    production.

    What changed?  Why is Saudi
    Arabia signaling it might reduce output?

    Internal pressures.  Fragile society with suppressed
    tensions.  Kept together by a huge social
    welfare system financed by oil revenue.  The
    Saudi government is running a large budget deficit which is rapidly reducing its sovereign wealth fund that finances the lost revenue.

    Saudi would be the “last man standing” but it
    might be a Pyrrhic victory.  The price
    might be too high.

    The Russian economy is really hurting.  A continuation of low prices for oil and
    natural gas could eventually threaten Putin’s power.

    Clear signal to Saudis that they want, or need,
    an end to low prices.  Given the
    continuing economic pain at home, Putin appears willing to cooperate with Saudi Arabia – the geopolitical rival of its client states in the Middle East – in exchange for a stable domestic economy and increased government
    revenues at home.

    A third miscalculation.  U.S.
    shale production hasn’t gone down anywhere near as much or as fast as the
    Saudis expected.  Two reasons:

    Private companies look to marginal costs and
    shutdown expenses, not average cost, in deciding whether to continue
    production.  Reacting to low prices, they
    have lowered their costs and reduced their losses. 
    American drillers adapted to lower prices by shutting down low-producing wells, using new technology to increase output per well, reducing drilling costs by drilling deeper and faster with fewer workers, and forcing suppliers to reduce their prices to producers.

    Until first quarter of 2016, many oil producers
    had locked in higher selling prices through futures contracts.

    American oil executives are saying that in the better shale oil
    areas, new wells can be profitable at $30/barrel.  Oil experts believe that at $45-$50/barrel, total
    U.S. shale production will stop falling. 
    Above $50/barrel, U.S. shale oil production will increase again. 

    Some countries may not cut production as promised.  U.S. shale producers can offset a reduction
    in total supply.  In that sense, the
    U.S., not Saudi Arabia, has become the swing producer.

    Both U.S. and global inventory are at record levels.  Even if production falls three million
    barrels a day, inventory drawdowns can make up most or all of the
    decrease.  Total supply would
    remain at current high levels and prices would fall again.

    THE RECENT PRICE INCREASE

    The futures market and speculators have driven the price of oil
    from around $30/barrel to $40/barrel. 
    Little has changed from the underlying supply/demand balance that drove
    the price from $100/barrel to $30/barrel. 
    Why the increase?

    Speculators look ahead.  Like
    gamblers at a roulette wheel, they pick a number and “puts down their money and
    takes their chances.”   They are betting
    that the major oil producers have reached the panic point and will agree to
    reduce production on April 17.  They are also covering short positions  These actions increased the world price of oil.  But, as the
    above comments indicate, only temporarily.


    THE UNITED STATES:  NAFTA IS THE NEW OPEC


    The United States is poised to become the world’s largest producer of oil and possibly  the world’s largest exporter of refined oil products. Combined with a fall in domestic demand for refined oil products because of electric and hybrid vehicles, the United States could become a net exporter. All of America’s remaining import needs could be filled by Canada and Mexico. Already, the United States does not need any Middle East oil. One reason for past American involvement in the Middle East no longer exists. The main economic reason for an alliance with Saudi Arabia no longer exists.


    The United States controls the technology of shale production. This technology is vital to opening new fields and recovering residual oil in old fields. It is also a geopolitical weapon. Currently, U.S. sanctions against Russia includes withholding oil drilling technology. 

    Related, the United States is already self-sufficient in natural gas, exporting to Mexico, and building liquid natural gas (LNG) plants for export. To reduce dependence on Russia, Poland and Lithuania are building LNG receiving plants. Poland is considering a pipeline from its LNG plant to Ukraine. The United States, plus new natural gas finds in the Mediterranean and shale fields in Poland and Ukraine, could replace much of the Russian exports to Europe.   

    CONCLUSION 

    The geopolitics of oil complicates the economics of oil. Inelastic demand for oil implies that a small percentage decrease in output will lead to a large percentage increase in price and revenue. But geopolitical rivalries make cooperation difficult and probably temporary.  Some of these rivalries have an overlay of intense religious or historical animosity. Virtually every OPEC member has a history of cheating on production quotas. And now any reduction agreement can be countered by increased output in the United States, Canada, and Mexico.

    Oil prices are the result of a complicated interaction of political and economic factors.  Oil buys power and influence.  Saudi Arabia is betting that they can use their oil policy to reassert some control over the tangled conflicts in the Middle East.  Russia hopes that oil and natural gas exports will fuel domestic political stability and geopolitical ambitions. Oil and natural gas exports to Europe are Russia’s most effective foreign policy weapons. Ironically, both countries’ ambitions are at the mercy of increased output and technological improvements in American shale oil production.


    =========================================================

    For further reading, see

    https://politicaleconomicsprof.com/2015/11/saudi-arabia-oil-and-geopolitics.html

    https://politicaleconomicsprof.com/2015/09/energy-and-geopolitics-ii-world-ex.html

    https://politicaleconomicsprof.com/2015/09/energy-and-geopolitics-i-united-states.html

    https://politicaleconomicsprof.com/2015/04/the-russian-economy-and-geopolitics-of.html

    https://politicaleconomicsprof.com/2015/04/the-death-of-opec-sheikh-rattle-and-roil.html

    https://politicaleconomicsprof.com/2015/01/changing-oil-prices-different.html

    https://politicaleconomicsprof.com/2014/12/cheaper-oil-winners-and-losers.html

    For excellent ongoing analysis of the geopolitics and economics of
    the global and national oil markets, see
    http://oilprice.com.

    The classic book on the history of the global oil industry and the
    rise of OPEC is Daniel Yergin, The Prize.

  • Note on the Current Global Oil Market

    Note on the Current Global Oil Market

    Saudi Arabia Oil Minister


    U.S. Oil Production


    Energy prices could go up
    at the same time that energy production could continue to decrease, although
    not as much as simple supply/demand forecasts would expect (see prior post).  Crude oil prices would have to rise from
    current $35/barrel level to at least $50/barrel to stabilize production and
    over $60/barrel to start increasing production. 
    Similar percent increases would be needed for natural gas.

    For most shale oil and
    natural gas producers, virtually all operating revenue is now going to debt
    payments.  After hedges come off, the
    number of bankruptcies and “distressed debt” will accelerate in second quarter
    of 2016.  The companies can continue
    production but bondholders, lenders and stockholders will suffer even larger
    losses.  This trend has already started
    in the junk bond market and the fall of public oil companies’ stock prices.


    Why Saudi Arabia Misjudged U.S. Oil Production


    While OPEC countries produce 40% of the world’s oil, there
    is no consensus on policy.  Just the
    opposite.  There are deep rifts between
    countries, as discussed in earlier posts. 


    Saudi Arabia and its allies believed that all-out production
    would quickly create a global glut, falling prices and a sharp cutback in U.S.
    and Canadian production.  Unlike most
    countries, American oil is produced by private companies that have to worry
    about profits and meeting debt obligations. 
    But over the last year, U.S. oil production has stayed high and is only
    now beginning to decline.  This has
    occurred even though the number of drilling rigs has decreased.  What the Saudis misjudged was that American
    drillers adapted to lower prices by shutting down low-producing wells, using new
    technology to increase output per well, reducing drilling costs by drilling
    deeper faster, and forcing suppliers to reduce their prices to producers.  Breakeven prices came down.  However, at $35/barrel, virtually all drillers
    are losing money.  More and more are
    having trouble meeting debt payments from operating income.  In the last two weeks, three junk bond funds
    have folded, mostly because of losses on energy junk bonds.  Total oil production is starting to decrease.


    One reason that American oil production stayed at higher
    levels than the Saudis expected is that when oil prices began to go down in
    late 2014, many drillers hedged part their production.  This means that they locked in prices higher
    than the declining market (spot) prices. 
    Revenue was higher than forecasted just from looking at market prices. 


    If I Were the Oil Minister of Saudi Arabia


    There is still too much global oil production as inventories
    continue to build up.  There is an
    estimated 30 billion barrels of oil in inventory, about 33 days of
    consumption.  The only growth sector of
    the oil industry is the building of storage facilities.  Some oil is being stored on tankers at sea. 


    Price increases will lag any production declines as
    inventory is worked down.  Global
    production will probably have to decrease by at least 2 million barrels per day
    for some time before supply comes back into balance with demand and prices rise,
    even if global demand is stagnant.


    As Saudi oil minister, I would continue all-out
    production.   Most of the American hedges
    expire in the fourth quarter of 2015 and the first quarter of 2016.  By the end of the second quarter of 2016, the
    financial condition of American drillers should be critical.  More drillers will declare bankruptcy.  But again, the decrease in production will be
    less than forecasted.  By declaring Chapter
    11 bankruptcy, drilling companies can continue in operation without the major cost
    of debt expense.  Companies will merge
    and assets will be sold.  Even given
    this, the Saudis can probably expect total U.S. and Canadian production will
    decline by about one million barrels a day.


    Besides Saudi Arabia and its allies, a number of other
    countries both within OPEC and outside OPEC would also like to decrease
    production.  Prices would rise but only
    if other countries did not raise production to take away market share. 


    With inelastic demand, the percent reduction in total output
    would be less than the percent increase in price.  Total export revenue would increase.


    If I Were Vladimir Putin


    While a number of countries might be willing to make a small
    percent reduction in production, the two wildcards are Russia and Iran.  Russia and Iran, as supporters of the
    government of Syria, are geopolitical rivals of Saudi Arabia.  But another year of low oil prices would put
    serious strains on the domestic economy and the government finances of
    Russia.  President Putin might calculate
    that the political risks of continued low oil (and related natural gas) prices
    are too high.


    Russia, one of the three largest oil producers, might keep
    production high for domestic political reasons and “free-ride” on a global
    price increase.  Iran, recently released
    from economic sanctions, has announced planned increases in production.  Russia might work out a long-term deal with
    Iran that would have economic and geopolitical benefits.  Russia would slightly cut back production
    (about 2 1/2% to start) and buy Iran’s increased output as a substitute and
    resell it to Europe.  Over time, Russia’s
    older fields would have declining production and Russia would abandon plans for
    very expensive (and unprofitable) Arctic exploration projects, which relies on
    Western technology.  Instead, Russia
    would buy increasing amounts of Iranian oil. 
    In exchange, Russia would build more nuclear power plants in Iran and
    supply Iran with uranium (and arms).  Russia
    and Iran have already agreed to the first steps of a nuclear power plant deal;
    it could be expanded as Iran sells more oil to Russia.  Both Russia and Iran would benefit from higher
    global oil prices without an explicit deal with Saudi Arabia.


    Conclusion


    Global oil production has to fall by about 2 million
    barrels/day from its current level of around 92 million barrels/day to work
    down inventories and increase prices.  By
    the middle of next year, half of the decrease will come from the U.S. and
    Canada.  So the rest of the world only
    has to decrease production by 1%-2% for prices to eventually rise.  A price increase to the $50-$60 range –
    40-70% from the current benchmark prices – would greatly increase the hard
    currency export earnings of all oil exporters and probably not lead to
    production increases in the U.S. and Canada.


    This seems like a no-brainer.  But will it happen?  A game theorist familiar with the Prisoner’s
    Dilemma would be somewhat doubtful.  These
    are not the purely rational players of game theory.  Despotic political leaders and their
    political elite more concerned about staying in power and other domestic
    concerns head many of these countries.  Some are also geopolitical rivals, often with
    an overlay of intense religious or historical animosity.  And virtually every OPEC member has a history
    of cheating on production quotas.

    ==================================================================

    A number of prior posts discuss these themes in more detail.  See the recent post on Saudi Arabia.

  • Saudi Arabia, Oil and Geopolitics

    Saudi Arabia, Oil and Geopolitics

    Saudi Oil Minister

    Introduction: The Fall in Oil Prices in 2015

    Crude oil prices temporarily rose because Saudi Arabia signaled that it
    would cooperate with OPEC and non-OPEC producers to “stabilize” oil
    prices.  Nothing specific was
    mentioned.  At the current price and for
    political reasons, it is unlikely Saudi Arabia and its Persian Gulf allies will
    cut production or negotiate joint production cuts with other large
    producers.  The comments are probably an
    indication that Saudi Arabia might be part of a global reduction in crude oil
    production if prices go much lower and the political situation in Syria changes.

    Until recently, Saudi Arabia was seeing the results it
    wanted.  Some are economic, having to do
    with the current and future price and production of oil.  The economic targets were shale production in
    the U.S and tar sands production in Canada. 
    The geopolitical targets were Iran and Russia.  But unexpected economic and geopolitical
    changes have increased the cost to the Saudis of continuing their
    policies.  Low prices will continue
    longer than the Saudis expected.  At the
    same time, geopolitical changes have made it more unlikely that Saudi Arabia can
    change its strategy or negotiate a favorable change in the global oil industry.

    Economic Goals

    Until 2014, increased production in the U.S. and Canada was
    matched by increased demand by China and other developing countries. Prices remained at record high levels, over $100/barrel.  But a continued increase in U.S. shale production combined
    with slower growth in Chinese and global demand in 2014 led to surplus
    production and rising inventories.  Since
    both global supply and global demand are inelastic, a small percentage increase
    in global supply relative to global demand led to a decrease in exports and a
    large decrease in price.  Thus far, about
    45%.

    The fall in the price of oil is part of a bigger picture,
    the fall in the price of virtually all globally-traded energy products,
    minerals, metals and agricultural products. 
    Strong growth in global demand before and after the last recession, led
    by China, encouraged countries and companies to expand capacity and production
    in almost all commodity industries.  A
    slowing of global growth resulted in excess supply and large decreases in world
    prices.  This implies that the pricing and supply problems of the global oil industry is not just caused industry variables but is part of a larger global trend of slowing manufacturing and exports.

    Oil production in many countries cannot be reduced for
    domestic political reasons. In some countries, the state owns or controls oil production and relies on oil export income for government revenue, earning hard currency to service rising foreign debt and maintaining employment and politically-necessary welfare programs and subsidies.  In countries like the United States, where oil production is done by private companies, producers try to maintain output as long as price is above marginal production costs, thus contributing to covering ongoing financial costs
    (interest and principal payments on increased levels of debt) and avoiding penalties for shutting down output of producing wells.

    Saudi Arabia and its allies knew if they cut back production
    and the price of oil rose, other countries and companies would expand
    production.  American shale production
    would continue to increase if the domestic price (WTI, a few dollars below
    Brent, the world benchmark price) stayed above $60/barrel.  At the current price range of $40-$45/barrel,
    some American production has been shut down and most drillers are
    losing money.  But total production has not gone down as far or a fast as the Saudis expected.  One reason is that many of the drillers hedged the price of some of the oil they sold when the price began to fall.  Another is that production costs are falling, partly due to new drilling technology. Their average selling price is high enough to cover lower marginal drilling and ongoing financial costs.  Some are even making a profit.

    The only question is how
    long will it take for some American shale companies to go bankrupt and the rest
    to decrease production further. 
    Apparently it is taking longer than the Saudis expected. American
    shale producers have cut costs of production, squeezed suppliers, and become
    much more efficient, reducing their marginal cost break-even price.  But a high percent of operating revenue is going to debt repayments.  A few highly leveraged producers have gone bankrupt. Production assets are being sold to other companies.

    Oil producers are still losing money, their bankers
    are getting nervous but total production has only decreased about ½ million
    barrels/day.  If oil prices don’t rise to around $60/barrel before the middle of next year, the decrease in production will accelerate.

    Many of the hedges come off this quarter and the first quarter of 2016.  We should see increased financial pressure on drillers in the second quarter of 2016.  The Saudis can wait that long to see how quickly the financial position of American producers deteriorate and if declines in production accelerate.

    Russia has also reduced its cost/barrel and break-even price by applying new technology, better organization and apparently lower taxes and fees on oil production.

    Saudi Arabia has actually increased production after
    completing a $100 billion modernization and expansion of their oil
    infrastructure.  The increased production
    and processing was for increased domestic consumption and more refining.  Exports have remained
    constant.  In the future, more of Saudi oil exports will be refined products and petrochemicals rather than crude oil.  This put them on a collision course with U.S. refineries, who have dramatically increased exports of refined petroleum products. 

    Saudi Arabia has been
    fighting hard for market share.  They
    have taken market share away from Russia in China by offering larger discounts
    off list prices.  They have also increased
    sales to Europe by also offering lower prices. 
    This is one of the benefits of being the world’s lowest cost producer
    and having a $700 billion sovereign wealth fund.  But the government is running a huge deficit relative to GDP.  At some point, the combination of lower oil revenue, large government deficits, the proxy and air war in Yemen, supporting Sunni militias in Syria, and the need for newer military equipment may force the Saudi government to reconsider its geopolitical strategy.  And, as discussed below, a change in American policy in the Middle East might be another reason for changing its oil strategy.

    A major goal of Saudi Arabia’s low-price strategy was to reduce global investment in oil exploration and production capacity.  This seems to be working.  A year of low prices has led to the
    cancellation of many oil capital projects to maintain production in old fields
    and open up new fields in other countries. 
    So far, industry analysts think about $200 billion of capital projects
    have already been cancelled or delayed. Many U.S. shale drilling rigs have been taken out of production.  This means
    less global oil production in the future, higher prices and a stronger long-term
    position for Saudi Arabia.  And possibly for the United States.  When WTI crude prices go above $60/barrel, or possibly lower with the continuing reduction in production costs, U.S. shale production will start expanding and new drilling will raise production above the recent level of 9.2 million barrels/day.

    Geopolitics and Religion: 
    Saudi Arabia, Iran and Russia

    Saudi Arabia and Russia are the world’s two largest
    exporters of oil.  Between them and with Saudi
    Arabia’s allies, they could jointly reduce exports and raise world prices.  As long as the world price stayed below $60/barrel, most U.S. shale producers would continue to lose money and probably be
    forced to reduce production further. 
    This would also reduce the economic pressure in Russia, which is in
    recession.  Russia would probably run a larger trade surplus and earn more hard currency to support domestic debt and reduce the government’s deficit. Russia might also decide to match Saudi discounts.  Europe still depends on
    Russia for most of its imported oil and natural gas.  If Russia can maintain its dominant position in Europe, the end result might be the lifting of European sanctions and more Russian interference in Ukraine.

    But geopolitics has intervened.  Iran, subject to punishing economic
    sanctions, agreed to delay its nuclear weapons program in exchange for the
    lifting of the sanctions.  This resulted in tens of
    billions of dollars becoming unfrozen and Iran could increase oil production and
    exports.  Iran has said it will use some
    of the money to modernize and expand its oil industry, increase exports by ½
    million barrels/day almost immediately and continue to increase production and
    exports in the future.  This negates the
    Saudi’s strategy of reducing global production by pressuring American shale
    producers.

    There is no way that Saudi Arabia will do a deal with Iran.  They are bitter enemies.  Besides rivals for control of the Persian
    Gulf, Iran is the leading Shia country in the Middle East and Saudi Arabia is
    the dominant Sunni country.  They are
    fighting a war by proxy in Yemen.

    To make the situation even more bitter, if possible, there
    is Syria.  The Syrian government is Shia,
    supported by Iran, and Iran’s and Syria’s client, Hezbollah.  Both Iran and Hezbollah have sent troops and
    military aid to the Syrian government, whose main opponents are Sunni, including al-Qaeda
    and Islamic State. 

    The Syrian government has long been a client state of Russia.  Vladimir Putin has decided to give military
    aid and air power support to Syria.  After Turkey shot down a Russian bomber, Russia increased the military technology, and probably the number of Russians, it based in Syria.  It
    is highly unlikely there will be a political settlement in Syria, where Shias are
    in the minority, that would be acceptable to the Syrian president, Russia, Iran, Saudi Arabia and the Sunni opposition groups. 

    Russia has also signed economic and technical agreements
    with Iran.  Any chance that Russia and
    Saudi Arabia would cooperate to reduce global oil production in the near future has disappeared.

    The United States and Saudi Arabia

    One reason that Russia has initiated more contacts with
    Iran, and supported Iran’s goals in Syria, is that it appears the Obama
    administration has been slowly moving away from the alliance with Saudi Arabia
    and towards some sort of détente with Iran. 
    Washington worked hard to come to an agreement with Iran, despite past
    animosity.  Also, American support of
    Saudi Arabia’s bombing campaign of Shias in Yemen has been almost invisible.

    The United States (and Russia) have learned some bitter
    lessons about the limits of military power in Afghanistan and the Middle
    East.  Maybe it is time to review
    America’s reliance on Saudi Arabia as an ally. 
    Think of the history:

    Going as far back as Franklin Roosevelt, the U.S. and the
    House of Saud agreed that Saudi Arabia and American oil companies would supply
    America and its allies with oil at low prices in exchange for American
    protection of Saudi Arabia and its oil fields.  Since then:

    Saudi Arabia has nationalized its oil fields and kicked out
    American oil companies (and their alien influence).

    Saudi Arabia has twice cut off oil exports to the United
    States.

    OPEC, dominated by Saudi Arabia and its allies, increased
    the price of crude oil by a factor of 10 ($3/barrel to over $30/barrel) between
    1973 and 1979.

    The Saudi government supports a fundamentalist version of
    Sunni Islam (Wahhabi) and spends money to spread its version of Islam throughout
    the Muslim world.

    Wahhabi Islam is the theological justification for al-Qaeda
    and its offshoot, Islamic State. 
    Al-Qaeda was originally begun by Saudi Arabia and America as a weapon to
    fight the Russians in Afghanistan.  After
    the Russians left, did America think that al-Qaeda would disband?  Did American leaders think that al-Qaeda
    wouldn’t go after secular Muslim states and not remember that Islam has been
    fighting against Christian states for over 1,300 years?

    15 of the 19 terrorists involved in the 9/11 attacks were
    Saudis.   None of the subsequent terrorist
    plots or bombings in the U.S. or Europe were by Shias.

    Saudi Arabia remains one of the most repressive countries in
    the world, complete with religious police.

    America no longer needs Saudi oil.  The U.S. imports only 400,000 barrels per day
    of Saudi oil, only because Saudi Arabia sends the oil to American refineries it
    partly owns.

    America’s protection of Saudi Arabia and its oil fields has come at a high price.  The United
    States committed most of its front-line military to defeat Iraq when Iraq invaded
    Kuwait and threatened nearby Saudi oil fields. 
    Subsequent military involvement in the Middle East has strained American
    military resources and diverted resources from Afghanistan.  One result has been
    the hollowing out of NATO, which could have serious consequences for America’s
    position in Europe.  Eastern European
    leaders, eager in the past to join NATO for protection from Russia, have
    expressed doubts about how much military and political support they could
    expect from NATO in light of increased Russian pressure.  America’s almost total lack of support for
    the pro-West Ukrainian government has made Eastern European governments more
    nervous and, in some states, led them to reconsider their relationship with
    Russia.  A few have called for ending
    economic sanctions against Russia.

    Conclusion: Implications for U.S. Foreign Policy

    The problem with being a global power is that all political
    and military actions in one part of the world have repercussions in other parts of the world and unintended
    consequences like blowback in the future.  This calls for a subtle and flexible set of
    foreign policies.  Adapting to changing
    circumstances and recognizing sometimes there are limited options is
    crucial.  Relying on an outdated set of
    circumstances for an alliance with a rigid Saudi Arabian government limits
    American options in the Middle East. 
    American foreign policy makers should question the wisdom of basing
    decisions in the Middle East on the geopolitical interests of a repressive
    government with no important allies in the region.

    UPDATE (January 17, 2016)

    By executing a Shiite cleric, the Saudis are
    playing a devious and dangerous game. 
    Saudi Arabia sees Shiite Iran as their main geopolitical threat and is
    very nervous about the treaty between Iran and the major powers.  By inflaming relations between Shia and Sunni
    countries, the Saudis are making it more difficult for the U.S. to follow up on
    the lifting of economic sanctions against Iran. 
    The Saudis do not want any détente between the U.S. and Iran, which
    implies a more flexible U.S. relationship with Saudi Arabia.  By executing the imam, the Saudis also hope
    it is more likely that the Iranian hard-liners, who also don’t like the treaty,
    will defeat the moderates in the current government in the upcoming  elections. 
    If they denounce or reject the treaty, the U.S. is once more dependent
    on Saudi Arabia as the foundation for its Middle East policy.  Iran will then be forced to strengthen its
    ties to Russia and China.

    At the same time, the Saudis continue to flood
    the global oil market, leading to even lower prices.  The main target of this strategy is the U.S.
    shale oil industry.  The Saudis hope to
    force the industry to drastically cut production because of heavy financial
    losses.  So far this hasn’t happened but
    virtually the entire industry is losing money (negative cash flow).  On the positive side for the Saudis, the U.S.
    and global oil industry is cutting investment, implying less
    production capacity in the near future. Lower prices is leading to investment by the U.S. shale producers in new technology to reduce extraction costs.

    The Saudis seem to believe that the United
    States government can mentally separate the Saudi’s geopolitical strategy from
    the Saudi’s oil strategy.  They may be
    right.

    Saudi Arabia had a sovereign wealth fund of about $700 billion at the beginning of 2014.  Their government deficit is running at around $100 billion per year.  Cost reductions are politically dangerous because over 80% of Saudis, directly or indirectly, receive their income from the government.  The government runs large social welfare programs and subsidizes the cost of food, fuel and electricity. Over 80% of the country’s export revenue and government revenue come from oil exports.  I would guess that the Saudi government will start to reconsider their oil export strategy sometime in the fourth quarter of this year.